
Global Digital Payment Gateway Market Report, Size, Share and Forecast 2026–2033: Twenty-Six Basis Points, Falling
Global Digital Payment Gateway Market, 2026–2033: Snapshot
| Metric | Value |
|---|---|
| Market size, 2025 | USD 35,251.0 million |
| Market size, 2033 | USD 60,307.3 million |
| CAGR, 2026–2033 | 6.94 per cent |
| Increment, 2025–2033 | USD 25,056.3 million |
| Processed volume, 2025 | USD 13,200.0 billion |
| Processed volume, 2033 | USD 30,305.6 billion |
| Volume CAGR, 2026–2033 | 10.95 per cent |
| Blended take rate, 2025 | 26.71 basis points |
| Blended take rate, 2033 | 19.90 basis points |
| Largest channel, 2025 | Regional domestic acquirer-gateways — 44.00 per cent |
| Fastest-growing channel | Gateway software, orchestration and white-label — 12.37 per cent |
| Base year / forecast window | 2025 / 2026–2033 |
| Currency and unit | USD, millions |
What this report actually counts
A payment gateway market can be drawn at four different widths, and most published figures do not say which one they used. This report uses the narrowest commercially meaningful one.
In scope: fee revenue earned by third-party platforms that authorise, route, tokenise and settle a payment for a merchant — processing fees charged in basis points, acquirer spread, platform and subscription fees, and FX or payout margin on the same transaction. The base is the net revenue of that layer.
Out of scope, and disclosed rather than quietly included: interchange, which is set by issuing banks and scheme rules and passes through to issuers; scheme and assessment fees, which accrue to the networks; terminal and hardware revenue; and the cost of credit risk where an acquirer carries it. Including interchange would roughly triple the number and would describe the card networks' economics rather than the gateway's.
The consequence is a market that looks small against the volume it moves. USD 35,251.0 million of gateway revenue sits on USD 13,200.0 billion of processed volume — 26.71 basis points. That ratio, not the dollar total, is what to forecast, because volume and price do not move together. Between 2025 and 2033 processed volume compounds at 10.95 per cent and revenue compounds at 6.94 per cent. The whole of the difference is the take rate falling to 19.90 basis points.
Table of contents
- Market definition and scope
- Executive summary
- Market size and forecast, 2025–2033
- 3.1 The take-rate build, channel by channel
- 3.2 Channel table, 2025 and 2033
- 3.3 Volume and price, decomposed
- 3.4 Reconciliation to the previous edition of this report
- 3.5 Regional distribution of processed volume
- Competitive landscape and market structure
- Value chain: the four ways a gateway gets paid
- Investment activity and capital flows
- Technology and innovation
- Market risk and disruption
- Regulatory and policy environment
- Method, sources and the primary-research layer
- About Pheonix Research
- Disclaimer
Market size and forecast, 2025–2033
3.1 The take-rate build, channel by channel
The market is built from volume and price rather than extrapolated from a headline. Four channels are separated because they are priced by different mechanisms and bought by different people: an enterprise merchant choosing one platform for online and in-store, a small business signing up to a developer platform, a domestic merchant buying acceptance from an acquirer that happens to run a gateway, and a merchant buying orchestration or a white-label licence on top of somebody else's processing.
Each channel is sized as processed volume multiplied by the net take rate that volume attracts. Take rates are calibrated to the two public revenue disclosures that make the layer observable — Adyen and GMO Payment Gateway — plus Stripe's disclosed volume, which is paired with a Pheonix estimate of its net revenue to produce 30.74 basis points. Stripe publishes processed volume and says only that it remained profitable; it does not publish revenue, and the table in section 4 says so at the line. The calibration is set out in section 4.
3.2 Channel table, 2025 and 2033
| Channel | 2025 volume (USD bn) | 2025 take rate (bps) | 2025 revenue (USD m) | Share 2025 | 2033 revenue (USD m) | Share 2033 | CAGR |
|---|---|---|---|---|---|---|---|
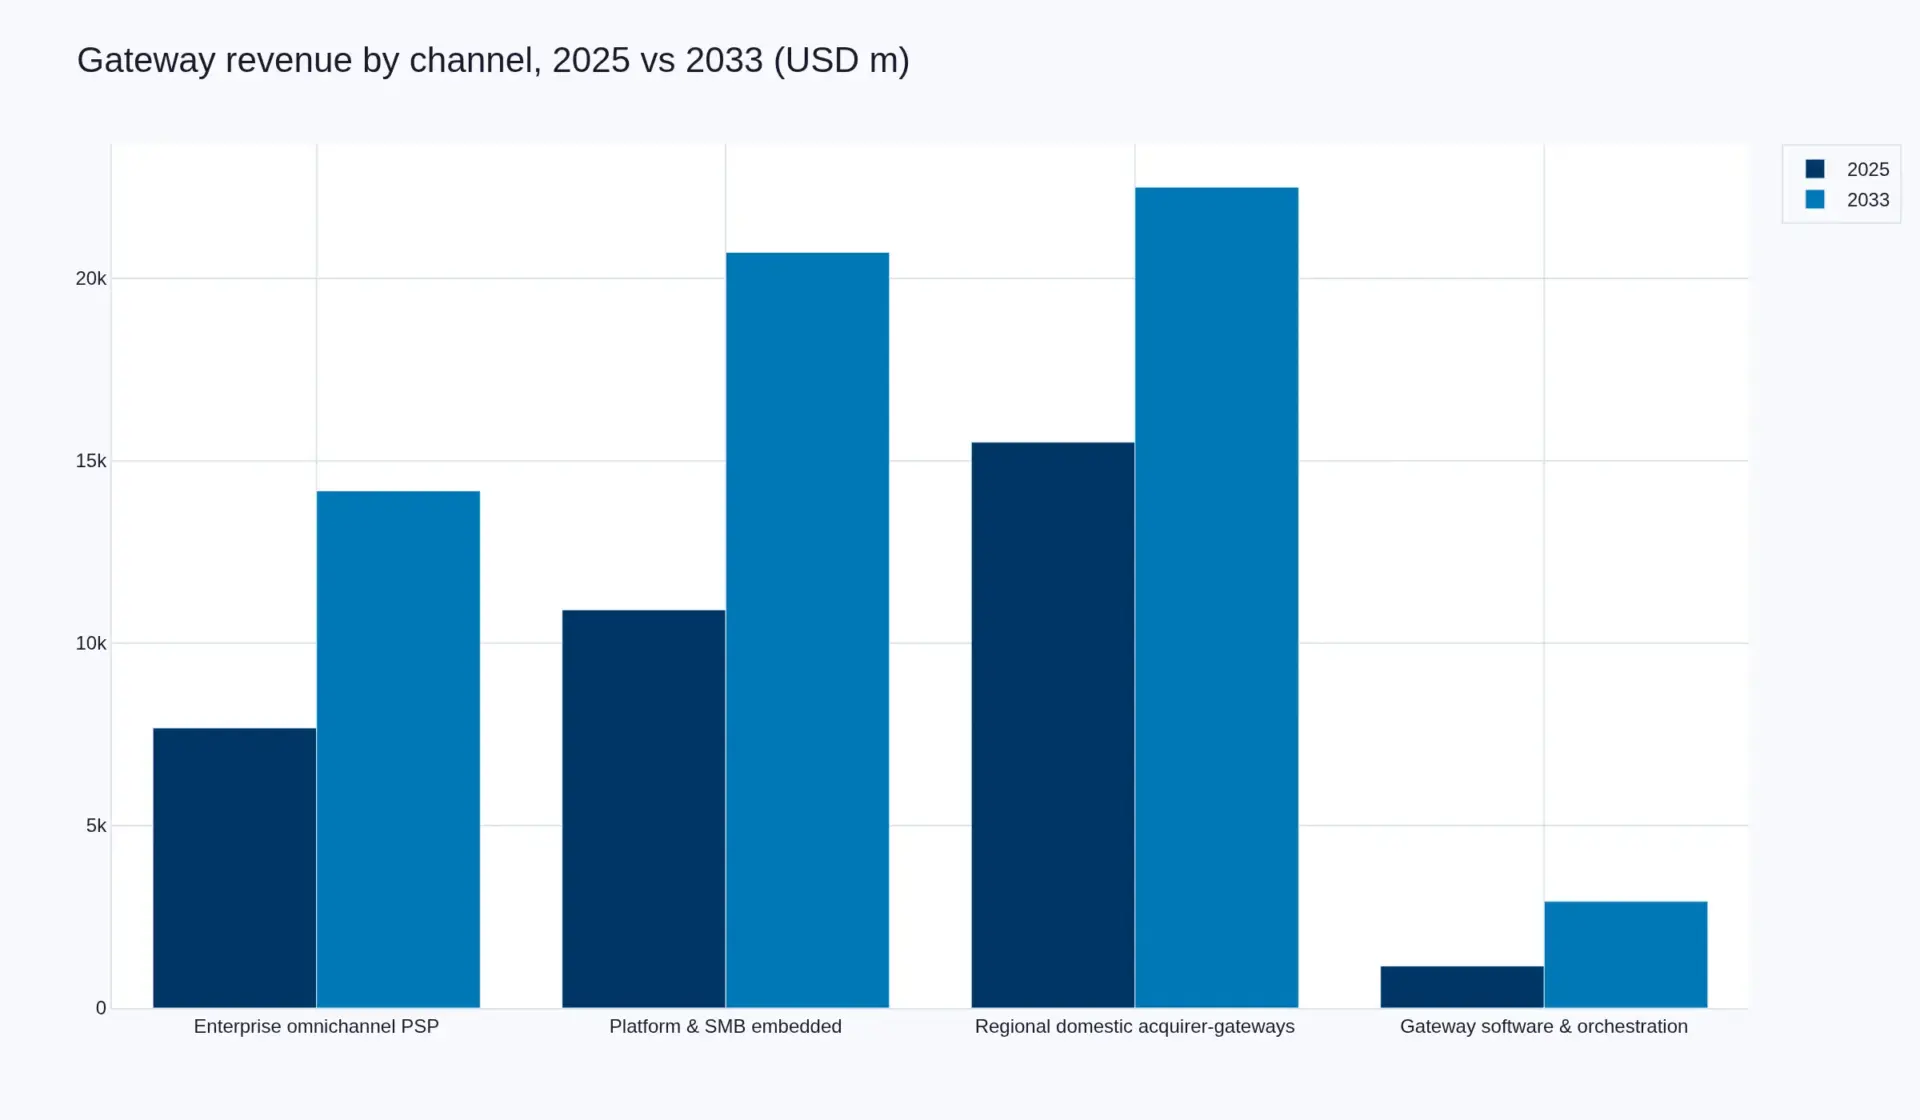
| Enterprise omnichannel and cross-border PSP | 5,050.0 | 15.20 | 7,676.0 | 21.78% | 14,174.1 | 23.50% | 7.97% |
| Platform and SMB embedded payments | 3,700.0 | 29.50 | 10,915.0 | 30.96% | 20,711.2 | 34.34% | 8.34% |
| Regional domestic acquirer-gateways | 3,300.0 | 47.00 | 15,510.0 | 44.00% | 22,499.6 | 37.31% | 4.76% |
| Gateway software, orchestration and white-label | 1,150.0 | 10.00 | 1,150.0 | 3.26% | 2,922.4 | 4.85% | 12.37% |
| Total | 13,200.0 | 26.71 | 35,251.0 | 100% | 60,307.3 | 100% | 6.94% |
3.3 Volume and price, decomposed
Two numbers carry the forecast. Volume grows at 10.95 per cent a year, which is not heroic: it is roughly what a market whose card-not-present base compounds at low double digits, while cash converts to card in several large emerging economies, should do. The take rate falls from 26.71 to 19.90 basis points — a 25.5 per cent decline in the price of the service over eight years.
That decline is not a forecast of a price war. It is a forecast of mix, and three things push the blended rate down with none of them requiring anyone to behave badly. The largest merchants negotiate against a marginal cost close to zero, so their share of volume grows faster than their share of revenue. Regulatory intervention drives domestic interchange-free rails which the gateway layer must still process, at a fraction of the card rate. And the fastest-growing channel by volume is the one where the platform earns less per dollar because the merchant does more of the work.
Read the model as a spread, not a point. Hold the take rate flat and the market reaches USD 80,946 million by 2033. Hold volume flat and let price fall, and it contracts to USD 26,268 million. Reality sits between them; the base case leans toward price.
3.4 Reconciliation to the previous edition
The previous edition of this report put the market at USD 36.80 billion in 2025, USD 95.60 billion in 2033, and a 12.70 per cent CAGR. The 2025 figure was close to the truth by accident. The 2033 figure was not.
This edition measures USD 35,251.0 million in 2025 — 4.2 per cent below the old number, well inside the tolerance of two different methods — and USD 60,307.3 million in 2033. The legacy 2033 figure overstates the market by 58.5 per cent, and its growth rate is 5.76 percentage points too high. The gap is entirely method: a top-down projection of digital commerce applied to a layer whose revenue is a percentage of that commerce, but a percentage that is falling. Growth in the thing being processed was mistaken for growth in the fee for processing it.
3.5 Regional distribution of processed volume
Asia-Pacific is the largest regional pool by purchase volume and the least valuable per dollar at the gateway layer, because a large share of it travels on domestic rails priced at or near zero. The Nilson Report puts purchase volume generated by cards issued in Asia-Pacific at USD 15.527 trillion in 2025, against USD 6.307 trillion for Europe; Visa and Mastercard alone generated USD 17.136 trillion in the first nine months of 2025, on 828.10 billion purchase transactions worldwide across all six global networks. That is the denominator. The gateway layer earns a low single-digit multiple of basis points on most of it, and materially more only where the merchant is cross-border, the currency is not the merchant's own, or the transaction is high-risk.
Read regionally, the market inverts: Asia-Pacific dominates volume and North America and Europe dominate revenue. For the banking and identity layers underneath, see our Global Digital Banking Market and Anti-Money Laundering coverage; for the demand side that sets these volumes, see Global E-Commerce, and for acceptance inside the world's third-largest cashless market see our Japan Digital Payment Acceptance report, where the same net-of-interchange basis yields 61.4 basis points against 26.71 here.
Why the fee, and not the volume, is the market
At the market level, volume growth outruns revenue growth by four points a year in this forecast, and the mechanism is visible in the largest platforms' own disclosures — usually read backwards. Adyen processed 21 per cent more value in 2025 than in 2024 excluding a single large customer, and 8 per cent more including it, while net revenue rose 18 per cent. Read the three together: thirteen percentage points of that platform's growth came from the book, not from its largest account, and revenue grew faster than reported volume, which is why Adyen's own blended rate rose in 2025 while the layer's fell. That is not a growth-dilution story; it is a level story. A merchant large enough to move that much volume is priced against its own alternatives rather than against the processor's cost, and the existence of such accounts sets the reference price for everything negotiated beneath them.
The forecast consequence is that a gateway's revenue is not a function of how much the world spends. It is a function of where the world spends, who is large enough to negotiate, and what the local rails cost to process. Three of those four are moving against the incumbent layer.
Articles on this market
Two supporting analyses extend the findings in this report, both built from the same figures and the same net-of-interchange basis.
- Volume Grows 10.95 Per Cent. The Fee for Processing It Grows 6.94. — why the previous edition of this market overstated 2033 by 58.5 per cent, and where the revenue actually sits channel by channel.
- The Same Processing Function Earns 16.96 Basis Points and 55.66. Nothing About the Software Differs. — the 3.28x spread between Adyen and GMO Payment Gateway, and why only two stages of the chain are contestable by software.
Table of Contents
1. Market Definition and Scope
1.1 What the gateway layer is 1.2 What is included 1.3 What is excluded, and why 1.4 The net-revenue principle 1.5 Reconciliation to an interchange-inclusive definition
2. Executive Summary
2.1 Market Snapshot, 2025-2033 2.2 The take rate, not the volume 2.3 Three pricing regimes 2.4 The thirteen points that came from everyone else 2.5 Analyst Viewpoint
3. Market Size and Forecast, 2025-2033
3.1 The take-rate build, channel by channel 3.2 Channel table, 2025 and 2033 3.3 Volume and price, decomposed 3.4 Reconciliation to the previous edition 3.5 Regional distribution of processed volume 3.6 Sensitivity: flat price and flat volume
4. Competitive Landscape and Market Structure
4.1 Three take-rate bands, one function 4.2 Enterprise omnichannel and cross-border PSPs 4.3 Platform and SMB embedded payments 4.4 Regional domestic acquirer-gateways 4.5 Gateway software and orchestration 4.6 Consolidation logic 4.7 What competition is actually about
5. Value Chain: The Four Ways a Gateway Gets Paid
5.1 Processing fee 5.2 Acquirer spread 5.3 Platform and subscription 5.4 FX and payout margin 5.5 Stage-by-stage margin characteristics 5.6 Why the merchant’s real cost is not the fee
6. Investment Activity and Capital Flows
6.1 A business that scales without a balance sheet 6.2 What capital buys: authorisation, coverage, volume 6.3 Capability acquisitions versus licence consolidation 6.4 Buybacks and margin 6.5 What to conclude
7. Technology and Innovation
7.1 Completion, not price 7.2 Network tokenisation 7.3 Verification of payee 7.4 Orchestration and smart routing 7.5 Agentic and machine-initiated commerce 7.6 Real-time account-to-account rails 7.7 Stablecoin and programmable settlement 7.8 The maturity question
8. Market Risk and Disruption
8.1 Rail substitution 8.2 Merchant concentration and take-rate dilution 8.3 Licensing and sponsor dependence 8.4 Fraud, chargeback and liability shift 8.5 Operational concentration 8.6 Agentic mandates and the credential 8.7 What is not a risk
9. Regulatory and Policy Environment
9.1 Four regulatory layers, not one 9.2 Licensing and safeguarding 9.3 Interchange: capped in Europe, disclosed in Japan, unpriced in the United States 9.4 The Instant Payments Regulation and price parity 9.5 Verification of payee as infrastructure 9.6 Security standards and scheme rules 9.7 Forward outlook to 2033
10. Method, Sources and the Primary-Research Layer
10.1 Secondary sources, named 10.2 Primary layer, and what it cannot do 10.3 Arithmetic, rounding and the two sensitivity bounds 10.4 Exclusion of third-party market-research estimates
11. About Pheonix Research
12. Disclaimer
Competitive Landscape
Competitive landscape and market structure
Three take-rate bands, one function
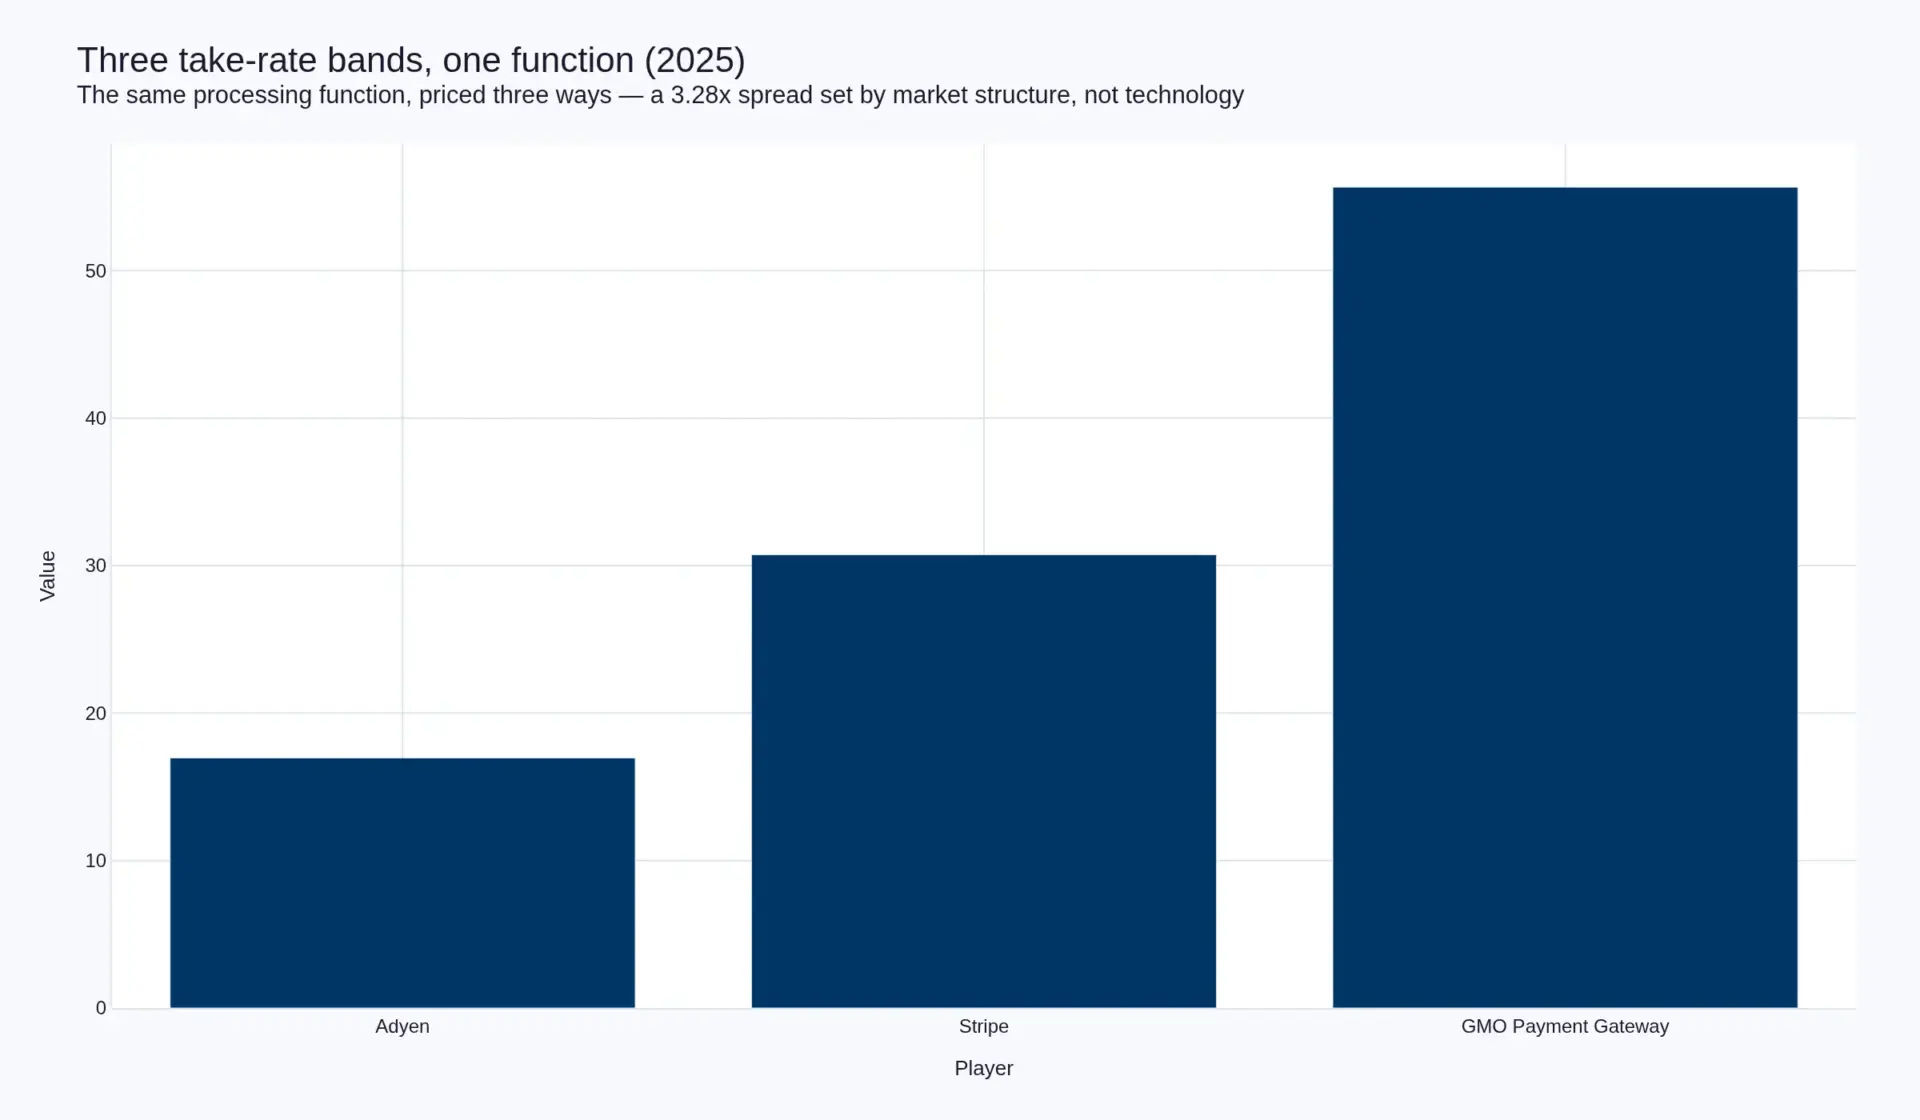
The market is not one market. It is three pricing regimes that happen to do the same thing, and the distance between them is the most useful single observation in this report.
| Provider | 2025 volume | 2025 net revenue | Take rate | What sets the rate |
|---|---|---|---|---|
| Adyen | EUR 1,394.3 bn | EUR 2,364.2 m | 16.96 bps | Enterprise mix, single platform, one large-volume account |
| Stripe | USD 1.9 tn | approx. USD 5.84 bn — Pheonix estimate; Stripe does not disclose revenue | 30.74 bps | SMB and platform mix, software attached to processing |
| GMO Payment Gateway | JPY 2.0 tn per quarter | JPY 11,132.2 m per quarter | 55.66 bps | Acquiring spread inside a domestic interchange structure |
The 3.28x gap between Adyen and GMO Payment Gateway is not a technology gap and not an efficiency gap. It is a market-structure gap. GMO earns an acquiring spread because Japanese merchant fees are set at 3.25 per cent at the standard tier; Adyen earns a processing fee on merchants who have already unbundled acquiring. Stripe sits in between because it sells software alongside the transaction.
The thirteen points that came from everyone else
Adyen’s 2025 disclosure contains the sector’s most instructive sentence: processed volume rose 21 per cent year on year excluding a single large-volume customer, and 8 per cent including that customer, while net revenue rose 18 per cent. Read those three numbers together and the structure of the market becomes visible. The largest account on a EUR 1.4 trillion platform is large enough to halve its growth rate, and it is priced at a level that barely moves the revenue line — which is why the platform’s blended rate rose in 2025 while the layer’s fell, and why both the growth and the revenue came from the book beneath it.
This is what a take-rate business looks like at the top. The largest merchants in the world price processing against their own credible alternative — building it, or moving it — and the marginal revenue on their volume approaches the marginal cost of serving it. Every additional point of volume those merchants bring dilutes the blended take rate, which is why a market can grow volume at 10.95 per cent and revenue at 6.94 per cent without anybody losing a customer.
Structure: moderately consolidated at the top, fragmented below
Ten providers operate at global scale in the enterprise and platform channels, and the revenue in those two channels is 52.74 per cent of the market in 2025 rising to 57.84 per cent in 2033. Beneath them sit hundreds of domestic acquirer-gateways, each holding a local interchange structure, a local licence and a merchant base that a global platform reaches only through partnership or acquisition.
That split explains the consolidation pattern. Global platforms consolidate capability — orchestration, fraud, payouts, terminals — because that is what raises take rate. Acquirers consolidate volume because that is what amortises a licence and a balance sheet. The two strategies produce very different multiples for the same sector, and the market’s M&A activity has for several years been a reallocation between them rather than a wave of like-for-like mergers.
What competition is actually about
Not price. Price is where competition is reported. Three things decide who wins an account, in the order merchants describe them:
- Authorisation uplift. The share of attempted payments that complete, measured by method, issuer country and device. A one-point improvement on a low-margin merchant is worth more than a materially lower fee.
- Coverage of the methods that actually clear. A market where 82.7 per cent of cashless value is card and 10.2 per cent is code — as Japan is — rewards the provider that settles both on one contract, not the one that is cheapest on card.
- Operational depth. Settlement timing, chargeback handling, reconciliation and the quality of the integration team. Unglamorous, and the most common reason an incumbent is replaced.
The implication for anyone buying or building in this market is uncomfortable but simple: the price competition that produces the take-rate series in this report is real, and it is being fought over a service that merchants do not primarily choose on price. Providers that compete only on basis points are competing for the accounts that will leave them next year.
Value Chain
Value chain: the four ways a gateway gets paid
The gateway layer is usually described as a piece of software. Commercially it is four revenue lines on the same transaction, and the mix between them explains almost every difference in take rate between one provider and the next.
The four lines
- Processing fee. A fixed rate in basis points on the value processed, sometimes with a per-transaction component. This is the line most people mean by “gateway”. It is the most visible and the easiest to negotiate away.
- Acquirer spread. Where the provider is also the acquiring entity, it keeps the difference between the merchant discount it charges and the interchange plus scheme fees it pays. This is the largest single line for domestic acquirer-gateways and the main reason their take rate is high.
- Platform and subscription. Fixed monthly or per-seat charges, modules, terminal rental, fraud tooling. Recurring and price-insensitive, which makes it the most valuable revenue a gateway has.
- FX and payout margin. The spread on currency conversion and on cross-border settlement. Invisible to most merchants and, on cross-border volume, frequently larger than the processing fee itself.
GMO Payment Gateway publishes this split, which makes it the cleanest public decomposition of a gateway’s P&L. In its most recent reported quarter the four lines were: initial revenue JPY 1,754.2 million, stock and recurring JPY 1,723.1 million, transaction fee JPY 2,923.0 million, and merchant-acquiring spread JPY 4,731.9 million, for a total of JPY 11,132.2 million on consolidated processed value of JPY 2.0 trillion and 0.97 billion transactions. Its transaction-fee line alone is 14.6 basis points; the blend, with acquiring spread included, is 55.66.
Stage by stage
| Stage | Who performs it | How they are paid | Margin characteristic |
|---|---|---|---|
| Issuance and credit | Issuing banks, card issuers | Interchange | Regulated and capped in most markets |
| Network and clearing | Card schemes, domestic switches | Assessment and scheme fees | Fixed percentage, effectively a toll |
| Acquiring and settlement | Acquirers, sponsor banks | Spread over interchange | Balance-sheet and licence dependent |
| Gateway and processing | PSPs, gateway platforms | Basis points on value, plus per-transaction | Software economics, highly scalable |
| Orchestration and tooling | Independent orchestration, fraud, reconciliation | Subscription plus per-transaction | Highest gross margin in the chain |
| Merchant | Retailer, marketplace, platform | Pays the discount, absorbs the fraud | Bears the authorisation risk |
Why the chain matters to the forecast
Two structural facts follow from the chain and both bear on the 19.90 basis points in 2033.
First, only the last two stages are contestable by software. Issuance, clearing and acquiring are licence- and balance-sheet businesses. That is why every serious gateway eventually tries to own acquiring — it is where the spread sits — and why the pure-processing fee compresses toward its own cost.
Second, the merchant’s real cost is not the fee. It is the fee multiplied by the share of attempted payments that are declined, plus the operational cost of recovering them. A provider that raises authorisation by one percentage point on a three per cent margin business is worth more than one that cuts its rate by five basis points. This is the single most important commercial fact in the market and the reason price competition has not consolidated it as fast as the take-rate series implies.
The primary layer of this research — merchant-side payments leads, interviewed across six markets, and the procurement conversations at the industry conferences where acquirers and merchants meet — consistently describes the decision the same way: cost is negotiated annually, authorisation is reviewed monthly, and the monthly review is what gets a provider replaced. The take rate is the number in the contract. The authorisation rate is the number in the board pack.
Investment Activity
Investment activity and capital flows
The revenue does not require capital, and that is the point
A gateway is one of the few financial businesses that scales without a balance sheet. Adyen’s 2025 accounts make the ratio explicit: EUR 1,245.7 million of EBITDA on EUR 2,364.2 million of net revenue, a 53 per cent margin, with capital expenditure at 5 per cent of net revenue and free cash flow conversion of 87 per cent. Stripe, privately held, reports that its Revenue suite is on track for a USD 1 billion annual run rate on top of processing.
This is why the sector’s investment question is not “how much capital does it take” but “what does the capital buy”. There are only three honest answers, and the market prices them very differently.
| What capital buys | Observed example | Effect on take rate | Effect on multiple |
|---|---|---|---|
| Authorisation performance | Issuer connectivity, tokenisation, retry logic | Protects the rate by making the provider non-substitutable | Highest, because it is the merchant’s own KPI |
| Method coverage | Local rails, wallets, bank transfers, code payments | Raises rate where local rails carry acquiring spread | Moderate; coverage is copyable within a cycle |
| Volume acquisition | Discounting to a single large merchant | Lowers the blended rate immediately | Negative if unmanaged; Adyen’s single large account is the worked example — 13 points of its growth came from everyone else |
Where the money actually went in 2025
Three patterns dominate. First, capability acquisitions: orchestration, fraud scoring, reconciliation, embedded lending and payouts, each bought to widen the revenue line rather than the volume. Second, licence and acquiring consolidation, where a processor buys its way into a domestic spread it cannot build. Third, and least discussed, nothing: a large share of the sector’s capital now goes to buybacks and margin rather than to expansion, because the enterprise channel is consolidated and the growth in volume is arriving at a price nobody wants to buy.
The signal to watch is not the size of a round or a deal. It is whether the acquired capability can be attached to existing volume at near-zero marginal cost. Stripe’s revenue suite is the model: software sold to merchants already processing on the platform, earning a subscription on a transaction it was going to see anyway. That is the only growth in this market that does not dilute the take rate, and it is why the gateway-software channel in this report grows at 12.37 per cent — the fastest of the four — from the smallest base.
What to conclude
Capital allocation in this sector has become a statement about which half of the business an operator believes in. Money spent on authorisation and software defends the take rate. Money spent on volume buys growth that the model in this report assumes will be priced at close to zero. Both are rational. Only one of them shows up in a revenue CAGR.
Technology & Innovation
Technology and innovation
The technology is not there to cut the price
Almost every innovation in this layer has the same commercial purpose: to complete a payment that would otherwise fail, or to make a payment possible on a rail the merchant could not otherwise reach. Neither reduces what the merchant pays. Both make the provider harder to replace. That is why the take rate can fall at the blended level while individual providers hold or raise their rate on the accounts they care about.
What is actually moving
| Capability | What it changes | Who captures the value |
|---|---|---|
| Network tokenisation | Replaces the card number with a scheme-issued token that survives card replacement | The provider that holds the token — it becomes the system of record |
| Verification of payee | Checks the account name against the identifier before a credit transfer is sent, returning match, close match, no match | Banks and the account-to-account rails; gateways that wrap it capture the workflow |
| Orchestration and smart routing | Sends each transaction to the acquirer most likely to authorise it | The orchestrator, because it owns the measured outcome rather than the price |
| Agentic and machine-initiated commerce | Moves the payment decision from a person at a checkout to a program executing an instruction | Whoever holds the credential and the mandate — an identity problem, not a processing one |
| Real-time account-to-account rails | Removes the card and its interchange from the transaction entirely | The merchant, if the rail is priced near zero; the gateway only if it is the integration layer |
| Stablecoin and programmable settlement | Changes the settlement leg, not the authorisation leg | Treasury and payout products, where the FX margin already sits |
Two of these are deflationary and four are not
Tokenisation, orchestration, agentic credentials and payout settlement all either defend or extend the fee. Verification of payee and real-time account-to-account rails are different: they exist to move a payment onto a rail that has no interchange, and the gateway’s role narrows to integration. That is the mechanism behind the 19.90 basis points at the end of the forecast window — not a price war, but a slow substitution of card volume by rails that clear at a fraction of the cost and therefore earn the gateway a fraction of the fee.
The European instant payments regime is the clearest live example. Under the Instant Payments Regulation, euro-area payment service providers had to be able to receive instant credit transfers from 9 January 2025 and to send them, with verification of payee, from 9 October 2025; electronic money institutions and payment institutions follow on 9 April 2027, and non-euro-area member states on 9 July 2027. Charges for instant transfers may not exceed charges for standard credit transfers. When a rail is mandated, priced at parity and equipped with a name-checking service, the case for routing a domestic payment through a card collapses from both ends at once.
The maturity question
This is a mature technology market with a low patent intensity: the innovation is in configuration and coverage rather than in protected mechanism. That has a specific consequence for anyone forecasting it. There is no defensible technology moat to sustain a price premium, so the only durable advantages are data (authorisation performance on a specific merchant’s traffic), coverage (the number of rails settled on one contract) and switching cost (the integration and the reconciliation). All three are real. None of them shows up in a technology roadmap, which is why the sector’s own narrative about innovation is a poor guide to its revenue.
Market Risk
Market risk and disruption
The volume is the safe part of this forecast
Processed volume is about as forecastable as any series in financial services: it tracks nominal consumption, e-commerce penetration and the conversion of cash to card, and all three have been stable and directionally clear for a decade. The uncertainty in this report sits almost entirely on the price side, and it is structural rather than cyclical.
Risk 1 — rail substitution, and it is already legislated
The clearest threat to this layer is not a competitor. It is a rail with no interchange inside it, mandated to be reachable, priced at parity with a standard transfer and equipped with a name-checking service. Europe has legislated exactly that, with a phased timetable running to 2027. Every domestic card transaction that moves to an account-to-account rail leaves the gateway earning an integration fee instead of a percentage of the value.
This is the mechanism, not a forecast of collapse. It is also the reason the take rate falls in this report even though no participant is assumed to behave badly. The plausible range is wide, and it is disclosed in section 3.6: hold price flat and the market reaches USD 80,946 million by 2033; hold volume flat and it contracts to USD 26,268 million.
Risk 2 — merchant concentration and dilution
The largest merchants price processing against their own credible alternative — building it, or moving it — and the marginal revenue on their volume approaches the marginal cost of serving it. Adyen’s own disclosure made this visible: processed volume rose 21 per cent excluding a single large customer and 8 per cent including that customer, while net revenue rose 18 per cent. Thirteen percentage points of that platform’s growth sat in the rest of the book, and the largest account on it is priced at a level that barely moves the revenue line.
This risk is unusual in that it raises with success. A provider that wins a very large merchant grows volume faster than revenue, and its blended take rate falls regardless of what happens to any other account.
Risk 3 — licensing and sponsor dependence
A provider that reaches settlement through a partner bank or a sponsor holds its permission at one remove. It is a commercial dependency that does not appear in a take rate, and it becomes acute exactly when a provider is growing fastest in a new geography. It is also the reason cross-border expansion in this layer tends to happen through acquisition of a licensed entity rather than through organic build.
Risk 4 — fraud, chargeback and liability shift
Fraud does not reduce the fee directly; it reduces the merchant’s tolerance for the provider. Card-not-present fraud, account takeover and credential phishing all land on a merchant as disputes and as lost goods, and the scheme rules that allocate that liability can move against the accepting side. A provider that cannot demonstrate better authorisation and lower fraud on a merchant’s own traffic is exposed at the annual review, whatever its rate.
Risk 5 — operational concentration
This layer is a single point of failure for its merchants’ revenue. An outage during a peak trading period is not an inconvenience; it is a measurable loss the merchant will attribute to the provider and act on. Concentration risk runs the other way too: a platform that depends on one upstream acquirer or one region’s infrastructure inherits that dependency in its own uptime record.
Risk 6 — agentic commerce and the credential
Machine-initiated purchasing moves the payment decision from a person at a checkout to a program executing an instruction. Whoever holds the credential and the mandate owns that transaction, and it may not be the party that processes it today. The risk is not that payments stop; it is that the layer which authenticates the agent captures the relationship, and the layer which clears the transaction is reduced to a utility.
What is not a risk, and is often sold as one
Tokenisation, orchestration, fraud scoring, payouts and programmable settlement all either defend or extend the fee. They are frequently presented as disruption when they are in fact the moat. And distributed-ledger settlement changes the settlement leg, not the authorisation leg — it does not remove the need for someone to decide whether a payment should complete, and that decision is what merchants pay for.
The joint risk that matters
The risks above are not independent. A market where the substitute rail is mandated, the largest merchants negotiate at marginal cost and the credential migrates to an agent platform is a market with a falling take rate and rising volume — which is exactly the base case in this report, and the reason its revenue CAGR is 6.94 rather than the 12.70 per cent of the previous edition.
Regulatory Landscape
Regulatory and policy environment
Four layers, and only one of them is about price
This market is regulated by four different things, and conflating them is the most common error in commentary on it. Licensing and safeguarding determine who may hold a merchant’s money and for how long. Interchange rules determine how much of the merchant discount belongs to the issuing bank rather than to this layer. Security and scheme standards determine what a provider must implement to be allowed to process at all. Competition and transparency rules determine whether the fee can be seen. Only the second and fourth touch the revenue line in this report, and only indirectly.
Interchange: three regimes, three different markets
Interchange is the fee an acquirer pays an issuer on a card transaction, and it is the largest single component of a merchant discount. It is also the boundary of this market: it accrues to the issuing side, so every change to it moves the merchant’s cost without moving the gateway’s revenue — except where the gateway is also the acquirer, in which case the spread it earns is set as a residual over interchange and moves with it.
The world divides into three regimes, and they produce the three take-rate bands in section 4.
- Europe capped it by regulation. Consumer interchange is capped by law, which compresses the merchant discount and, with it, the absolute spread available inside a domestic card transaction. The consequence is a market where the processing fee must be earned on service rather than on spread.
- Japan disclosed it. Under METI and Japan Fair Trade Commission coordination the card networks — Visa, Mastercard and UnionPay — published their standard credit-card interchange rates in 2022, and JCB published its own merchant-fee allocation ratio in 2023: roughly a quarter of the merchant discount to the acquirer, three quarters to the issuer, with the underlying rates left unpublished. Nothing is capped. What changed is that a merchant can now see which party to negotiate with — and a domestic acquirer that earns its living on the residual over a now-published number has a visible ceiling.
- The United States left it to scheme rules and to partial debit regulation. The widest spread sits here, which is why domestic American acquirers and the platforms that serve them earn materially more per dollar than a European or an enterprise cross-border PSP.
For this forecast the implication is mechanical. A gateway’s take rate is what remains after interchange and scheme fees are taken out of the merchant discount. Where interchange is capped, the remainder is small and must be defended by service. Where it is disclosed, the remainder is visible and must be defended in negotiation. Where it is unpriced, the remainder is wide and attracts entrants.
The Instant Payments Regulation is the real policy event
The European instant payments regime matters more to this market than any interchange rule, because it attacks the card transaction from the rail underneath it. Euro-area payment service providers had to be able to receive instant credit transfers from 9 January 2025, and to send them with verification of payee from 9 October 2025; electronic money institutions and payment institutions follow on 9 April 2027, and non-euro-area member states on 9 July 2027. Charges for instant transfers may not exceed charges for standard credit transfers.
Three design choices in that regime are worth separating, because they do different things to the gateway layer. Mandatory reachability makes the rail universal, so a merchant cannot be told the rail is unavailable. Price parity makes it cheaper than a card, permanently, by statute rather than by competition. And verification of payee — the name-check before a transfer is sent, returning match, close match or no match — removes the single largest reason merchants have refused account-to-account payment: the fear of sending goods against a mistyped account.
Together they convert a domestic card payment from the default into a choice. That is the mechanism behind the 19.90 basis points at the end of the forecast window, and it is regulatory rather than commercial, which is why it is more reliable than a forecast of a price war.
Licensing and safeguarding
Whoever holds a merchant’s funds between authorisation and settlement is doing something a regulator cares about, and the perimeter differs by jurisdiction. The practical consequence for market structure is that the ability to process a payment and the permission to hold its proceeds are separate capabilities, and many providers buy the second through a sponsor or partner bank. That is why the enterprise channel is dominated by a small number of licensed institutions with balance sheets and why the software layer above it is so much more contestable.
Security standards and scheme rules
Card data security standards and scheme mandates are the entry ticket rather than a differentiator. Their commercial effect is to raise the fixed cost of being a provider and therefore to favour scale. Two current mandates matter for the revenue line: network tokenisation, which replaces the card number with a scheme-issued token that survives card replacement, and the move of authentication decisions from the merchant to the issuer. Both reduce fraud. Both also make the provider holding the credential harder to replace, which defends the fee.
Forward outlook to 2033
Three expectations shape the regulatory path in this forecast. Instant payment reachability and price parity extend beyond the euro area, so the substitute for a domestic card transaction becomes available in more markets and at a lower price. Transparency spreads in the disclosure direction rather than the capping direction outside Europe, because it is politically easier and because it works. And agentic commerce forces a new permission layer — a mandate that proves a program is authorised to spend a consumer’s money — which will be written as financial regulation, not as technology standards.
The regulatory risk to this forecast is therefore not a cap on gateway fees, because no jurisdiction caps them. It is that the substitute rail arrives faster than the base case assumes. That would be good for merchants, good for consumers, and bad for anyone who bought this layer on its historical spread.