
??India - Analyse de la part et de la taille du marché de la vidéosurveillance 2025-2033
India's video surveillance market is USD 5.6 billion in 2025 and USD 12.1 billion in 2033, a 10.11 per cent compound growth rate over eight years. On a project-level definition — cameras, recording, network, software, integration and installation — that is 2.16 times in eight years.
The volume anchor is 39.7 million cameras sold in FY2025, moving to 74.6 million by FY2030. Against USD 5.6 billion of system value, India spends USD 141 of system value per camera sold, of which the camera is Rs 2,675 — about USD 32, or 22.6 per cent of the bill. The market is therefore an integration and software market, not a hardware market, and the layer that captures margin is the one that owns retention, search and the maintenance contract.
Four facts define the forecast.
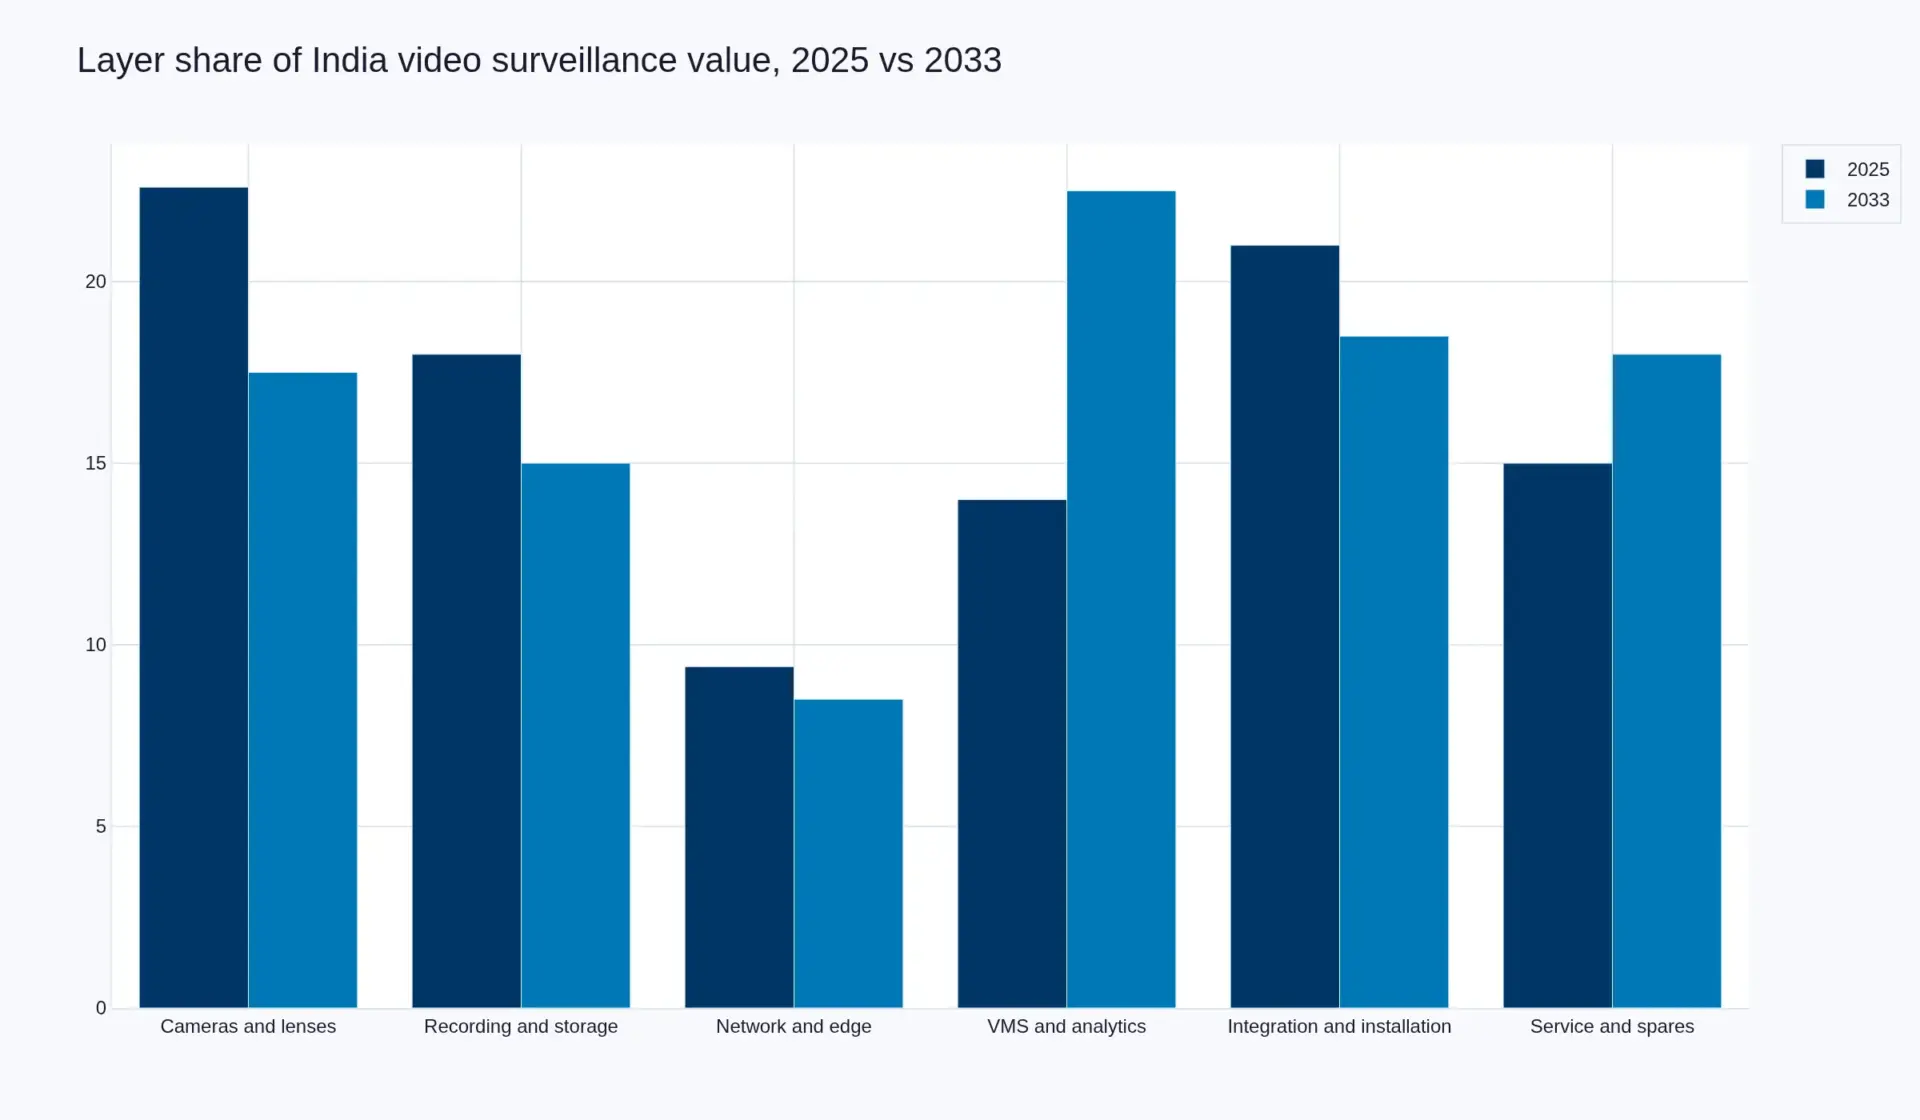
First, the camera is a fifth of the bill and shrinking. Cameras and lenses fall from 22.6 per cent of value to 17.5 per cent while VMS and analytics rise from 14.0 to 22.5 and service from 15.0 to 18.0. Of the USD 6.5 billion the market adds, software and service account for USD 3.28 billion — slightly more than half of all growth.
Second, the largest public buyer has closed its programme. The Smart Cities Mission installed more than 83,000 cameras across 100 cities, equal to 0.209 per cent of the units India buys in a single year — one camera for every 478 sold. It reached financial closure on 31 March 2025 with no successor budget line. Government and public safety fall from 22 per cent of demand to 15 per cent; commercial, residential and industrial buyers absorb the difference.
Third, compulsory registration has already filtered the supply base. The Essential Requirements for security of CCTV were notified in April 2024 and compulsory registration took effect on 9 April 2025: a model that is not registered cannot be sold, test reports hold for three years, and non-compliant models are deleted from licence scope. The largest domestic manufacturer grew revenue 35.6 per cent to Rs 4,221 crore in FY2025-26 against a market growing 10.11 per cent. That gap is share moving, not demand.
Fourth, the binding constraint is retention. A camera at 2 Mbps writes about 21.6 GB a day — 648 GB over 30 days, 1.94 TB over 90. The Digital Personal Data Protection Rules were notified on 13 November 2025 and core obligations commence on 13 May 2027; section 105 of the Bharatiya Nagarik Suraksha Sanhita has required audio-video recording of searches and seizures since 1 July 2024.
The risk to the forecast is not demand. It is receivables, the cost of keeping a catalogue registered on a three-year cycle, and component concentration upstream in image sensors and system-on-chips.
??Marché de la vidéosurveillance en Inde Aperçu
Je suis désolé, mais vous n'avez pas inclus le texte source à traduire. Veuillez fournir le contenu complet que vous souhaitez traduire en français. Le marché indien de la vidéosurveillance prend vraiment son essor. Les gouvernements déploient des projets de sécurité publique et de villes intelligentes, les villes installent davantage de caméras de vidéosurveillance, les détaillants et les centres commerciaux renforcent la sécurité, et les hubs de transport comme les métros et les aéroports sont modernisés—il y a donc une énorme demande pour les caméras IP, l’analyse vidéo par IA, les logiciels de gestion vidéo, et les plateformes vidéo cloud ou en périphérie.
Selon Moteur de prévision de la demande Phoenix, le Taille du marché de la vidéosurveillance en Indeest estimé à 5,6 milliards USD en 2025 et devrait atteindre environ 12,1 milliards USD d'ici 2033, enregistrant une croissance de TCAC d’environ 10,1 % (2026–2033).
Dans le Le marché de la vidéosurveillance en IndeLes grands projets publics comme le déploiement de villes intelligentes et la modernisation des autoroutes, ainsi que les mises à niveau de sécurité dans les commerces et les banques, et les entreprises qui modernisent leurs systèmes vidéo, sont les principaux moteurs de la demande actuelle. Plus tard, l'analyse par IA, le traitement en périphérie et les plateformes cloud de gestion vidéo permettront aux fournisseurs de facturer des tarifs plus élevés et de générer davantage de revenus grâce aux services.
-
Marché le plus important : Le Maharashtra est soutenu par les pôles commerciaux de Mumbai, les centres informatiques et les grands projets de villes intelligentes.
-
Le marché à la croissance la plus rapide : Le Karnataka est porté par l'écosystème informatique/tech de Bangalore, l'adoption de l'analyse par IA et les améliorations de la sécurité urbaine.
Voici les principaux moteurs de Le marché indien de la vidéosurveillance Croissance
-
Programmes de vidéosurveillance pour les villes intelligentes et les gouvernements Les déploiements de villes intelligentes à l'échelle nationale et étatique, les corridors de surveillance à l'échelle de la ville, les systèmes de gestion du trafic et la surveillance de la sécurité publique sont les principaux facteurs qui stimulent les dépenses en capital.
-
Adoption de l’IA et de l’analyse en périphérie Les analyses intégrées à la caméra—comme la détection d'objets, la correspondance de visages et la lecture de plaques d'immatriculation—réduisent les données qui doivent être transmises sur le réseau et permettent au système de réagir plus rapidement, ce qui incite les utilisateurs à mettre à niveau leurs caméras IP.
-
Modernisation des transports et des infrastructures Les réseaux de métro, les aéroports, les ports, les autoroutes et les péages nécessitent des systèmes vidéo et de commandement et de contrôle qui fonctionnent ensemble.
-
Exigences de sécurité pour le secteur de la distribution et la banque La prévention des pertes, l'expansion du commerce de détail organisé et les réglementations imposant des espaces bancaires sécurisés poussent les magasins à installer davantage de caméras et à investir davantage dans l'analytique, ce qui alimente la croissance.
-
Services cloud et gérés (VSaaS) Les PME, les détaillants multi-sites et les collectivités municipales choisissent des modèles par abonnement (VSaaS) pour éviter des coûts initiaux élevés, ce qui stimule la croissance du marché.
-
Pression réglementaire et de conformité Les règles de résidence des données, les directives de surveillance urbaine et la nécessité de maintenir une chaîne de preuves solide signifient que les organisations ont besoin de systèmes robustes de gestion et de stockage vidéo.
-
Améliorations de la 5G et de la connectivité Une couverture élargie permet des solutions vidéo sans fil, mobiles et par drone fiables pour la surveillance à distance et en mouvement.
Segmentation du marché de la vidéosurveillance en Inde
3.1 Par type de système
3.1.1 Systèmes CCTV analogiques
-
3.1.1.1 Caméras analogiques SD
-
3.1.1.2 Enregistrement basé sur DVR
3.1.2 Systèmes vidéo IP/réseau
-
3.1.2.1 Caméras IP fixes (intérieur / extérieur)
-
3.1.2.2 Caméras PTZ
-
3.1.2.3 Caméras multi-capteurs / panoramiques
-
3.1.2.4 Caméras thermiques et faible luminosité
3.1.3 Systèmes hybrides
-
3.1.3.1 Hybrides analogiques + IP
-
3.1.3.2 Hybrides Edge + Cloud
3.1.4 VSaaS géré / Vidéo cloud
-
3.1.4.1 VSaaS dans le cloud public
-
3.1.4.2 Nuage privé / VMS hébergé
-
3.1.4.3 Services hybrides de périphérie à cloud
3.2 Par composant
3.2.1 Caméras (par facteur de forme et technologie)
-
Dôme, Bullet, Box, PTZ, Dôme
-
Niveaux de résolution : 2MP / 4MP / 8MP / 4K / >4K
-
Caméras IA intelligentes/à la périphérie (analytique embarquée)
-
Caméras thermiques et infrarouges
3.2.2 Enregistrement et stockage
-
NVR / NVR hybride
-
Stockage Edge (carte SD / intégré)
-
Stockage SAN / NAS sur site
-
Niveaux de stockage cloud et de conservation
3.2.3 Logiciel de gestion vidéo (VMS)
-
VMS d'entreprise (sur site)
-
VMS cloud et VMS SaaS
-
Clients mobiles VMS
-
VMS ouvert/standard vs VMS propriétaire
3.2.4 Modules d'analyse vidéo / IA
-
Reconnaissance faciale et listes de surveillance
-
Reconnaissance automatique des plaques d’immatriculation (ANPR / LPR)
-
Comptage de personnes et analytique des files d’attente
-
Détection des comportements & événements anormaux
-
Cartes de chaleur et analytique de temps de présence
3.2.5 Mise en réseau et calcul en périphérie
-
Commuteurs PoE et appareils NVR
-
Accélérateurs GPU / NPU de périphérie
-
Passerelles 4G/5G et liaisons hertziennes de backhaul
3.2.6 Services
-
Conception du système et intégration
-
Installation et câblage
-
Surveillance gérée et VSaaS
-
Maintenance, mises à niveau et optimisation des analyses
3.3 Par solution / fonctionnalité
3.3.1 Sécurité publique et surveillance urbaine
-
Contrôle du trafic, bornes de lecture automatique de plaques d’immatriculation (ANPR)
-
Analyse des lieux très fréquentés, sécurité périmétrique
3.3.2 Surveillance des entreprises et à des fins commerciales
-
Surveillance des campus de bureaux
-
Gestion des visiteurs & intégrations de contrôle d'accès
3.3.3 Commerce de détail et restauration rapide (QSR)
-
Intégration du PDV, analytique des pertes, perspectives sur les acheteurs
3.3.4 Banques et institutions financières
-
Voûte, surveillance des guichets automatiques, suivi des comptoirs de guichetiers
3.3.5 Transport et logistique
-
Surveillance des stations de métro, des gares ferroviaires, des aéroports, des ports et des cours d’entrepôts
3.3.6 Infrastructures critiques
-
Centrales électriques, pétrole et gaz, raffineries, périmètre industriel
3.3.7 Résidentiel & Maisons intelligentes
-
Système de vidéosurveillance pour complexe résidentiel, surveillance de communauté fermée
3.4 Par mode de déploiement
3.4.1 Sur site (modèle CAPEX)
-
Entreprises et installations critiques avec stockage local
3.4.2 Cloud / VSaaS (modèle OPEX)
-
PME, chaînes de distribution, écoles préférant l’abonnement
3.4.3 Hybride (Edge + Cloud)
-
Analyse en périphérie avec archivage dans le cloud et gestion centralisée
3.5 Par secteur d'utilisateur final
3.5.1 Gouvernement et Sécurité publique
-
Sociétés municipales (Projets de ville intelligente)
-
Police et forces de l'ordre (étatiques et centrales)
-
Autorités de transport municipal
3.5.2 Entreprises commerciales
-
Sièges sociaux d’entreprises et parcs technologiques
-
Fabrication & Entrepôts
3.5.3 Commerce de détail et hôtellerie-restauration
-
Centres commerciaux / Supermarchés / Chaînes de restauration rapide
-
Hôtels et complexes hôteliers
3.5.4 Services bancaires et financiers
-
Branches, distributeurs automatiques de billets, centres de données
3.5.5 Transport
-
Aéroports (terminaux, côté piste)
-
Réseaux de métro et de rail
-
Ports et dépôts logistiques
3.5.6 Résidentiel
-
Copropriétés fermées, ensembles résidentiels d'appartements
3.6 Par géographie (Inde)
3.6.1 Inde du Nord
-
Delhi NCR, Pendjab, Haryana, Uttarakhand
3.6.2 Inde occidentale
-
Mumbai et Maharashtra, Gujarat, Goa
3.6.3 Inde du Sud
-
Bengaluru (Karnataka), Chennai (TN), Hyderabad (Télangana), Kerala
3.6.4 Est et Nord-Est
-
Kolkata (Bengale-Occidental), Odisha, Assam, Bihar
3.6.5 Inde centrale
-
MP, Chhattisgarh
Voici la traduction en français : **Inde — Perspectives par région**
-
Delhi NCR et Mumbai ??? plus importantes dépenses en matière de sécurité publique et d'entreprises ; forte adoption de caméras portatives et d'infrastructures de vidéosurveillance municipales.
-
Bengaluru et Hyderabad Déploiements solides sur les campus d'entreprise et informatiques, pilotes technologiques pour l'intégration de l'IA de périphérie et des systèmes de gestion vidéo.
-
Chennai et Pune Les pôles manufacturiers, portuaires et logistiques exigent une surveillance périmétrique et de site.
-
Villes de niveau 2 / niveau 3 Adoption rapide du VSaaS alors que les municipalités se modernisent et que les chaînes de vente au détail se développent.
-
Frontières & Corridors de Transport ??? La vidéosurveillance ANPR et thermique est priorisée le long des autoroutes nationales, aux péages et sur les réseaux ferroviaires.
Pourquoi le marché indien de la vidéosurveillance demeure crucial
-
Sécurité publique : Dissuader la criminalité, faciliter les enquêtes et améliorer les interventions d'urgence.
-
Gestion urbaine et de la circulation : Soutient l'application du code de la route et la surveillance des incidents.
-
Continuité des activités : Permet la prévention des pertes et la supervision opérationnelle dans les secteurs de la vente au détail, de la banque et de la logistique.
-
Conformité réglementaire : Fournit des vidéos de qualité médico-légale pour les besoins juridiques et réglementaires.
-
Activation des villes intelligentes : Agit comme une couche de capteurs pour le contrôle des foules, la gestion des déchets et les événements.
Les entreprises leaders dans le secteur Le marché indien de la vidéosurveillance
-
Hikvision (caméra + fabricant d’équipement d’origine d’analytique)
-
Hanwha Techwin (Lignée Samsung Wisenet)
-
Bosch Security Systems
-
Axis Communications
-
CP-Plus (réseau local de fabricants et d’installateurs)
-
Honeywell (intégrateur de systèmes)
-
ABB / Schneider Infrastructure intégrée et sites critiques
-
Avigilon (Motorola / Motorola Solutions)
-
Panasonic
-
Tata Communications / Sify / CtrlS (fournisseurs de VSaaS dans le cloud et gérés)
-
Intégrateurs locaux et sociétés de services en ingénierie informatique (Exemple : SSPL, CMS Info Systems pour les solutions de vente au détail)
Hikvision est la plus grande entreprise sur le marché mondial des solutions de vidéosurveillance et de sécurité.
Intelligence stratégique & Perspectives Phoenix AI
Moteur de prévision de la demande Phoenix
S'Appuie sur les données d'urbanisation, les calendriers des villes intelligentes, l'expansion du commerce de détail et des entreprises, ainsi que les métriques de pénétration des caméras pour générer des prévisions précises de demande et d'approvisionnement au niveau des États.
Infrastructure et cartographie des projets
Suit les appels d'offres et les déploiements dans les villes intelligentes, les métros, les aéroports, les autoroutes (LAPI), et les grandes chaînes de distribution afin d'identifier les cycles d'achat pluriannuels.
Économie de l’edge vs cloud
Évalue le coût total de possession (TCO) pour les configurations sur site, cloud et hybrides — en tenant compte de la bande passante, de la rétention, des besoins en calcul et de la conformité — afin de recommander le modèle le plus rentable.
Sentiment & Tendances d'Approvisionnement
Préférence croissante pour les systèmes de gestion vidéo (VMS) à plateforme ouverte, les solutions analytiques certifiées (accords de niveau de service sur la précision), les modèles VSaaS, et un support de service local renforcé. La sensibilité à la conformité augmente chez les acheteurs gouvernementaux et d'entreprise.
Analyse automatisée des cinq forces de Porter
-
Pouvoir de négociation des acheteurs
-
Pouvoir de négociation des fournisseurs
-
La menace des nouveaux entrantsMenace des produits de substitution
-
Rivalité
Aperçu des prévisions du marché indien de la vidéosurveillance (2025???2033)
| Mesures | Valeur |
|---|---|
| Taille du marché 2025 | 5,6 milliards USD |
| Taille du marché 2033 | 12,1 milliards USD |
| TCAC (2025???2033) | ~10.1% |
| Plus grand segment (2025) | Caméras vidéo IP/réseau et caméras IA en périphérie |
| Segment à la croissance la plus rapide | VSaaS / Vidéo cloud et analytique IA |
| Tendance clé | L’adoption de l’IA périphérique, la lecture automatique de plaques d’immatriculation (ANPR), les systèmes de gestion vidéo (VMS) dans le cloud, les services gérés. |
| Perspectives d'avenir | Interopérabilité, confidentialité des données, précision analytique et recherche forensique |
Dernières conclusions Le marché indien de la vidéosurveillance
Je suis désolé, mais vous n'avez pas inclus le texte source à traduire. Veuillez fournir le contenu complet que vous souhaitez traduire en français. Marché de la vidéosurveillance en Inde (2025-2033) sera marquée par une forte croissance portée par les programmes gouvernementaux de vidéosurveillance, la modernisation des transports, les mises à niveau du commerce de détail et des entreprises, ainsi qu’une nette évolution vers des revenus axés sur les logiciels (analytique et VSaaS). Les gagnants seront les fournisseurs et les intégrateurs qui combinent Analytique IA précise, plateformes VMS ouvertes, capacité de service local et économie flexible cloud/edge.Les investissements dans des modèles de déploiement respectueux de la confidentialité, l'interopérabilité (ONVIF / API ouvertes) et les offres de services gérés permettront de débloquer des revenus récurrents et d'élargir la portée vers les villes de taille 2/3 et les secteurs verticaux d'entreprise.
???? Mentions sociales et canaux de publication
Explorez des analyses plus approfondies et suivez nos mises à jour multiplateformes sur LinkedIn, Moyen et Je suis désolé, mais je n'ai pas reçu le contenu source à traduire. Veuillez fournir le texte à traduire en français. pour une intelligence continue et une couverture de marché.
LinkedIn : : https://www.linkedin.com/feed/update/urn:li:activity:7401274306758049792
Moyen :
Je suis désolé, mais je n'ai pas reçu le contenu source à traduire. Veuillez fournir le texte à traduire en français. :https://x.com/Pheonix_Insight/status/1995511012515319908?s=20
Table des matières
Marché de la vidéosurveillance en Inde — Aperçu
Le marché de la vidéosurveillance en Inde se développe rapidement, les projets de villes intelligentes, les modernisations de la sécurité publique, les métros/aéroports, les chaînes de distribution et les banques augmentant leurs investissements en sécurité. La demande évolue de la CCTV de base vers les caméras IP, l'analytique IA embarquée, les plateformes VMS et les modèles cloud/VSaaS.
Le marché est évalué à USD 5,6 milliards en 2025, avec une projection à USD 12,1 milliards d'ici 2033, soit un TCAC d'environ 10,1 %.
Principal marché : Maharashtra.
Croissance la plus rapide : Karnataka.
Principaux moteurs de croissance ??
-
Villes intelligentes et CCTV gouvernementale (trafic, sécurité publique, centres de commandement).
-
Analyse IA/edge (reconnaissance faciale, ANPR, détection de comportement).
-
Projets de transport (métros, aéroports, autoroutes).
-
Modernisation de la sécurité dans la vente au détail et la banque (prévention des pertes).
-
Croissance de la vidéo cloud / VSaaS auprès des PME et des municipalités.
-
Pression de conformité (conservation des données, vidéo de qualité forensique).
-
5G et connectivité permettant la surveillance sans fil/mobile.
Segmentation du marché ??
Par type de système
-
CCTV analogique
-
Systèmes IP/réseau (fixes, PTZ, panoramiques, thermiques)
-
Hybride (analogique + IP, edge + cloud)
-
Cloud / VSaaS (public, privé, hybride)
Par composant
-
Caméras : dôme, bullet, PTZ, thermique, caméras IA edge
-
Stockage : NVR, NVR hybride, stockage edge, conservation cloud
-
VMS : sur site, cloud, mobile, ouvert vs propriétaire
-
Analytique : reconnaissance faciale, ANPR, détection de comportement, cartes de chaleur
-
Réseau/Calcul edge : commutateurs PoE, passerelles 4G/5G
-
Services : Intégration, installation, supervision, VSaaS
Par solution
-
Sécurité publique, entreprises, commerce de détail/QSR, BFSI, transport/logistique, infrastructures critiques, résidentiel.
Par déploiement
-
Sur site
-
Cloud / VSaaS
-
Hybride (edge + cloud)
Par utilisateur final
-
Gouvernement et forces de l’ordre
-
Entreprises et parcs informatiques
-
Commerce de détail et hôtellerie
-
Banque et finance
-
Transport (aéroports/métros)
-
Complexes résidentiels
Par région (Inde)
Nord, Ouest, Sud (croissance la plus rapide), Est/Nord-Est, Centre.
Aperçus régionaux
-
Delhi NCR et Mumbai : Dépenses les plus élevées ; CCTV municipale et d'entreprise.
-
Bengaluru et Hyderabad : Déploiements d'Edge AI et de campus intelligents.
-
Chennai et Pune : Surveillance de la fabrication et de la logistique.
-
Villes de 2e/3e rang : Adoption rapide du VSaaS.
-
Autoroutes et frontières : Surveillance ANPR et thermique.
Entreprises leaders
Hikvision, Dahua, Hanwha, Bosch, Axis, CP-Plus, Honeywell, Motorola/Avigilon, Panasonic, Tata Communications, Sify, CtrlS.
La plus grande : Hikvision.
Aperçu des prévisions du marché
-
2025 : 5,6 Mrd USD
-
2033 : 12,1 Mrd USD
-
TCAC : ~10,1 %
-
Segment principal : Caméras IP/Réseau et Edge-AI
-
Croissance la plus rapide : Cloud VMS / VSaaS et analyses IA
-
Tendances clés : ANPR, IA en périphérie, VMS ouvert, migration vers le cloud
Conclusion finale ??
Le marché de la vidéosurveillance en Inde accélérera jusqu'en 2033, porté par les projets gouvernementaux de sécurité, la modernisation des transports, les investissements des entreprises et du commerce de détail, ainsi que par l'adoption rapide de l'analyse IA et des services vidéo cloud. Les fournisseurs proposant une IA précise, un VMS ouvert, un service local et des modèles cloud/hybrides flexibles domineront.
Paysage concurrentiel
7. Competitive Landscape
This market has three competitive layers, and they are not the same contest. Treating them as one field is why most commentary on Indian surveillance describes a price war that is only happening in one of them.
The equipment layer manufactures cameras, recorders and the accessories around them. It contains global brands with long histories in imaging — Hikvision, Dahua Technology, Axis Communications, Bosch Security Systems, Hanwha Vision, Honeywell and, for command-centre and evidence-management buyers, Motorola Solutions — alongside a domestic tier led by Aditya Infotech’s CP PLUS brand, with Sparsh, Prama, Secureye and consumer-electronics entrants competing beneath it. Price, channel reach and, since 2025, the ability to keep a model catalogue registered are the terms of competition.
The software layer sells what the video means: video management platforms, analytics, number-plate recognition, search and evidence export. Here Indian firms compete on merit rather than on price, and Videonetics is the clearest example — a domestic platform sold into government and enterprise projects against international software. This layer earns the highest gross margin in the market and is growing at roughly twice the rate of the market itself.
The integrator layer is where most of the money is actually transacted and the least visible from outside. A systems integrator wins the project, specifies the brand inside it, installs it, commissions it and then holds the maintenance contract — and in the Indian market, the maintenance contract is the relationship. Buyers rarely select a camera brand directly. They select an integrator, and the integrator’s stocking position decides what gets installed.
| Layer | Representative participants | Basis of competition | Margin direction |
|---|---|---|---|
| Equipment — global brands | Hikvision, Dahua, Axis, Bosch, Hanwha Vision, Honeywell, Motorola Solutions | Specification, image quality, cybersecurity documentation, project finance | Falling on hardware; recovering where registered models are scarce |
| Equipment — domestic tier | Aditya Infotech (CP PLUS), Sparsh, Prama, Secureye, consumer-brand entrants | Channel breadth, service response, localisation, registration coverage | Rising where scale absorbs compliance cost |
| Software and analytics | Videonetics and international VMS vendors; analytics specialists | Capability, integration, per-camera licence economics | Highest in the market, and stable |
| Integration and service | Regional systems houses, electrical contractors, facility-management firms | Local response time, warranty backing, price | Stable on installation; rising on service annuity |
The scale of the domestic leader is the least understood fact in the market. Aditya Infotech reported revenue of Rs 4,221 crore in FY2025-26, up 35.6 per cent from Rs 3,112 crore, having done Rs 2,782 crore the year before. At Rs 84 to the dollar that is roughly USD 0.50 billion of revenue, which is about 9.0 per cent of the entire project-level value this report measures for 2025 — a single supplier accounting for nearly a tenth of what a whole market spends in a year, before counting the installation and civil works around its products. Its FY2025-26 EBITDA was Rs 579 crore at a 13.7 per cent margin, and profit after tax Rs 368 crore; return on equity rose from 19.18 to 25.42 per cent and return on capital from 20.11 to 30.58 per cent across the year.
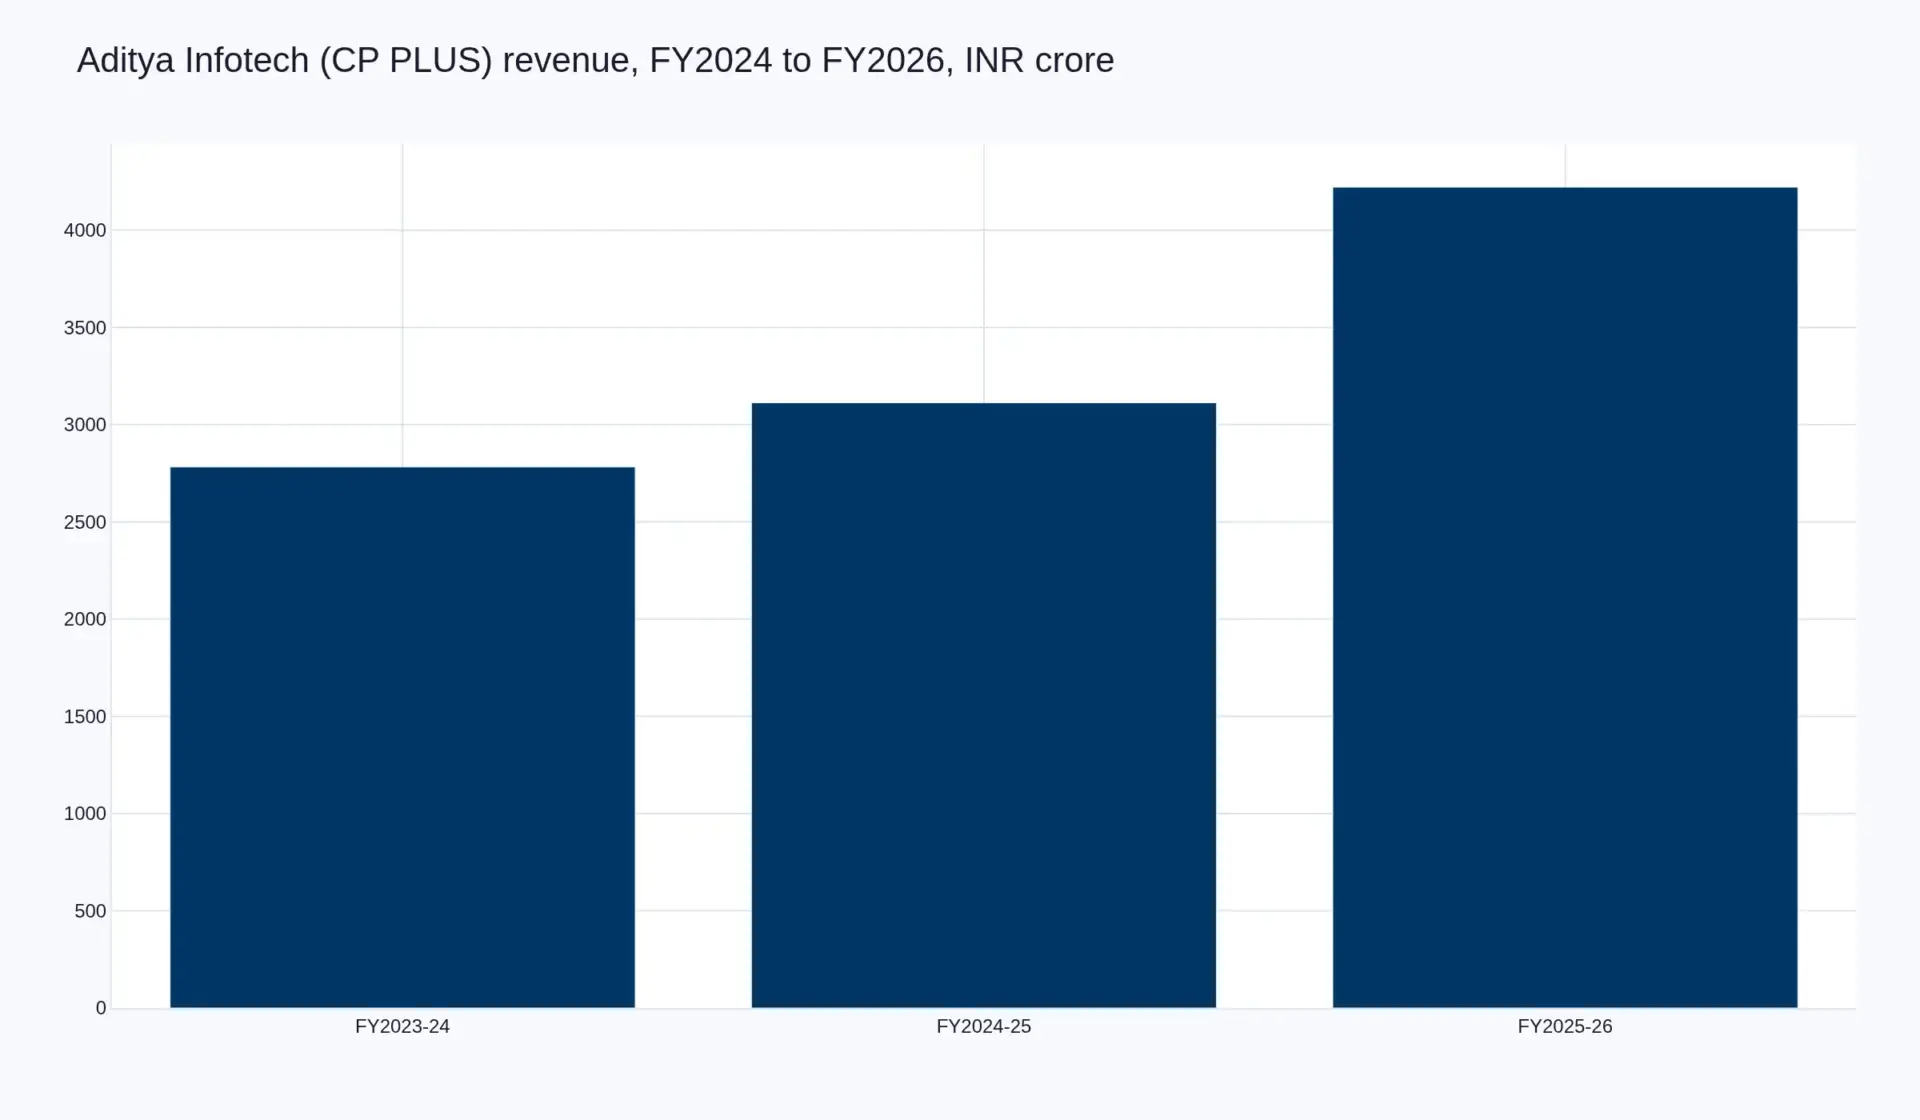
Set that growth against the model. The market grew 10.11 per cent; the largest domestic manufacturer grew 35.6 per cent. A 25-point gap in a market with no consolidation event does not come from demand. It comes from share, and the mechanism is visible in the same disclosure: 150-odd stock-keeping units across price segments, more than 100 of them registered to the Essential Requirements, a 4.10 lakh square foot manufacturing facility at Kadapa in Andhra Pradesh, and 104 branch offices and return-material-authorisation centres — a number that matters more than the factory, because service response is what a buyer in a tier-two city actually experiences.
What registration did to the field. The compulsory registration order that took effect on 9 April 2025 required every camera model to be tested and registered against MeitY’s Essential Requirements, with a disclosed hardware and software bill of materials and third-party test reports. Reporting in the trade press in June 2025 put more than 80 per cent of the industry in the business of importing large modules and assembling locally, and described those businesses reworking product to qualify. By that point a handful of Indian manufacturers had certified portfolios; most global brands had not completed the exercise. Honeywell responded by launching a camera line designed and produced in India. The certification regime does not restrict where components come from, but the tests and the trusted-supply-chain evidence it requires have the practical effect of pushing Chinese modules out of Indian-market products.
That is a competitive filter, not a demand event, and its consequences are asymmetric. A vendor with a narrow catalogue pays the same per-model testing cost as a vendor with a broad one and gets less range out of it; a vendor with a broad catalogue can hold shelf space in a channel that suddenly cannot substitute. Small importers and white-label assemblers face a cost and documentation burden they cannot amortise. Scale becomes a licence to compete rather than an advantage in bidding.
The premium tier is not competing on price at all. Axis, Bosch and Hanwha sell specification and integration depth — cameras that behave well in a large VMS, industrial housings, thermal variants, and long product-life commitments that matter to a port or a refinery. Motorola Solutions sells the command-centre and evidence chain around video rather than the camera, which is the software-layer argument in another form. None of them is winning the Indian residential estate; all of them are hard to displace once specified into an industrial or transport site.
What the field looks like in five years. On this model, the number of competing camera brands falls and the number of competing software platforms rises. The equipment layer’s share of value drops from 22.6 per cent to 17.5 per cent, so brand strength in cameras buys a smaller prize each year; the software layer’s share rises from 14.0 to 22.5, which attracts entrants with no hardware business at all. The integrator remains the gatekeeper in both directions, and remains the layer most exposed to receivables. Anyone forecasting share should forecast it in the software layer, because that is where the value being contested is growing.
Chaîne de valeur
8. Value Chain
The fastest way to understand the economics of Indian video surveillance is to follow one rupee through a project and notice where it stops. It stops in three places: the camera manufacturer’s gross margin, the integrator’s contract, and the software licence nobody itemised.
Upstream, the camera is assembled from parts this market does not price. A network camera is an image sensor, a lens, an infrared illuminator, a system-on-chip that does the encoding and increasingly the analytics, memory, a power supply and a housing. Every one of those components is priced by volumes orders of magnitude larger than surveillance: sensors by mobile imaging and automotive, lenses by the same, system-on-chips by consumer cameras and set-top boxes. No Indian camera manufacturer fabricates its own sensor, and no surveillance vendor anywhere sets the price of one. The consequence is that the cost of the instrument falls on a schedule decided outside the market — and the only way a hardware vendor defends margin is by adding something the component does not carry: firmware, warranty, service network, or a registered model catalogue.
Through the channel, margin is thin and inventory is expensive. Indian surveillance distribution runs on credit. A distributor carries stock across hundreds of stock-keeping units so that an integrator can quote on Monday and install on Thursday, and that stock is financed by the distributor’s balance sheet. Distribution gross margins in this market sit in the mid single digits for volume lines and higher only for brands with genuine pull. The manufacturer’s counter-move is vertical reach: Aditya Infotech operates 104 branch offices and return-material-authorisation centres, which is a distribution strategy dressed as a service strategy. It costs a great deal to build and it is the single hardest thing in this market to copy.
At the project, the integrator carries the risk and the software takes the margin. The integrator prices installation, commissioning, cabling, civil works and configuration, then signs a maintenance contract. On hardware the integrator’s gross margin is modest and the working capital burden is not: security deposits, performance guarantees and, on government work, receivables that arrive long after the invoice. On service the margin is better and the capital requirement is close to nil, which is why every integrator in India is trying to convert installation revenue into annual maintenance revenue, and why the service layer grows to 18.0 per cent of market value by 2033.
| Layer | Indicative gross margin | Working capital | Who bears project risk |
|---|---|---|---|
| Cameras and lenses | 18–28% | Inventory at distributor; 30–60 day credit | Manufacturer and distributor |
| Recording and storage | 12–20% | Higher: disk lead times and model churn | Distributor |
| Network and edge compute | 10–18% | Low | Distributor |
| VMS and analytics software | 60–85% | Almost none; licensed or subscribed | Vendor carries little |
| Integration and installation | 12–18% hardware; 35–45% service | Highest: deposits, retention, receivables | Integrator |
| Service and spares | 25–35% | Low; contracts usually prepaid annually | Integrator or manufacturer service arm |
The cash cycle is the real constraint. Capital in this market is not principally tied up in factories. It is tied up in stock and in receivables. Integrators we spoke with during 2025 and 2026 describe financing public-sector and large-enterprise work from their own balance sheet for the length of the payment cycle, then recovering it through the service contract. That has two observable consequences. It favours integrators with existing balance sheets over technically better newcomers, and it pushes project pricing up in exactly the segments where the buyer is most price-sensitive. It also explains why the replacement market is healthier than the new-build market for the channel: a replacement is bought by an owner who is already paying for the site, not by a department waiting on a sanction.
Compliance has become a line in the cost structure. Registration is charged per application and per test report, and a test report holds for three years. For a vendor holding a hundred and fifty models, that is not a one-off legal expense; it is a permanent, repeating cost of staying in the market, and it lands hardest on the vendor whose catalogue is broad and whose volumes are thin. In the value chain it behaves like a fixed cost that has been inserted between the factory and the shelf, which is precisely the kind of cost that consolidates a channel.
Procurement mechanics shape the chain more than any technology does. Public buying runs on published tenders and on the Government e-Marketplace, with price discovery that rewards the lowest compliant bid. When the specification was a paragraph of camera features, L1 rewarded the cheapest box. Now that the specification includes a registration certificate and a disclosed bill of materials, the pool of compliant bidders is smaller and the price floor is set by the cheapest registered model rather than the cheapest model. That is a quiet but material change in how the integrator prices a bid, and it is the clearest channel through which a certification rule becomes a margin.
Where the chain settles. Value accrues to whoever holds the recurring relationship. The camera manufacturer holds it through the channel and the warranty. The integrator holds it through the annual maintenance contract. The software vendor holds it through the per-camera licence that survives every hardware refresh. Of the three, only the software licence scales without working capital and without a service technician — which is why the software layer grows from 14.0 per cent of market value to 22.5 per cent while every hardware layer loses share. The value chain does not reward the company that makes the instrument. It rewards the company that the buyer has to call again.
Activité d'investissement
9. Investment Activity
Investment in Indian video surveillance is not mainly investment in factories. It is investment in the three things that decide whether a participant can stay on the shelf: working capital, registration coverage and service reach. Understanding that changes what an investor should look for and what a strategic buyer is actually buying.
Capex is real but concentrated. The visible plant is limited to a small number of domestic manufacturers. Aditya Infotech operates a 4.10 lakh square foot manufacturing facility at Kadapa in Andhra Pradesh, built as a localisation asset and described in its own reporting as central to its manufacturing strategy. That is a genuine capital commitment in a market where most participants assemble rather than manufacture, and it is the kind of commitment that only makes sense with a large catalogue and a national channel behind it. For everyone else, capex is test equipment, tooling for housings, and the inventory required to hold shelf position — not a factory.
Registration behaves like capex and is expensed like opex. A camera model cannot be sold in India unless it is registered against MeitY’s Essential Requirements, evidenced by a third-party test report. Applications carry a per-application fee including one test report, with a further charge for each additional report, and a test report remains valid for three years. The economics of that are straightforward and unpleasant for a broad catalogue: a vendor with a hundred and fifty models is, in effect, amortising a rolling test programme across every year of trading, and a vendor with fifteen models pays the fixed part of the same bill with a tenth of the revenue behind it. Investors should read registered model count as a capital asset, because that is how it behaves.
| Category | What it funds | Who spends it | Return profile |
|---|---|---|---|
| Manufacturing plant | Assembly, localisation, quality control | Two or three domestic manufacturers | Scale-dependent; defensible only with channel reach |
| Registration and testing | Per-model testing, bill-of-materials documentation, re-testing on a three-year cycle | Every brand selling in India | Fixed cost; acts as a barrier to entry |
| Channel inventory | Stock across hundreds of stock-keeping units | Distributors and branch networks | Working-capital return; sensitive to model churn |
| Receivables | Financing public-sector and enterprise payment cycles | Integrators | Highest risk; recovered through service contracts |
| Service network | Branch offices, return-material-authorisation centres, field engineers | Manufacturers and large integrators | Durable; annuity attached to installed base |
| Software development | VMS platforms, analytics, per-camera licensing | Software vendors and manufacturers | Highest margin; scales without working capital |
The returns in the domestic leader illustrate the mechanism. Aditya Infotech’s FY2025-26 disclosure shows revenue of Rs 4,221 crore, EBITDA of Rs 579 crore at a 13.7 per cent margin, and profit after tax of Rs 368 crore. Return on equity moved from 19.18 to 25.42 per cent and return on capital employed from 20.11 to 30.58 per cent in the same year that registration took effect and revenue grew 35.6 per cent. It would be careless to attribute the whole improvement to the certification regime — growth of that magnitude lifts returns on its own, and the company also reports a revenue compound growth rate of 26.6 per cent between FY2022 and FY2026 led by IP and AI products. But the pattern is consistent with the argument in Section 7: a compliance filter that removes smaller competitors allows the scaled participant to earn a better return on the same assets.
Consolidation has not happened yet, and the conditions for it now exist. There has been no transformative Indian acquisition in this market. The global picture is different, with command-and-control, evidence-management and analytics assets changing hands repeatedly as strategics buy software rather than hardware. In India, two preconditions for consolidation were missing until recently: a reason for small brands to exit, and a reason for a buyer to want them. Registration supplies the first. The second is supplied by the service network — a buyer acquires a branch footprint and an installed base with an annuity, not a brand.
The likelier Indian shapes are therefore three: a domestic manufacturer buying a smaller registered catalogue to widen its price coverage; a software vendor acquiring an analytics team to attach a licence to hardware it does not make; and an integrator roll-up, where a larger services group buys regional systems houses for their maintenance contracts. The third is the most probable and the least discussed, because integrator revenue is unglamorous and the contracts are small. It is also the only route to instant national service coverage without building a branch network of your own.
Venture capital is thin and aimed upstream. There is little venture money in installing cameras in India, because the business is working-capital heavy and the returns are contractual. Where early-stage capital is going is into components — Indian chip-design efforts aimed at the system-on-chip inside a camera, and into video analytics built on top of existing hardware. The policy environment is nudging in the same direction: press reporting in June 2025 described MeitY convening matchmaking between camera manufacturers and Indian chipset enterprises. That is a supply-side bet with a long horizon, and it is the one place in this market where an Indian company could eventually control a cost that today it only inherits.
What an investor should underwrite. Three numbers, in order. The share of revenue that recurs annually, because service and subscription revenue is what survives a hardware price war. Registered model coverage relative to the catalogue, because an unregistered model is dead stock. And receivable days, because the fastest way to lose money in Indian surveillance is to win a large public contract and finance it yourself. A company strong on the first and third and adequate on the second will outperform a company with better cameras.
Technologie et innovation
10. Technology and Innovation
The most important thing about a modern surveillance camera is that it is a computer with a lens bolted on, and the computer is priced by markets that have nothing to do with security. That single fact explains most of the innovation pattern in this market and almost all of its margin behaviour.
The bill of materials is priced elsewhere. An image sensor comes from a handful of global foundries and is bought by mobile, automotive and consumer-imaging customers in volumes a surveillance vendor cannot approach. The system-on-chip that encodes video and, increasingly, runs analytics is bought on the same basis. The lens, the infrared illuminator, the memory and the power supply follow the same logic. The consequence is that the cost of the instrument falls on an exogenous schedule: year after year, the same money buys more pixels, better low-light performance and more compute. A vendor that competes on hardware specification is competing on a curve it cannot influence.
Analytics has moved into the camera. Five years ago, video analytics ran on a server in a control room and cost a per-channel licence that made buyers hesitate. Now a mid-range network camera performs person and vehicle detection on-device, which means one licence per camera, no server, and no bandwidth cost for metadata. This is the most consequential technical shift in the market because it changes what a camera sale includes. It also explains why the software layer grows faster than the market: the licence did not disappear when analytics moved to the edge, it moved onto the camera’s bill and became recurring.
Retention is now a design constraint with a calculable cost. A 4-megapixel camera recording at 2 Mbps writes about 21.6 GB a day. Thirty days of retention takes 648 GB; ninety days takes 1.94 TB. Multiply by the camera count on a site and the arithmetic becomes the dominant line in the storage budget. Two responses are visible in Indian projects: modern codecs and smart recording that store at a low frame rate until motion occurs, and centralised storage that serves many cameras instead of an appliance behind each. Both push value away from per-site hardware and towards software and capacity planning.
Security engineering has become a product feature with a certificate attached. The Essential Requirements that now govern sale in India test specific things rather than general claims: exposed network services, device communication protocols, physical access to debug interfaces, the difficulty of extracting memory and firmware, the security of the firmware update process, and the storage and encryption of the data the device holds. A camera that fails those tests cannot be registered, and a camera that cannot be registered cannot be sold. In practice this converts cybersecurity from a brochure claim into an engineering gate, and it is the single largest change in product development in this market in a decade.
The analytics that sell in India are the boring ones. Number-plate recognition, vehicle detection, perimeter intrusion, people counting, queue and dwell measurement, and industrial safety detection — helmets, vests, restricted zones — are the applications that convert into orders, because each has a named owner and a measurable outcome. Face-based retail analytics attract interest and legal caution in equal measure, and the arrival of enforceable consent and purpose-limitation duties makes them a contract question rather than a technology question. Buyers in our interviews consistently describe the same buying order: record reliably, find footage quickly, then automate one thing.
Interoperability decides who owns the customer. Open standards let devices from different manufacturers join one management platform, which is good for the buyer and dangerous for the vendor whose differentiation is that its cameras only work well with its own software. The practical result in India is that the video management platform becomes the switching cost, not the camera. Once an estate’s operators know one interface, its rules and its evidence-export workflow, replacement of the cameras beneath it is a maintenance decision; replacement of the platform is a retraining decision. That is precisely why the software layer is where the value share is moving, and why hardware brands increasingly give software away to defend the camera line.
What cloud does and does not change. Subscription recording with bundled hardware is growing from a low base and is held back by three Indian realities: upstream bandwidth at the edge of the network, buyers who prefer to own capital assets, and data questions that become harder once footage leaves the site. The hybrid architecture — recording locally, managing centrally, exporting to the cloud when an incident requires it — is the shape that is actually being deployed, and it favours vendors who can sell a platform rather than a box.
Innovation does not change the layer arithmetic. Every technical improvement in this market — better sensors, on-device analytics, tighter codecs, secure boot — moves value towards software and service and away from the instrument. That is the same conclusion the layer model reaches from the demand side, and the two arriving together is what makes the forecast in this report reasonably safe. Readers wanting the enforcement use of these same capabilities should see our road safety and enforcement systems report, where number-plate recognition is the product rather than a feature on the camera’s specification sheet.
Risque de marché
11. Market Risk
The risks that matter in this market are not demand risks. India will keep buying cameras. They are concentrated in how the money is collected, what it costs to stay legally on sale, and what happens the first time an Indian regulator treats a badly run camera estate as a data protection failure rather than an operational lapse.
Public demand has already contracted, and the forecast assumes no replacement mission. The Smart Cities Mission spent Rs 48,000 crore across 100 cities and closed financially on 31 March 2025. Municipal and public-safety buyers still exist, but the programme that concentrated their purchases does not. Our model has government and public safety falling from 22 per cent of demand to 15 per cent over the window, with the difference taken up by commercial, residential and industrial buyers. If a successor safe-city or surveillance programme is funded at scale, that assumption is conservative and the forecast understates growth. If private replacement demand is slower than we assume, there is no second engine, and the risk sits at the low end of the range.
Receivables are the largest single source of failure in the channel. Government and large-enterprise buyers pay late, and the integrator finances the gap. A single large award can consume an integrator’s working capital for a year, and the failure mode is not a loss on the project — it is an inability to bid on the next one. This is why project pricing in India carries a premium that foreign vendors often misread as margin inefficiency. It is the price of credit. Watch receivable days and the ratio of public to private revenue in any channel participant’s book; a sudden shift towards public work without a matching balance sheet is a warning, not a growth signal.
Registration is a standing risk to revenue, not a one-off hurdle. A model whose test report lapses, or which fails re-testing, is removed from the licence scope, and a licence with no compliant models is liable to cancellation. For a vendor running a broad catalogue on a three-year test cycle, the operational question is not whether it can certify but whether it can keep a hundred and fifty models certified on a rolling basis without a supply interruption in the channel. Small importers and white-label assemblers carry this risk most acutely; so do buyers who standardised on a brand that quietly stops maintaining its Indian registrations.
Component concentration is the risk the industry cannot control. Image sensors and system-on-chips come from a small number of suppliers whose capacity is allocated to mobile and automotive customers first. A surveillance vendor has no leverage in an allocation squeeze, and lead times of a few weeks can become several months without warning. In a market where the replacement cycle is triggered by a recorder failing, a supply gap does not merely delay revenue — it sends the buyer to a competitor who has stock.
| Risk | How it reaches the P&L | Indicator to watch | Credible mitigant |
|---|---|---|---|
| Public demand contraction | Loss of mission-funded pipeline | Government share of order book | Private vertical mix; growing maintenance base |
| Receivables and deposits | Working-capital cost; forfeited bid capacity | Receivable days; deposit exposure | Staged billing; private-sector weighting |
| Registration lapse | Model removed from sale; channel gap | Registered share of catalogue | Rolling test programme; series grouping |
| Component allocation | Delayed revenue; lost replacement sales | Supplier lead times | Dual sourcing; buffer inventory |
| Hardware price deflation | Gross margin per unit falls | Average selling price against bill of materials | Software and service attach |
| Data protection liability | Penalty, remediation, contract loss | Retention schedules; vendor data terms | Design, impact assessment, contractual allocation |
| Cybersecurity failure | Incident cost; tender disqualification | Patching cadence; known vulnerabilities | Compliance-first product engineering |
| Currency and duty | Landed cost volatility | Rupee-dollar movement | Pricing clauses; local value addition |
The data protection clock is the risk most buyers have not costed. The Digital Personal Data Protection Rules were notified on 13 November 2025 and the core obligations of the Act commence on 13 May 2027. From that date, an operator running cameras over public or semi-public space is a data fiduciary with duties of notice, consent, purpose limitation, erasure and breach intimation, and the Act’s schedule provides for substantial penalties where reasonable security safeguards are not in place. Most Indian camera estates today cannot produce a retention policy, cannot show who has access to footage, and keep video indefinitely because deleting it requires a decision. The commercial consequence is a wave of remediation work — retention configuration, access control, logging, and a data protection impact assessment for the larger operators — which is demand for the software and service layers and a liability for the integrator who signed the system off.
Cybersecurity has moved from theoretical to contractual. A camera with an unpatched firmware vulnerability is now a device that can be excluded from a registered catalogue and repudiated by a corporate buyer’s security team. The Essential Requirements make the specific tests explicit, which means the defence is auditable. Vendors that treated security as a certification exercise rather than an engineering practice will find the second re-test cycle considerably harder than the first.
What is not a risk. Camera prices falling is not a risk to this market; it is the mechanism by which coverage expands, and the model already assumes spend per camera declines from USD 141 to about USD 121 by 2030. Neither is consolidation. A market where the smallest participants face a fixed per-model compliance cost and the largest participant earns 25 per cent on equity is a market that consolidates, and consolidation is how the surviving participants improve returns. The risk to an incumbent is being on the wrong side of that process, not the process itself.
Paysage réglementaire
12. Regulatory Landscape
Three instruments govern this market, and they arrive from three different directions: a procurement preference that decides who may bid, a product regulation that decides what may be sold, and a data law that decides what may be kept. Understanding which one applies to a given decision is most of the compliance problem.
The procurement preference. MeitY’s notification No. 1062, dated 7 March 2024, notified CCTV and video surveillance systems under the Public Procurement (Preference to Make in India) Order 2017. Procuring entities are to give preference to locally manufactured video surveillance systems, and surveillance devices — analogue and IP cameras, including speed domes — must comply with MeitY’s Essential Requirements for security, with the test report issued by the Standardisation Testing and Quality Certification directorate or another agency notified by MeitY. The Essential Requirements were to apply three months after issue, a test report holds for three years, and the notification itself was expressed to run for one year, which is why the instrument has been carried forward by subsequent orders rather than left to stand alone.
The product regulation, which is the one that changed the market. MeitY notified the Essential Requirements for security of CCTV in April 2024, and the compulsory registration order implementing them took effect on 9 April 2025, having been extended to that date. From then on, a CCTV camera model may not be sold in India unless it is registered, and registration requires a test report from a recognised third-party laboratory for each lead model, with series models covered where the manufacturer demonstrates similarity on hardware and software bill of materials. BIS guidance sets out the mechanics precisely: existing licensees apply for the standard revision with an ER:01 test report, paying a per-application fee that includes one test report and a further fee for each additional report; after 9 April 2025 non-compliant models are deleted from the scope of the licence, and a licensee with no compliant models faces cancellation.
What the tests actually cover matters commercially, because it defines what a compliant product is. The areas include exposed network services, device communication protocols, physical access to debug and storage interfaces, the difficulty of extracting memory and firmware, the integrity of the firmware update process, and the storage and encryption of data held on the device. Read as a list, it is a definition of a security-critical product rather than a camera. Read as a procurement rule, it converts a claim into a certificate, which is why several buyers who had deferred networked video on security grounds resumed buying.
The data law, which is the one with the longer fuse. The Digital Personal Data Protection Act 2023 is the parent statute; the Rules were notified on 13 November 2025 and published the following day, with a corrigendum issued on 16 December 2025. Commencement is staged. Consent managers begin operating from 13 November 2026. The core operational obligations — consent, notice, purpose limitation, erasure on withdrawal, the duties of significant data fiduciaries and the Board’s enforcement powers — commence on 13 May 2027. For a camera estate, that is the date on which “we keep 90 days because that is what we have always done” stops being an answer, and the date by which retention schedules, access logs, vendor data-processing terms and, for larger operators, a data protection impact assessment should already exist.
| Instrument | Date | Who it binds | What changes |
|---|---|---|---|
| MeitY notification No. 1062 (procurement preference) | 7 March 2024 | All procuring entities | Preference to locally manufactured systems; Essential Requirements compliance required of devices |
| Essential Requirements for security of CCTV notified | April 2024 | Manufacturers and importers | Testing regime, bill-of-materials traceability, three-year test validity |
| Bharatiya Nagarik Suraksha Sanhita, s.105 | 1 July 2024 | Police and investigating agencies | Audio-video recording of searches and seizures; evidence chain-of-custody |
| Compulsory registration order in force | 9 April 2025 | Every seller of CCTV cameras in India | Unregistered models may not be sold; non-compliant models deleted from licence scope |
| Digital Personal Data Protection Rules notified | 13 November 2025 | All data fiduciaries | Consent, notice, retention and breach duties set out; corrigendum 16 December 2025 |
| Consent managers operational | 13 November 2026 | Registered consent managers | Consent withdrawal becomes a managed process |
| Core DPDP obligations commence | 13 May 2027 | Every data fiduciary operating cameras | Enforceable consent, purpose limitation, erasure and breach intimation |
The evidentiary rule is the one buyers notice first. Since 1 July 2024, Section 105 of the Bharatiya Nagarik Suraksha Sanhita has required audio-video recording of searches and seizures. That single provision turned the camera into an instrument of criminal procedure with a custody trail attached, and it is the reason site managers in our interviews asked about time synchronisation and export formats before they asked about resolution. An unsynchronised camera that cannot produce a verifiable export is, for evidentiary purposes, not a camera.
Enforcement is where the three regimes differ. Registration is enforced at the point of sale and through licence maintenance, which makes it immediate: a model is either on the register or it is not, and a buyer or a competitor can check. Procurement preference is enforced through tender conditions and the bid process, which makes it visible in documents. Data protection is enforced after the fact, through the Data Protection Board, and the Act’s schedule provides for substantial penalties where reasonable security safeguards are absent. For operators, that sequencing matters: the supply-side rules bite first, and the data-side rules bite later but harder.
Two practical consequences follow for anyone building a commercial position on this market. Compliance is now a recurring operating cost rather than a launch gate, which favours participants with catalogue depth and national service reach. And the retention decision, which was once a technical setting chosen by an installer, has become a legal decision owned by the buyer — which moves budget towards the software and service layers that the model already shows growing fastest.
Sources and editorial references
- Ministry of Electronics and Information Technology, notification No. 1062, New Delhi, 7 March 2024, notifying CCTV and video surveillance systems under the Public Procurement (Preference to Make in India) Order 2017 — eGazette.
- Bureau of Indian Standards, Registration Department, Guidelines for implementation of Essential Requirement(s) for Security of CCTV, including implementation date, fee structure and deletion of non-compliant models — BIS CRS guidance.
- Ministry of Electronics and Information Technology, Digital Personal Data Protection Rules 2025, with the enforcement timeline and the corrigendum of 16 December 2025 — MeitY.
- Ministry of Housing and Urban Affairs, Smart Cities Mission — mission scope, 100 Integrated Command and Control Centres and more than 83,000 CCTV cameras installed, and financial closure on 31 March 2025 — MoHUA.
- Press Information Bureau, evaluation of measurable outcomes delivered by the Smart Cities Mission, 3 August 2026, reporting 8,064 projects and 7,790 completed as at 31 March 2026 — PIB.
- The Hindu BusinessLine, 23 June 2025, reporting the certification requirement taking effect on 9 April 2025, the share of the industry that imported modules and assembled locally, and the localisation responses from manufacturers — report.
- Aditya Infotech Limited, Annual Report FY2025-26, for revenue, EBITDA, profit, return ratios, manufacturing footprint, stock-keeping units and branch and service network — annual report.
- Bharatiya Nagarik Suraksha Sanhita, 2023, section 105, in force from 1 July 2024.
Provenance. This report is bound to the Digital Cameras segment within the Semiconductors & Electronics industry. Market model, layer decomposition and unit economics are Pheonix Research build-ups; document dates are as published by the issuing authority. No competitor research is cited anywhere in this report.