
Global Ethanol in Pharmaceutical & Healthcare Market Report, Size & Forecast 2026-2033
Global Ethanol in Pharmaceutical & Healthcare Market Forecast Snapshot 2025–2033
| Metric | 2025 | 2033 | Rate 2025–2033 |
|---|---|---|---|
| Market value, USD million | 6,025 | 9,492 | 5.85% CAGR |
| Volume, million litres | 4,700 | 6,364 | 3.86% CAGR |
| Implied realised price, USD per litre | 1.2819 | 1.4915 | 1.91% CAGR |
| Compendial (monograph) grade, USD million | 4,030 | 6,593 | 6.35% CAGR |
| Healthcare specification grade, USD million | 1,995 | 2,900 | 4.79% CAGR |
| North America, USD million | 2,048 | 2,935 | 4.6% CAGR |
| Europe, USD million | 1,717 | 2,386 | 4.2% CAGR |
| Asia Pacific, USD million | 1,627 | 3,160 | 8.65% CAGR |
| Largest application | API and process solvent — USD 2,403 million, 39.9% of 2025 value | ||
| Fastest application | Excipient in finished dose forms — 6.32% CAGR | ||
| Base year and horizon | 2025 to 2033 | ||
What this report sizes, and the rule that follows from it
This page sizes ethanol — the litres a pharmaceutical plant or a hospital actually buys — and not the pharmaceutical or healthcare industry that buys them. The distinction is not pedantry. Size the industry and the answer runs into the hundreds of billions and tells a supplier of ethanol nothing it can act on.
The build has two components. 2,600 million litres of compendial, monograph-grade ethanol at USD 1.55 a litre, or USD 4,030 million, consumed where a pharmacopoeial specification is required: as a process solvent in API manufacture and as an excipient in finished dose forms. Plus 2,100 million litres of healthcare specification grade at USD 0.95 a litre, or USD 1,995 million: the ethanol base of disinfectants and hand hygiene products, and the solvent and cleaning agent used around medical devices and in laboratories. Together, USD 6,025 million in 2025.
The rule that follows. Both components are subsets of the industrial and pharmaceutical line of the ethanol series, cut a second way — by end use rather than by grade. This page is therefore a use view. Its compendial component is 2,600 million litres against the 13,600 million litres and USD 14,480 million sized in the industrial and pharmaceutical ethanol report: 19.1 per cent of that volume and 27.8 per cent of that value. Adding this page to that one, to the beverage-grade line, to the fuel blending line or to the total ethanol market counts the same litres twice. What may be added is stated on each page; here it is nothing.
Two exclusions carry more weight than the rest. Finished medicinal products are outside: a tincture or a prefilled syringe belongs to a pharmaceutical market, and its ethanol content appears here once, at the price the formulator paid for it. Captive production is also outside: a plasma fractionator that recovers and re-distils its own ethanol never buys those litres, and its recycling rate is a process-efficiency story rather than a market. The processing and refining report sizes the step between the two — a cost line inside the parent, and equally not additive.
Two grades, two price mechanisms
Across the eight years to 2033 volume supplies 3.86 points of the 5.85 per cent growth and price supplies 1.91. That is the opposite of the fuel market, where the volume line does almost all the work, and it is what distinguishes a specification market from a commodity one: the buyer is not choosing between suppliers of a molecule, but between suppliers of a document.
Compendial material is priced by documentation and lot size — a validated monograph-compliant release, a change-control history, a dedicated stainless parcel, and a certificate of analysis a qualified person will sign without a query. Specification grade is priced by the bulk market plus the cost of moving a class 3 flammable to a site that needs 20,000 litres rather than 20 million. The result is USD 1.55 against USD 0.95, a ratio of 1.632. The two escalate almost identically, at 1.74 and 1.73 per cent a year, because both are ultimately tied to the same feedstock and the same energy.
Geography prices it a third way. Europe at USD 1.455 a litre and North America at 1.442 sit against Asia Pacific at 1.063 — a 1.369× premium, or 36.9 per cent, for the same molecule. That gap is not freight. It is compendial mix, because Europe and North America consume a far higher share of their litres as monograph-grade, plus excise, which is discussed in the regulatory chapter and which no supplier can arbitrage away.
Where the litres actually go
| Application | 2025 volume, m litres | 2025, USD m | 2033, USD m | CAGR |
|---|---|---|---|---|
| API and process solvent | 1,550 | 2,403 | 3,934 | 6.36% |
| Excipient in finished dose forms | 1,050 | 1,628 | 2,659 | 6.32% |
| Disinfection and hand hygiene | 1,350 | 1,283 | 1,864 | 4.78% |
| Medical device processing and laboratory | 750 | 713 | 1,036 | 4.78% |
The honest observation about this table is that a third of the value sits in a demand pool that was inflated by a pandemic and is now growing at 3.00 per cent in volume, while the two thirds that sit in compendial supply grows at 4.5 per cent in volume because pharmaceutical output grows. Grade A supplies 73.9 per cent of all absolute value growth over the period, and the two disinfection applications supply the rest between them at half the pace.
Within grade A, the API and process solvent line is the larger and the slightly faster of the two at 6.36 against 6.32 per cent — a difference small enough to be noise, and deliberately left in rather than flattened, because the two are driven by different things. Solvent demand tracks the kilogrammes of API made; excipient demand tracks the number of dose units filled, and those two curves have not moved together since sterile injectables began taking share from oral solids.
Regional structure: Asia Pacific stops being the growth story and becomes the market
| Region | 2025, USD m | 2025 volume, m litres | Implied price, USD/litre | 2033, USD m | CAGR | Share 2025 → 2033 |
|---|---|---|---|---|---|---|
| North America | 2,048 | 1,420 | 1.442 | 2,935 | 4.6% | 34.0% → 30.9% |
| Europe | 1,717 | 1,180 | 1.455 | 2,386 | 4.2% | 28.5% → 25.2% |
| Asia Pacific | 1,627 | 1,530 | 1.063 | 3,160 | 8.65% | 27.0% → 33.3% |
| Latin America | 313 | 300 | 1.043 | 510 | 6.3% | 5.2% → 5.4% |
| Middle East and Africa | 193 | 175 | 1.103 | 327 | 6.8% | 3.2% → 3.4% |
| FSU | 127 | 95 | 1.337 | 169 | 3.6% | 2.1% → 1.8% |
Asia Pacific passes North America in value during the period and holds 33.3 per cent of it by 2033, supplying 44.3 per cent of all absolute growth. That is a statement about pharmaceutical manufacturing location, not about ethanol: the region is where new API capacity, new fill-finish capacity and new hospital infrastructure are being built, and it buys solvent at a discount because most of what it buys is specification grade rather than monograph grade. The USD 1.063 implied price against Europe's 1.455 is exactly that discount, and it should not be read as efficiency.
North America remains the single most valuable market in the base year at 34.0 per cent, on a high compendial mix and the most expensive verification labour in the world. Its share erodes for arithmetic reasons rather than weakness.
The year-by-year path: flat growth, moving composition
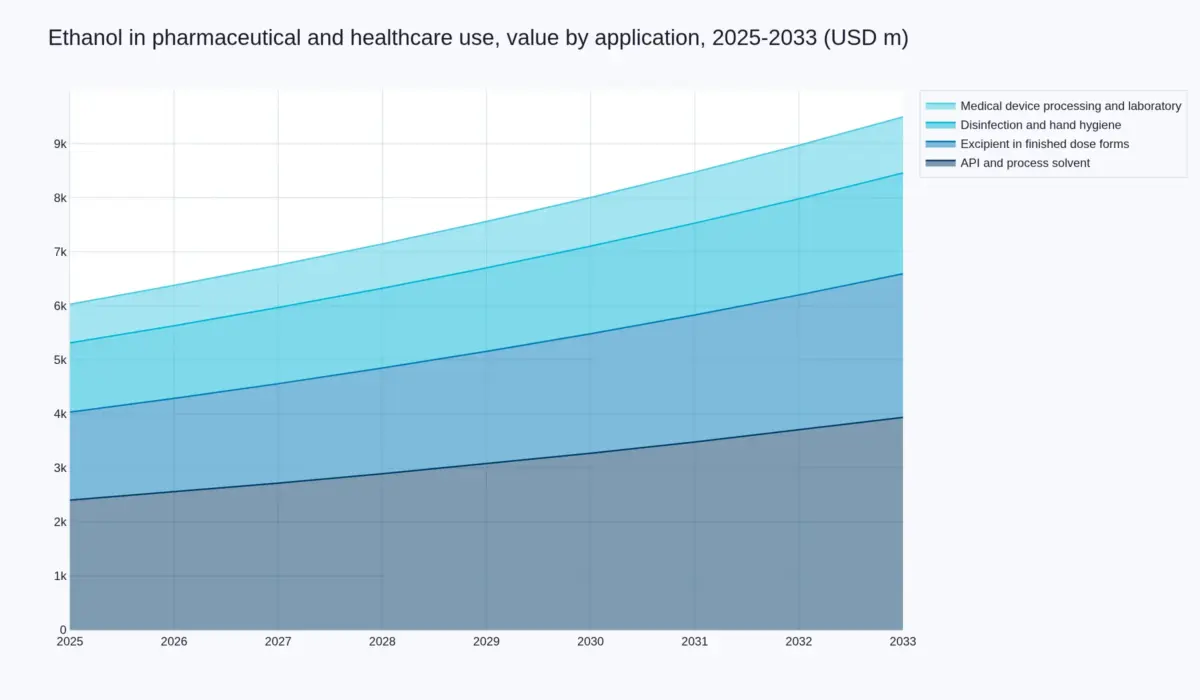
Every other line in this series has something to say about timing. This one does not. Built application by application, the first three years compound at 5.83% and the last five at 5.85% — a market that runs on clinical trial and fill-finish volumes rather than on a mandate or a tax rate, and therefore grows at very close to a constant rate for eight years.
| Year | API and process solvent, USD m | Excipient, USD m | Disinfection and hand hygiene, USD m | Device processing and laboratory, USD m | Total value, USD m | Volume, m litres | Implied price, USD/litre |
|---|---|---|---|---|---|---|---|
| 2025 | 2,403 | 1,628 | 1,283 | 713 | 6,027 | 4,700 | 1.2823 |
| 2026 | 2,556 | 1,731 | 1,344 | 747 | 6,378 | 4,881 | 1.3067 |
| 2027 | 2,718 | 1,840 | 1,409 | 783 | 6,750 | 5,070 | 1.3314 |
| 2028 | 2,891 | 1,957 | 1,476 | 820 | 7,144 | 5,266 | 1.3566 |
| 2029 | 3,075 | 2,080 | 1,546 | 859 | 7,561 | 5,469 | 1.3825 |
| 2030 | 3,271 | 2,212 | 1,620 | 900 | 8,003 | 5,680 | 1.4090 |
| 2031 | 3,479 | 2,351 | 1,698 | 944 | 8,472 | 5,899 | 1.4362 |
| 2032 | 3,700 | 2,500 | 1,779 | 989 | 8,968 | 6,127 | 1.4637 |
| 2033 | 3,935 | 2,658 | 1,864 | 1,036 | 9,493 | 6,363 | 1.4919 |
The compendial share is the whole of the premium over the parent. The two compendial applications are USD 4,031 million of the 2025 value and USD 6,593 million of the 2033 value; the two specification applications are the rest. That is the 73.9 per cent of absolute growth the report attributes to grade A, arriving one year at a time, and it is the reason this page grows at 5.85 per cent while the ethanol market it sits inside grows at 3.99. Take the compendial mix out and there is no premium left — which the assumptions table above already says, and which the annual build now shows.
Three totals for 2033, all disclosed. The application cut in this table totals USD 9,493 million. The regional cut totals USD 9,487 million. The headline is USD 9,492 million. The page already stated the six-million-dollar spread between the first two; the third figure sits between them and is the baseline the scenarios are run against. None of the three is adjusted to meet the others.
A two-million-dollar rounding gap in the base year, stated rather than absorbed. The four applications add to USD 6,027 million in 2025 against a headline of USD 6,025 million. The gap is inside the grade split, which carries compendial at 4,030 (API 2,403 plus excipient 1,628 gives 4,031) and specification grade at 1,995 (disinfection 1,283 plus devices 713 gives 1,996). One million dollars each, from rounding the application lines to whole millions. It is immaterial and it is visible, which is the point.
What the table cannot tell you. The compendial mix is held at its 2025 composition through the whole path, and the assumptions table above names that as the least evidenced assumption in the model, with a tested range of plus or minus five points. A five-point shift toward compendial material would raise the price line without touching the volume line; a five-point shift away would do the reverse. Everything in this table downstream of that assumption inherits it.
Forecast and scenarios
| Scenario | 2025, USD m | 2033, USD m | CAGR |
|---|---|---|---|
| Conservative | 6,025 | 8,182 | 3.90% |
| Baseline | 6,025 | 9,492 | 5.85% |
| Optimistic | 6,025 | 11,152 | 8.00% |
The baseline is built bottom-up from the four applications and checked against the six regions. The two cuts do not land on the same figure: the application cut totals USD 9,493 million in 2033 and the regional cut USD 9,487 million, a six-million-dollar spread worth 0.06 per cent. It is stated rather than absorbed into a rounding note, because a reader who adds up the regional column should find the gap where it actually is.
| Assumption | Baseline | Range tested | What moves it |
|---|---|---|---|
| Compendial volume growth | 4.52% | 3.0% – 6.0% | API and fill-finish capacity location; Indian self-sufficiency in solvents |
| Compendial price growth | 1.74% | 0.5% – 3.0% | Feedstock and energy; distributor competition compressing the documentation premium |
| Specification-grade volume growth | 3.00% | 0.5% – 5.0% | Hand hygiene normalisation; hospital-acquired infection control spending |
| Specification-grade price growth | 1.73% | 0.5% – 3.0% | Bulk ethanol floor; excise |
| Grading assumption | No change in compendial mix | Mix shift ± 5 points | Emerging-market pharmacopoeial adoption |
What would change this number
Four things, in order of force. A harmonised EU hazard classification of ethanol would land on the 33.1 per cent of value that sits in the disinfection pool, and the conservative path is roughly what that looks like. A deeper normalisation of hand hygiene than the 3.00 per cent volume growth assumed would pull the whole healthcare-specification line closer to flat. Indian and Chinese self-sufficiency in pharmaceutical solvents would relocate demand rather than grow it, and would compress the compendial premium as new capacity qualifies. And a credible shift away from alcohol-based disinfection — real but slow — would take volume out of the only line whose price is set by the bulk market rather than by a specification.
What would not change it: fuel ethanol prices, except through feedstock. This market is 4,700 million litres — 3.3 per cent of global ethanol volume — and it pays what it must.
Table of Contents
Table of Contents
- Executive Snapshot
- Market Size and Growth at a Glance (2025–2033)
- Largest and Fastest-Growing Applications
- Regional Structure and the 2033 Handover
- Scope, Definition and Perimeter
- What This Report Sizes — Ethanol, Not the Pharmaceutical Industry
- The Use-View Rule — What May and May Not Be Added
- Exclusions — Finished Medicinal Products, Captive Production, Biotechnology Feed
- Compendial Grade versus Healthcare Specification Grade
- Research Methodology and Assumption Stack
- Bottom-Up Build by Application and by Region
- Volume, Price and Value Decomposition
- Assumption Ranges and Sensitivity
- Market Size, Forecast and Scenario Outlook
- Baseline, Conservative and Optimistic Paths
- The Year-by-Year Path — 5.83 Per Cent in the First Three Years, 5.85 in the Last Five
- Why Price Contributes 1.91 Points of a 5.85 Per Cent Growth Rate
- The 0.06 Per Cent Gap Between the Two Cuts
- Segmentation
- By Grade — Compendial and Specification
- By Application — Solvent, Excipient, Disinfection, Device and Laboratory
- By End User — Pharmaceutical Manufacturers, CDMOs, Hospitals and Laboratories
- Regional Analysis
- North America and Europe — Compendial Mix and Verification Cost
- Asia Pacific — Capacity Location and the Price Discount
- Latin America, Middle East and Africa, FSU
- Competitive Landscape
- Value Chain and Supply Structure
- Investment Activity
- Technology and Innovation
- Market Risk
- Regulatory Landscape
- Strategic Outlook
- Appendix — Assumptions, Conversions and Sources
Competitive Landscape
Competitive Landscape: Four Layers That Do Not Compete With Each Other
There is no such thing as market share in this market, and any figure presented as one should be treated as an artefact of a boundary someone chose. The reason is structural rather than a gap in the data. The litres are made by companies whose business is fuel, sold by companies whose business is documentation, formulated by companies whose business is infection control, and in a few important cases made by the buyer itself. Those four groups do not bid against each other. They sit in series.
The consequence for a reader is that “who leads the pharmaceutical ethanol market” has no single answer. Ask who can deliver 200,000 litres of USP-grade ethanol to a validated site in a fortnight and the list is short. Ask who controls the molecules that end up in a medicine and the list includes refiners who never touch a pharmaceutical plant.
Layer one — fuel-scale distillers who happen to hold a compendial file
The molecule is made at fuel scale. A dry mill running 100 million gallons a year can produce a compendial grade by adding a polishing train and a quality system, and several of the large American, Brazilian and European producers do exactly that: ADM, POET and Valero on the American side, Raízen and the Brazilian cane complex, Tereos and Cristal Union in France, CropEnergies in Germany, Manildra in Australia, NCP Alcohols in South Africa.
Their economics are set elsewhere. The marginal gallon of ethanol in the world is priced by a blend mandate and a corn crush, and a compendial parcel is a small premium-priced sliver of a very large fuel business. That has two effects a buyer should understand. It makes pharmaceutical-grade supply structurally long, because it arrives as a by-product of investment decisions taken for another reason. And it makes the supplier’s commitment to the pharmaceutical grade contingent: when fuel margins are strong, the polishing train is a rounding error and receives no attention; when fuel margins collapse, the premium becomes interesting and capacity appears.
MGP Ingredients at Atchison, Kansas is the clearest example of a producer whose identity is high-purity alcohol rather than fuel, and it is the exception that proves the rule: the companies that treat pharmaceutical alcohol as a core product are few, and they are mostly of sub-fuel scale.
Layer two — the excipient houses that own the document
This is the layer that is genuinely consolidated, and it is the one the structured data on this page describes. The competitive asset is not the ethanol. It is the file: a compendial release that a qualified person will sign, a change-control history, an audited quality system, a supplier qualification package that satisfies the customer’s own auditor, and in Europe the written confirmation that excipient users are obliged to obtain.
That layer is occupied by a small number of organisations — Merck KGaA through its excipient documentation programme, Avantor through its J.T. Baker line, Thermo Fisher, Honeywell through Burdick & Jackson, and specialist high-purity producers such as Greenfield Global. Six suppliers of real scale is a fair description of the specification layer, and it is where the moderate consolidation in this market actually sits. The concentration is in distribution and documentation, not in distillation.
What these firms sell is availability and assurance at small lot size: a 200-litre drum or a 1,000-litre IBC, delivered inside a week, with a certificate of analysis that matches a specification the customer’s auditor has already approved. The bulk producer cannot serve that demand economically, and the formulator cannot buy a 25-tonne parcel to make a batch of cough syrup.
Layer three — the formulators who buy the litre and sell the claim
The 33.1 per cent of value sitting in healthcare specification grade is not sold by ethanol companies at all. It is sold by infection-prevention businesses — Ecolab, Diversey, B. Braun, Schülke, BODE, Steris, GOJO, Reckitt and Procter & Gamble in consumer formats — whose product is a claim, a pack and a hospital relationship, with ethanol as the active ingredient they buy by the tanker.
Their competitive position does not depend on ethanol at all until it does. In 2020 and 2021 it did: when ethanol was scarce, formulators reformulated, qualified isopropanol lines, and in some markets reduced alcohol content. Those decisions have not been fully reversed, and they are part of why the specification-grade pool now grows at 3.00 per cent in volume rather than at the rate the pre-pandemic trend implied.
Layer four — the buyer who makes its own
The most under-modelled competitor in this market is the customer. Plasma fractionators run cold ethanol processes at industrial scale and recover and re-distil their own solvent; large pharmaceutical sites with solvent-recovery loops do the same. Every litre recycled is a litre not bought, and it does not appear in any supply-side capacity count.
This is also where the most interesting substitution threat sits. Cold ethanol fractionation is the classical route to plasma-derived therapies, and chromatography has been displacing parts of it for two decades. A fractionator that moves a fraction from ethanol precipitation to a chromatographic step does not reduce its ethanol purchases by a percentage point. It removes a demand pool.
What is actually being sold, and to whom
Read across the four layers and the commercial logic becomes simple. The distiller sells a commodity with a specification attached. The excipient house sells the specification and the logistics. The formulator sells the claim. The fractionator sells a validated process that happens to consume solvent.
Only the first two are in this market as suppliers, and only the second has pricing power in it. The compendial premium of 1.632× over specification grade is not a scarcity rent on ethanol. It is the price of the document, the parcel and the audit, and it is bounded by how expensive it is for a customer to requalify an alternative source — typically months of work, and worth doing only above a volume that most customers do not reach.
Implications for the forecast
Three. First, no supplier can build a dominant position in this market by adding distillation capacity, because capacity is not the constraint. Second, the compendial premium is more likely to compress than to widen, as distributors compete on service and as Asian producers qualify compendial supply against United States and European pharmacopoeias. Third, the healthcare specification half of the market is a formulated-product market wearing an ingredient label, and its growth rate should be read as a proxy for hospital infection-control budgets rather than for anything ethanol-specific.
Value Chain
Value Chain: Five Gates Between Fermentation and a Signed Release
Ethanol reaches a pharmaceutical plant through five distinct operations, and the price paid at the end is the sum of what each adds. Understanding which gate creates the premium is the difference between a supplier who can defend a price and one who cannot.
Gate one — fermentation and distillation to the azeotrope
Whether from corn, cane, molasses, wheat or a cellulosic feedstock, fermentation produces a dilute beer that is distilled to approximately 95.6 per cent ethanol by weight. This is as far as simple distillation goes: at that composition ethanol and water form a minimum-boiling azeotrope and further distillation produces the same mixture. Everything downstream exists because of that physical fact.
The distillation gate is where the energy is consumed and where the cost of the molecule is largely set. It is also the gate over which the producer has least commercial control, because the same column serves the fuel market.
Gate two — dehydration past the azeotrope
Getting to anhydrous ethanol requires breaking the azeotrope — molecular sieve with a 3A zeolite, membrane pervaporation, or a pressure-swing or entrainer route. This gate determines whether the product is 96 per cent or anhydrous, and the distinction matters commercially rather than chemically: some compendial monographs are written for the 96 per cent material, and formulation steps that must remain water-free require the anhydrous grade. Two products, one molecule, different equipment.
Gate three — compendial polishing and release
The third gate is where this market’s premium is created, and it is mostly laboratory rather than plant. Activated carbon treatment and ion exchange remove the trace aldehydes, esters and higher alcohols that a pharmacopoeial monograph limits; filtration removes particulates; and a quality-control release tests identity, assay, water content, volatile impurities, non-volatile residue and, where the monograph requires it, elemental impurities. The output is not a purer solvent in any commercially meaningful sense. It is a documented one.
Residual ethanol itself barely constrains a formulation. Under the international residual solvents guideline ethanol sits in Class 3 — solvents of low toxic potential, with no health-based exposure limit required — where amounts of 50 milligrams per day or less, corresponding to 5,000 parts per million or 0.5 per cent under the guideline’s Option 1 approach, are acceptable without justification. A formulator can therefore use ethanol freely and does. What the compendial gates are controlling is everything else in the drum.
Gate four — packaging and dedicated logistics
The fourth gate adds value in a way that is easy to overlook and expensive to build. Ethanol is a class 3 flammable with a low flash point, and a pharmaceutical parcel must arrive with no cross-contamination from a previous cargo. Dedicated stainless tankers, validated cleaning between campaigns, appropriate packaging and documented chain of custody are capital and discipline, and they are why a formulator buying 20,000 litres pays more per litre than an industrial buyer taking a road tanker.
Gate five — qualification at the customer
The final gate belongs to the buyer and is the real barrier to switching. Before a supplier’s ethanol enters a licensed product, the customer qualifies it: specification approval, audit, change-control agreement, and in Europe the written confirmation that excipient users must obtain under the falsified-medicines framework. This is months of work, and it is what caps the compendial premium at 1.632× rather than letting it widen: the premium can rise only as far as the cost a customer would incur to avoid it.
Ethanol as a process reagent — the cold fractionation of plasma
The most technically distinctive demand in this market is not a solvent at all. Plasma-derived therapies are separated by adding ethanol to plasma at sub-zero temperature and stepping the concentration, pH and ionic strength so that different proteins precipitate in sequence. Ethanol works here because it is a cheap precipitant that reduces protein solubility while allowing the process to run cold, which both protects the proteins from denaturation and suppresses bacterial growth.
This demand pool has properties that no other part of this market has. The process is validated for decades, the specification is uncompromising, and the ethanol is consumed as a reagent rather than as an ingredient that must be declared. It is also, for exactly those reasons, the most exposed to substitution: chromatography can separate what precipitation separates, and it does so without a flammable solvent.
Ethanol as a vehicle — lipid nanoparticles
The newest demand is also the most specification-sensitive. Lipid nanoparticles carrying nucleic acid payloads are now commonly manufactured by rapid mixing, in which an ethanol phase containing the dissolved lipids meets an aqueous phase containing the nucleic acid under controlled pH and flow rate; the ethanol is removed downstream and the resulting particle is what the patient receives.
Ethanol is not an excipient in the finished product here. It is the solvent that makes the particle possible, and the grade is nonetheless compendial, because the material enters a sterile manufacturing environment and must be documented to the same standard as anything else that does. This is a small volume of very high-specification material, and it is the reason the technology chapter of this market is more interesting than the molecule deserves.
The excise constraint that fuel ethanol does not carry
Ethanol for a licensed medicine cannot be denatured, because the denaturant would enter the product. It is therefore excise-paid, and the duty is carried in inventory until drawback is claimed. That single fact shapes the trade: it puts a balance-sheet requirement between the distiller and the pharmaceutical plant, it favours distributors with trade-compliance capability over producers, and it means the price a formulator pays embeds a tax that the fuel market does not pay on the same molecule.
Who holds the margin
Across the five gates, the margin that is specific to this market accrues at gates three, four and five — polishing, packaging and qualification. Gate one earns the commodity return, gate two earns an equipment return, and the rest is the price of a document and a parcel. That is why the companies described in the competitive chapter as the specification layer are the ones with pricing power, and why a distiller’s attempt to move downstream into pharmaceutical supply is a distribution problem before it is a chemistry problem.
Investment Activity
Investment Activity: Nobody Builds a Plant to Make Pharmaceutical Ethanol
The single most useful fact about capital formation in this market is that it is almost entirely a by-product. A compendial polishing train — carbon treatment, ion exchange, filtration, a validated quality-control laboratory and a dedicated packaging line — is a small increment against the capital cost of a fuel-scale dry mill or a sugarcane complex. That asymmetry determines everything that follows.
The polishing train is a rounding error against the dry mill
When a producer decides to serve pharmaceutical and healthcare customers, the decision is a marginal one taken after the main plant decision, not before it. The consequence is that supply of the two grades tracked in this report responds to investment made for the fuel market. A wave of fuel capacity creates a wave of potential compendial capacity a year or two later, whether or not anyone wanted it.
That is why the compendial premium has never behaved like a scarcity price. Scarcity prices require a capacity constraint that cannot be relieved cheaply; here the relieving investment is a modest line item on somebody else’s project.
The pandemic capacity, and the half that stranded
The one period when investment in this market was a headline was 2020 and 2021, and it was investment in the wrong thing. Hand sanitiser demand exploded, ethanol for it became scarce, and producers responded — distilleries, chemical companies and entirely new entrants built filling capacity and bought feedstock at any price.
The regulatory correction was explicit and dated. The United States drug regulator withdrew its temporary hand-sanitiser guidance documents, holding that consumers and health professionals were no longer having difficulty obtaining alcohol-based hand sanitiser. Producers who had been operating under those flexibilities had to stop manufacturing hand sanitiser under them by 31 December 2021, and stop distributing remaining stock produced under them by 31 March 2022. Continuing producers had to comply instead with the tentative final monograph for over-the-counter topical antiseptics, together with current good manufacturing practice. That is a precise instrument with a precise date, and it converted a temporary capacity wave into a permanently lower demand base.
The arithmetic of that correction is visible in the forecast rather than asserted: the healthcare specification pool is modelled at 3.00 per cent volume growth, which is roughly what hospital infection-control budgets support once the pandemic demand has been subtracted. Had that capacity wave been met by genuinely new ethanol capacity rather than by reallocated industrial ethanol, the stranding would be larger still.
Where the capital actually goes now
Four destinations, none of them a pharmaceutical ethanol plant.
Sterile fill-finish and formulation capacity. The build-out of biological drug product capacity — Lonza, Samsung Biologics, WuXi Biologics, Patheon and the rest — creates demand for anhydrous ethanol inside classified environments: as a lipid solvent for nanoparticle formulation, as a cleaning and depyrogenation agent, as a precipitation reagent in nucleic acid processing. This is the fastest-growing demand for the highest specification of the molecule, and it is being financed as pharmaceutical capex, not as ethanol capex.
Good-manufacturing-practice packaging and dedicated logistics. The unglamorous investment that actually determines who can serve this market: stainless parcels, validated cleaning between campaigns, temperature and humidity control, and segregation from non-pharmaceutical grades on the same site.
Solvent capacity in Asia. Indian and Chinese investment in active-ingredient manufacturing, supported in India by production-linked incentive schemes, relocates solvent demand toward the point of synthesis. The investment is in the drug substance, and the ethanol follows it.
Feedstock-adjacent capacity with a purity dividend. Brazil’s corn ethanol plants in the interior, and membrane-dehydration retrofits at existing distilleries, both add neutral-grain capacity that can be upgraded to compendial grade more cheaply than greenfield construction allows.
A capex figure I will not invent
There is no published series that isolates investment in pharmaceutical-grade ethanol capacity, and any number presented as one would be a guess wearing a citation. So this report gives a direction and not a magnitude: investment activity in this market is rising, driven by the three destinations above, and it is entirely dwarfed in absolute terms by investment in the fuel and industrial ethanol plants that make the molecule in the first place. The rising trend describes the polishing, packaging and qualification layer, which is where the money that is specific to this market goes.
Working capital is the real barrier to entry
One economic feature separates this trade from the fuel trade and gets almost no attention. Ethanol destined for a medicine cannot be denatured, because a denaturant cannot enter a licensed product. It therefore travels excise-paid. A producer or distributor holding compendial inventory is financing duty on every litre in the tank, and recovering it later through drawback mechanisms that depend on the destination of the finished product and on documentation that must survive an audit years afterwards.
That is a balance-sheet requirement, not a plant requirement, and it is why the layer that controls this market is a distribution layer with sophisticated tax and trade-compliance functions rather than a distillation layer. A new entrant can buy a polishing train. Buying the working capital, the drawback expertise and the audit trail takes longer.
What the investment picture implies for the forecast
It implies that supply will not be the binding constraint on this forecast anywhere in the period to 2033, and that the risk to the compendial premium runs one way. Where growth is genuinely constrained, it is constrained by demand — by how much pharmaceutical is manufactured and where, and by how much hospital infection control is funded — and by regulation, which is the subject of the two chapters that follow.
Technology & Innovation
Technology and Innovation: A Mature Molecule Inside an Immature Process
Ethanol has been distilled for a thousand years and has no technology road map left. Any chapter that presents this market as a technology story is describing the wrong thing. The honest position, and the one this report takes, is that the molecule is mature, the equipment that purifies it is mature, and the innovation that matters happens in the process of the customer — which is why the innovation intensity of this market reads moderate rather than low even though nothing about ethanol itself is changing.
Dehydration is the only hard engineering problem in the chain
The physical constraint that structures the entire value chain is the azeotrope: ethanol and water form a minimum-boiling mixture at approximately 95.6 per cent ethanol by weight, and simple distillation cannot pass it. Everything above that concentration requires a separate technology — molecular sieve with a 3A zeolite, membrane pervaporation, pressure swing or an entrainer.
That is where the engineering competition sits. Sieve systems dominate at scale because they are robust and well understood; their economics turn on regeneration energy and on bead life, and bead replacement is a real operating cost that buyers rarely see. Membrane systems compete at smaller scale and in retrofits, where their lower energy demand and smaller footprint outweigh a higher capital cost per daily litre. The direction of travel is toward lower energy per litre rather than toward a new chemistry, because the thermodynamic floor is fixed.
The commercial consequence is worth stating. Because dehydration is a discrete, purchasable step, the difference between a 96 per cent product and an anhydrous one is an equipment decision rather than a technological capability. That is why the anhydrous grade is not scarce, and why its premium over the azeotropic grade is modest.
Analytical control and data integrity
The second front is not chemistry at all. Compendial release depends on analytical testing, and the cost of a batch is heavily influenced by how long release takes and how much re-testing it generates. Process analytical technology — near-infrared or Raman spectroscopy at the column outlet, calibrated against the reference methods — shortens that loop and reduces the frequency with which a batch is held. The gain is working capital and release time, not purity.
Alongside it sits data integrity. A quality-control laboratory in a regulated environment must be able to demonstrate that an analytical result was produced by the method it claims, from an instrument under control, without a manual transcription. That has moved from paper to validated software, and it has become a real barrier to entry in the specification layer described in the competitive chapter: a distributor can buy a high-purity tank, and cannot easily buy a twenty-year audit trail.
Where innovation changes the shape of demand — rapid mixing
The most interesting technical development in this market is not in ethanol production at all. Lipid nanoparticles carrying nucleic acid payloads are now commonly manufactured by rapid mixing: an ethanol phase containing dissolved lipids is combined with an aqueous phase containing the nucleic acid under controlled pH and flow rate, and the particle forms as the solvent environment changes. The ethanol is then removed downstream, and what the patient receives is a particle, not a solvent.
Ethanol’s role here is functional and difficult to substitute. It dissolves the lipids at the concentrations the process needs, it is miscible with the aqueous phase in the proportions used, and it is removable to parts-per-million levels by tangential-flow filtration without denaturing the payload. The demand it creates is small in litres and demanding in specification, and it is the fastest-growing pocket of compendial demand in this market.
The same logic explains ethanol’s persistence in nucleic acid processing generally: precipitation of nucleic acids from aqueous solution with ethanol and a salt is a cheap, scalable concentration step that chromatography performs more precisely at far higher cost.
Where innovation removes demand — chromatography for plasma
The mirror image of that story sits in plasma fractionation. Cold ethanol fractionation separates proteins by stepping ethanol concentration, pH and ionic strength at sub-zero temperature, and it has been the industrial standard for three quarters of a century because it is cheap, scalable and microbially inhibitory. Chromatography separates more precisely and does not require a flammable solvent, and it has been displacing individual fractions for two decades.
Each displacement is small and permanent. That is the pattern for this market’s technology exposure: demand is not lost through a dramatic substitution, but through a series of validated process changes, each of which removes a pool that never returns.
Continuous manufacturing reduces solvent intensity, quietly
The shift from batch to continuous processing in small-molecule manufacture reduces the solvent held up in vessels and the solvent consumed in cleaning between batches. The effect on this market is slow and adverse at the margin: less ethanol per kilogramme of active ingredient, in a segment that otherwise grows with output. It is not large enough to change the forecast, and it is the main reason the compendial volume growth rate is modelled at 4.52 per cent rather than at the growth rate of pharmaceutical output itself.
Patent activity is low, and that is the finding
Patent activity in ethanol as a material is negligible, and this report records that rather than dressing it up. The relevant intellectual property sits in three adjacent places: equipment vendors who patent dehydration and mixing hardware, formulators who patent particle compositions and processes, and producers who patent purification sequences. A supplier of ethanol cannot build a technology moat. It can build a documentation and logistics moat, which is a different asset and is the subject of the competitive chapter.
For a reader deciding where technology risk sits in this market, the answer is that it sits with the customer. A pharmaceutical process change is a threat to a supplier’s volume; no ethanol technology change is a threat to a customer’s supply.
Market Risk
Market Risk: Six Ranked, One Dominant
This market’s risks are not the risks of a commodity. A commodity’s risk is price. Here the price is the stable part — both grades escalate at almost the same rate, 1.74 and 1.73 per cent a year — and the risk sits in whether a third of the value is allowed to keep being sold as it is currently sold, and in whether a two-thirds majority keeps growing at the rate pharmaceutical output grows.
| Rank | Risk | Exposure | Direction |
|---|---|---|---|
| 1 | EU hazard classification of ethanol as a biocide | 33.1% of value — USD 1,995m | Downside |
| 2 | Hand hygiene demand normalisation | Grade B volume, 2,100m litres | Downside |
| 3 | Feedstock and energy transmission | Both grades, price | Two-way |
| 4 | Compendial revision and elemental impurities | Grade A, revalidation cost | Cost, not volume |
| 5 | Substitution — isopropanol, chromatography, solvent replacement | Grade B disinfection; captive fractionation | Downside, slow |
| 6 | Trade policy and freight | Regional price spreads | Two-way |
1. The EU hazard classification question, which is open
This is the risk that matters, and it is live rather than hypothetical. In February 2026 the European Chemicals Agency’s Biocidal Products Committee adopted opinions supporting the approval of ethanol as an active substance for product-type 1 (human hygiene, including hand disinfectants), product-type 2 (disinfectants not intended for direct contact with humans or animals) and product-type 4 (food and feed areas), concluding that safe use had been demonstrated for all uses in those product types.
It then declined to reach a conclusion on ethanol’s carcinogenic or reproductive properties. The reasons it gave are specific and worth stating, because they define what could close the question later: the applicant’s dossier lacked data on dermal exposure, which is the key route for a biocide; the available inhalation data had not been generated to standard guidelines; and most of the evidence on carcinogenicity and reproductive toxicity comes from voluntary oral consumption of alcoholic beverages, which the committee did not consider an appropriate basis for decisions about biocidal uses. No new hazard classification was proposed as a result.
Read precisely, that is an approval and an open question in the same document. If a harmonised classification as a carcinogen or a reproductive toxicant follows — through the classification and labelling route rather than the biocides route — the consequences land on labelling, safety data sheets, product authorisation dossiers and, in some formulations, on whether the product can be sold to the claims it currently makes. The pool exposed is the entire healthcare specification grade: USD 1,995 million in 2025, 33.1 per cent of this market’s value.
This report does not forecast that outcome. It prices it: the conservative path, at USD 8,182 million for 2033 against a baseline of USD 9,492 million, is roughly what a negative outcome concentrated on the disinfection pool looks like.
2. Hand hygiene has already normalised, and the model says so
The second risk is not a forecast risk but an accounting one that most treatments of this market get wrong. The healthcare specification pool grew violently in 2020 and 2021, then corrected. The model here assumes 3.00 per cent volume growth from 2025, which is a hospital-budget growth rate, not a pandemic growth rate. The risk is that this is still too generous: formulators that reformulated during the shortage — qualifying isopropanol lines, reducing alcohol content, shifting to non-alcohol chemistries — have not all reversed those decisions, and every formulation that stays reformulated is volume that never comes back.
3. Feedstock and energy are transmitted, not absorbed
This market is 4,700 million litres against a global ethanol pool of 141,100 million litres — 3.3 per cent. It is a price taker. The marginal litre of ethanol in the world is priced by a blend mandate and a grain or cane crush, and a pharmaceutical buyer inherits that volatility in a market it does not set.
The transmission is asymmetric in an important way. A rise in feedstock cost passes through into both grades within a contract cycle, because no supplier can absorb it. A fall does not pass through as quickly, because the compendial grade’s price is anchored to a qualification process rather than to a spot market. Buyers should expect the premium to widen on the way down, which is precisely when they are least inclined to renegotiate.
4. Compendial revision is a cost event, not a volume event
Pharmacopoeial monographs are revised, and the international guideline on elemental impurities has already forced excipient suppliers across every category to requalify. For ethanol the exposure is modest — the molecule is simple and the monographs are mature — but a revised limit on a trace impurity triggers revalidation, renewed customer qualification and, in the worst case, a batch hold. It does not change how much ethanol a plant buys. It changes what the batch costs to release.
5. Substitution is real, slow, and concentrated in two places
Two substitution threats deserve names. In disinfection, isopropanol is a genuine functional substitute for ethanol at similar cost and similar efficacy, and it is already used where a formulation permits. In plasma fractionation, chromatography continues to displace cold ethanol precipitation fraction by fraction, and each displacement removes a validated ethanol demand rather than trimming it.
Elsewhere the threat is weaker than the marketing implies. Solvent substitution in small-molecule synthesis is constrained by the same pharmacopoeial and toxicological logic that made ethanol attractive in the first place — it sits in the low-toxicity class with no health-based exposure limit required — and “alcohol-free” claims in consumer healthcare are a marketing position rather than a manufacturing trend.
6. Trade policy shows up as price, not volume
Ethanol moves across borders subject to tariff lines and anti-dumping actions that change without notice, and the excise treatment of a compendial parcel is jurisdiction-specific. The effect is visible in this report as regional price dispersion rather than as missing volume: Europe at USD 1.455 a litre against Asia Pacific at 1.063 is partly a compendial-mix difference and partly a tax and trade difference, and the second part can move.
The quantified sensitivity
| Path | 2033, USD m | CAGR | Difference from baseline |
|---|---|---|---|
| Conservative | 8,182 | 3.90% | −1,310 |
| Baseline | 9,492 | 5.85% | — |
| Optimistic | 11,152 | 8.00% | +1,660 |
The band is wide because the two halves of this market are driven by things that do not correlate: pharmaceutical manufacturing output on one side, hospital infection-control budgets and biocide regulation on the other. A reader who wants a single risk statement should take this one. The downside is a regulatory event with a date on it. The upside is a manufacturing-location shift already under construction.
Regulatory Landscape
Regulatory Landscape: Two Regimes on Two Clocks
The most common error in reading this market’s regulation is to treat it as one regime. Ethanol in a medicine and ethanol in a disinfectant are the same molecule governed by different law, decided by different bodies, on different timetables, with different consequences for a supplier. A change in one does not imply a change in the other, and a supplier that satisfies one has satisfied nothing about the other.
Regime one — ethanol as a medicine ingredient
As an excipient and process solvent, ethanol is governed by pharmacopoeial monographs and by good manufacturing practice. The European Pharmacopoeia carries separate monographs for ethanol at 96 per cent and for anhydrous ethanol; the United States Pharmacopoeia likewise distinguishes the azeotropic material from the dehydrated grade. Compliance is demonstrated by release testing against the monograph, and the supplier’s quality system is audited rather than approved — a distinction that matters, because there is no licence to hold and therefore no licence to lose. A supplier that falls out of compliance loses customers one qualification at a time.
Three instruments do most of the practical work. The residual solvents guideline places ethanol in Class 3 — low toxic potential, no health-based exposure limit required — with amounts of 50 milligrams per day or less, corresponding to 5,000 parts per million or 0.5 per cent under Option 1, acceptable without justification. The elemental impurities guideline governs what else may be in the drum and has already forced requalification across the excipient industry. And in Europe the falsified medicines framework obliges the excipient user to obtain written confirmation from the supplier that the material was manufactured under appropriate good manufacturing practice, based on a documented risk assessment. That written confirmation is the single most consequential piece of paper in this trade, because it sits between the supplier and the customer’s licence.
Regime two — ethanol as a biocidal active substance in the European Union
Disinfectants are regulated as biocidal products, and the active substance must be approved before products containing it can be authorised. This is a slower and more consequential process than excipient compliance, because it can end a use rather than merely condition it.
The status as at this report is specific. In February 2026 the Biocidal Products Committee of the European Chemicals Agency adopted opinions supporting the approval of ethanol for product-type 1 (human hygiene, including hand disinfectants), product-type 2 (disinfectants and algaecides not intended for direct application to humans or animals) and product-type 4 (food and feed areas), having concluded that safe use had been demonstrated for all uses in those product types. Final decisions rest with the European Commission together with the member states, on the basis of those opinions.
The same opinions are the reason this market carries a live classification risk. The committee did not reach a conclusion on ethanol’s carcinogenic or reproductive properties, citing the absence of dermal exposure data in the applicant’s dossier, inhalation data not generated to standard guidelines, and a carcinogenicity evidence base drawn largely from voluntary oral consumption of alcoholic beverages. No new hazard classification was proposed on that basis. Approval and an unresolved hazard question are not contradictory: they are a committee approving the use it was asked about while declining to settle a question it was not equipped to settle.
Regime three — ethanol as an over-the-counter drug in the United States
In the United States the hand-sanitiser use sits under the over-the-counter drug framework rather than under a biocide regime, and here the position is settled and dated. Temporary flexibilities granted during the public health emergency were withdrawn once supply normalised. Producers operating under them had to stop manufacturing hand sanitiser under those flexibilities by 31 December 2021 and had to stop distributing remaining stock produced under them by 31 March 2022. To continue, a producer must comply with the tentative final monograph for over-the-counter topical antiseptics, as amended, together with current good manufacturing practice requirements.
That is a cleaner regulatory position than Europe’s, and it has already done the damage it was going to do: the capacity and the product lines that depended on the flexibilities are gone, which is why this report models the healthcare specification pool at 3.00 per cent volume growth rather than at its pandemic trajectory.
Regime four — excise, denaturation and drawback
Ethanol is taxed as a beverage alcohol base everywhere, and the pharmaceutical use earns relief rather than exemption. Denaturation — adding a bitterant or a denaturant so the ethanol cannot be drunk — is the standard route to tax-free industrial use and is unavailable here, because the denaturant would enter a licensed medicine. Compendial ethanol is therefore excise-paid, and the duty is recovered later through drawback mechanisms that depend on the destination of the finished product and on documentation that must survive audit.
This is a regulatory constraint with a commercial consequence: it creates a working-capital requirement that fuel ethanol does not carry, and it explains why the layer that controls this market is a distribution layer with trade-compliance capability rather than a distillation layer.
The instruments, and what each obliges
| Regime | Instrument | What it obliges |
|---|---|---|
| Ingredient, EU | European Pharmacopoeia monographs; good manufacturing practice; written confirmation under the falsified medicines framework | Monograph release testing; documented GMP; written supplier confirmation to the excipient user |
| Ingredient, US | United States Pharmacopoeia monographs; current good manufacturing practice | Monograph release testing; audited quality system |
| Residual solvents | ICH Q3C(R9) | Class 3 solvent: 50 mg/day or 5,000 ppm (0.5%) acceptable without justification |
| Elemental impurities | ICH Q3D | Risk assessment and, where needed, control of elemental impurities |
| Biocide, EU | Regulation (EU) No 528/2012 | Active substance approval, then product authorisation; BPC opinions supporting product-types 1, 2 and 4 adopted February 2026 |
| OTC drug, US | Tentative final monograph for OTC topical antiseptics, as amended; CGMP | Compliance to manufacture hand sanitiser after the temporary COVID-era flexibilities were withdrawn |
| Excise | National duty regimes; drawback mechanisms | Duty-paid because denaturation is impossible; recovery on documented export or qualifying use |
What is not harmonised, and why it matters
There is no global excipient monograph and no mutual recognition of a compendial release. A batch qualified against the European Pharmacopoeia is not qualified against the United States Pharmacopoeia or the Japanese Pharmacopoeia without additional testing, and the differences are in the trace-impurity limits rather than in the assay. For a supplier, that is a cost of serving multiple markets and a reason why compendial supply concentrates in large organisations. For a buyer, it is why the same molecule carries a different price in Rotterdam and in Singapore, and why a global sourcing strategy for this material is harder than it looks.
The other gap is timing. A pharmacopoeial revision runs on a multi-year cycle with consultation. A biocide approval decision, or a classification proposal, can move faster than a customer’s requalification cycle. That asymmetry — the regulatory question settling before the commercial response can — is the mechanism by which the dominant risk in this market would actually arrive.