
Company Profile
Baker Hughes Company
Identifiers
| Legal name | Baker Hughes Company |
|---|---|
| Listing | Nasdaq: BKR (Class A common stock); 992.7 million Class A shares outstanding at 30 September 2026 |
| Incorporated | Delaware, United States (I.R.S. Employer Identification No. 81-4403168) |
| Headquarters | 575 N. Dairy Ashford Rd., Suite 100, Houston, Texas 77079-1121; co-headquarters in London |
| Chairman, President and Chief Executive Officer | Lorenzo Simonelli |
| Employees | Approximately 56,000 at 31 December 2025, of whom more than 45,000 work outside the United States |
| Footprint | Business conducted in more than 120 countries; employees in more than 85 countries; more than 150 nationalities represented |
| Wikidata | Q804353 |
| Pheonix entity | MIEN-node_d804aab1 |
| Official website | bakerhughes.com |
| Investor relations | investors.bakerhughes.com |
| Primary filings | Form 10-K, FY2025 · Form 10-Q, Q3 2026 (SEC CIK 1701605) |
Executive Summary
Baker Hughes Company is an energy technology company with a portfolio spanning the energy and industrial value chain. It reports through two heritage segments — Oilfield Services & Equipment (OFSE) and Industrial & Energy Technology (IET) — and added Chart Industries as a third reporting segment on 16 July 2026. Revenue was USD 27,733 million in the year to 31 December 2025, essentially flat on FY2024, while adjusted EBITDA rose 5 per cent to USD 4,825 million at a record 17.4 per cent margin.
The shape of the company changed materially during 2026. It acquired Chart Industries for USD 13.6 billion in enterprise value and, across four portfolio actions, expects roughly USD 3 billion of gross proceeds in the year: the Precision Sensors & Instrumentation product line sold to Crane Company, a joint venture covering the surface pressure control product line, an initial public offering of the minority-owned drilling equipment business HMH, and the sale of Waygate Technologies to Hexagon. The last of those closed on 2 November 2026 at approximately USD 1.45 billion in pre-tax cash proceeds. At 30 September 2026 the balance sheet carried USD 18,264 million of total debt against USD 4,068 million of cash.
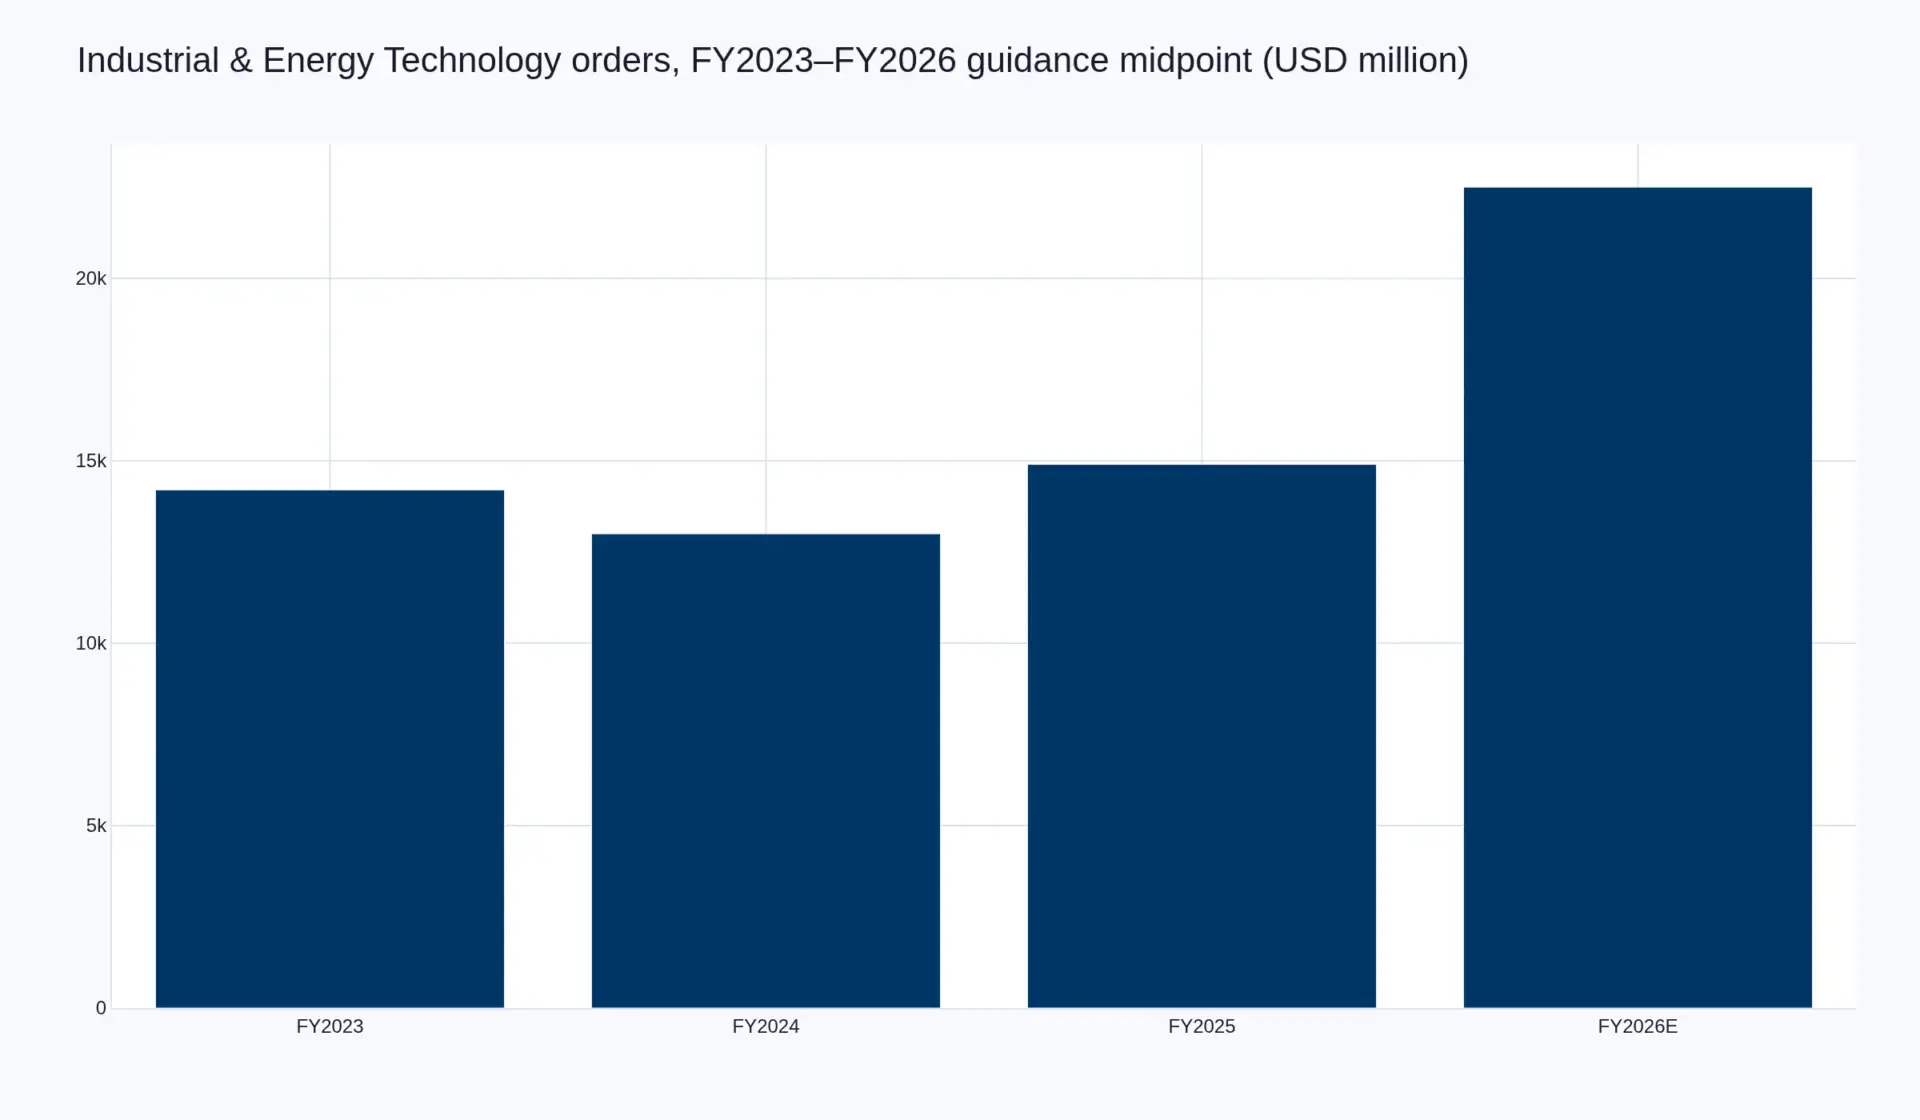
IET is where the order book sits. Segment orders reached USD 5,886 million in the third quarter of 2026, up 42 per cent year on year, taking remaining performance obligations to a record USD 46.4 billion for the company and USD 39.4 billion for IET. Management raised the full-year IET order outlook to USD 21,500–23,500 million, which at the midpoint implies a book-to-bill above 1.6x.
| Measure | Value | Period |
|---|---|---|
| Revenue | USD 27,733 million | FY2025 |
| Adjusted EBITDA | USD 4,825 million, 17.4 per cent margin (record) | FY2025 |
| Adjusted EBITDA guidance midpoint | USD 5,265 million | FY2026 |
| Remaining performance obligations | USD 46,416 million | 30 September 2026 |
Key Highlights
- Record full-year adjusted EBITDA of USD 4,825 million in FY2025, with the margin up 90 basis points to 17.4 per cent.
- Free cash flow of USD 2,732 million in FY2025, up 21 per cent year on year, on cash from operations of USD 3,810 million.
- IET segment margin reached 18.5 per cent in FY2025, a historical high and up 170 basis points; the segment delivered a record USD 14,871 million of orders.
- OFSE revenue fell 8 per cent in FY2025 to USD 14,324 million, with segment EBITDA of USD 2,618 million, a 9 per cent decline.
- Chart contributed USD 888 million of revenue and USD 156 million of segment EBITDA in the third quarter of 2026, its first partial quarter of consolidation.
- Non-LNG equipment represented approximately 85 per cent of IET orders in FY2025 — the second consecutive year at that level.
Company Overview
Business description
Baker Hughes describes itself as an energy technology company with a diversified portfolio of technologies and services across the energy and industrial value chain, built on more than a century of operating history and business in over 120 countries. Research and development spending was approximately USD 600 million in 2025, with more than 1,400 patents granted worldwide in the year.
OFSE supplies equipment and services to oil and gas operators and service companies across well construction, completions, intervention and measurement, production, and subsea and surface pressure systems. IET supplies gas technology equipment and services, industrial products and solutions, and climate technology solutions — including LNG and gas infrastructure equipment, power systems, flow and process technologies, and industrial software and instrumentation. Chart adds process technologies and equipment for gas and liquid molecule handling, with thermal management, air and gas handling, and lifecycle services exposure across gas infrastructure, nuclear, data centres, carbon capture and storage, space and geothermal end markets.
Reporting segments, FY2025
| Segment | Revenue (USD m) | Share of revenue | Segment EBITDA (USD m) | EBITDA margin | Orders (USD m) |
|---|---|---|---|---|---|
| Oilfield Services & Equipment | 14,324 | 51.6% | 2,618 | 18.3% | 14,714 |
| Industrial & Energy Technology | 13,409 | 48.4% | 2,482 | 18.5% | 14,871 |
| Total | 27,733 | 100% | 5,100 | 18.4% | 29,585 |
Total company adjusted EBITDA of USD 4,825 million differs from the USD 5,100 million of segment EBITDA because of unallocated corporate costs of USD 318 million, other income of USD 43 million, and identified items excluded from the adjusted measure. FY2025 segment revenue was flat overall but not within the segments: OFSE declined 8 per cent while IET grew 10 per cent, and the same split ran through EBITDA, with OFSE down 9 per cent and IET up 21 per cent.
Product lines, third quarter 2026
Oilfield Services & Equipment — segment revenue USD 3,660 million, up 1 per cent year on year.
| Product line | Revenue (USD m) |
|---|---|
| Well Construction | 958 |
| Completions, Intervention and Measurements | 1,008 |
| Production Solutions | 983 |
| Subsea & Surface Pressure Systems | 711 |
| Total | 3,660 |
Industrial & Energy Technology — segment revenue USD 3,477 million, up 3 per cent year on year.
| Product line | Revenue (USD m) |
|---|---|
| Gas Technology Equipment | 1,576 |
| Gas Technology Services | 897 |
| Industrial Products | 537 |
| Industrial Solutions | 205 |
| Climate Technology Solutions | 262 |
| Total | 3,477 |
Two movements inside IET are worth separating. Gas Technology Services grew 12 per cent year on year to USD 897 million while Gas Technology Equipment declined 7 per cent, and Climate Technology Solutions grew from USD 84 million to USD 262 million. Industrial Solutions fell 29 per cent, which the company attributes to the Precision Sensors & Instrumentation divestiture.
Chart Industries, consolidated from 16 July 2026
Chart reported USD 4.3 billion of revenue for its own fiscal year 2025 and serves customers in more than 50 countries. It is reported as a separate segment rather than folded into IET, and is led by senior vice president Jim Apostolides, who ran the integration programme from July 2025.
| Chart segment, Q3 2026 (from acquisition date) | Orders (USD m) | Revenue (USD m) |
|---|---|---|
| Original equipment | 587 | 623 |
| Aftermarket | 244 | 265 |
| Total | 831 | 888 |
Segment EBITDA was USD 156 million at a 17.6 per cent margin. Aftermarket revenue was 29.8 per cent of the segment’s revenue in the quarter.
Geographic and operational footprint
OFSE revenue was USD 955 million from North America and USD 2,705 million international in the third quarter of 2026, of which Middle East/Asia was USD 1,261 million. Middle East/Asia OFSE revenue fell 13 per cent year on year, which the company attributes to lower activity and to the surface pressure control disposition.
| Footprint measure | 2025 |
|---|---|
| Employees | Approximately 56,000 |
| Employees outside the United States | More than 45,000, in more than 85 countries |
| Nationalities represented | More than 150 |
| Countries where business is conducted | More than 120 |
| Research and development spend | Approximately USD 600 million |
| Patents granted worldwide | More than 1,400 |
| HSE Perfect Days | 201 |
Financial Performance
Income statement, FY2023–FY2025
| USD million | FY2023 | FY2024 | FY2025 |
|---|---|---|---|
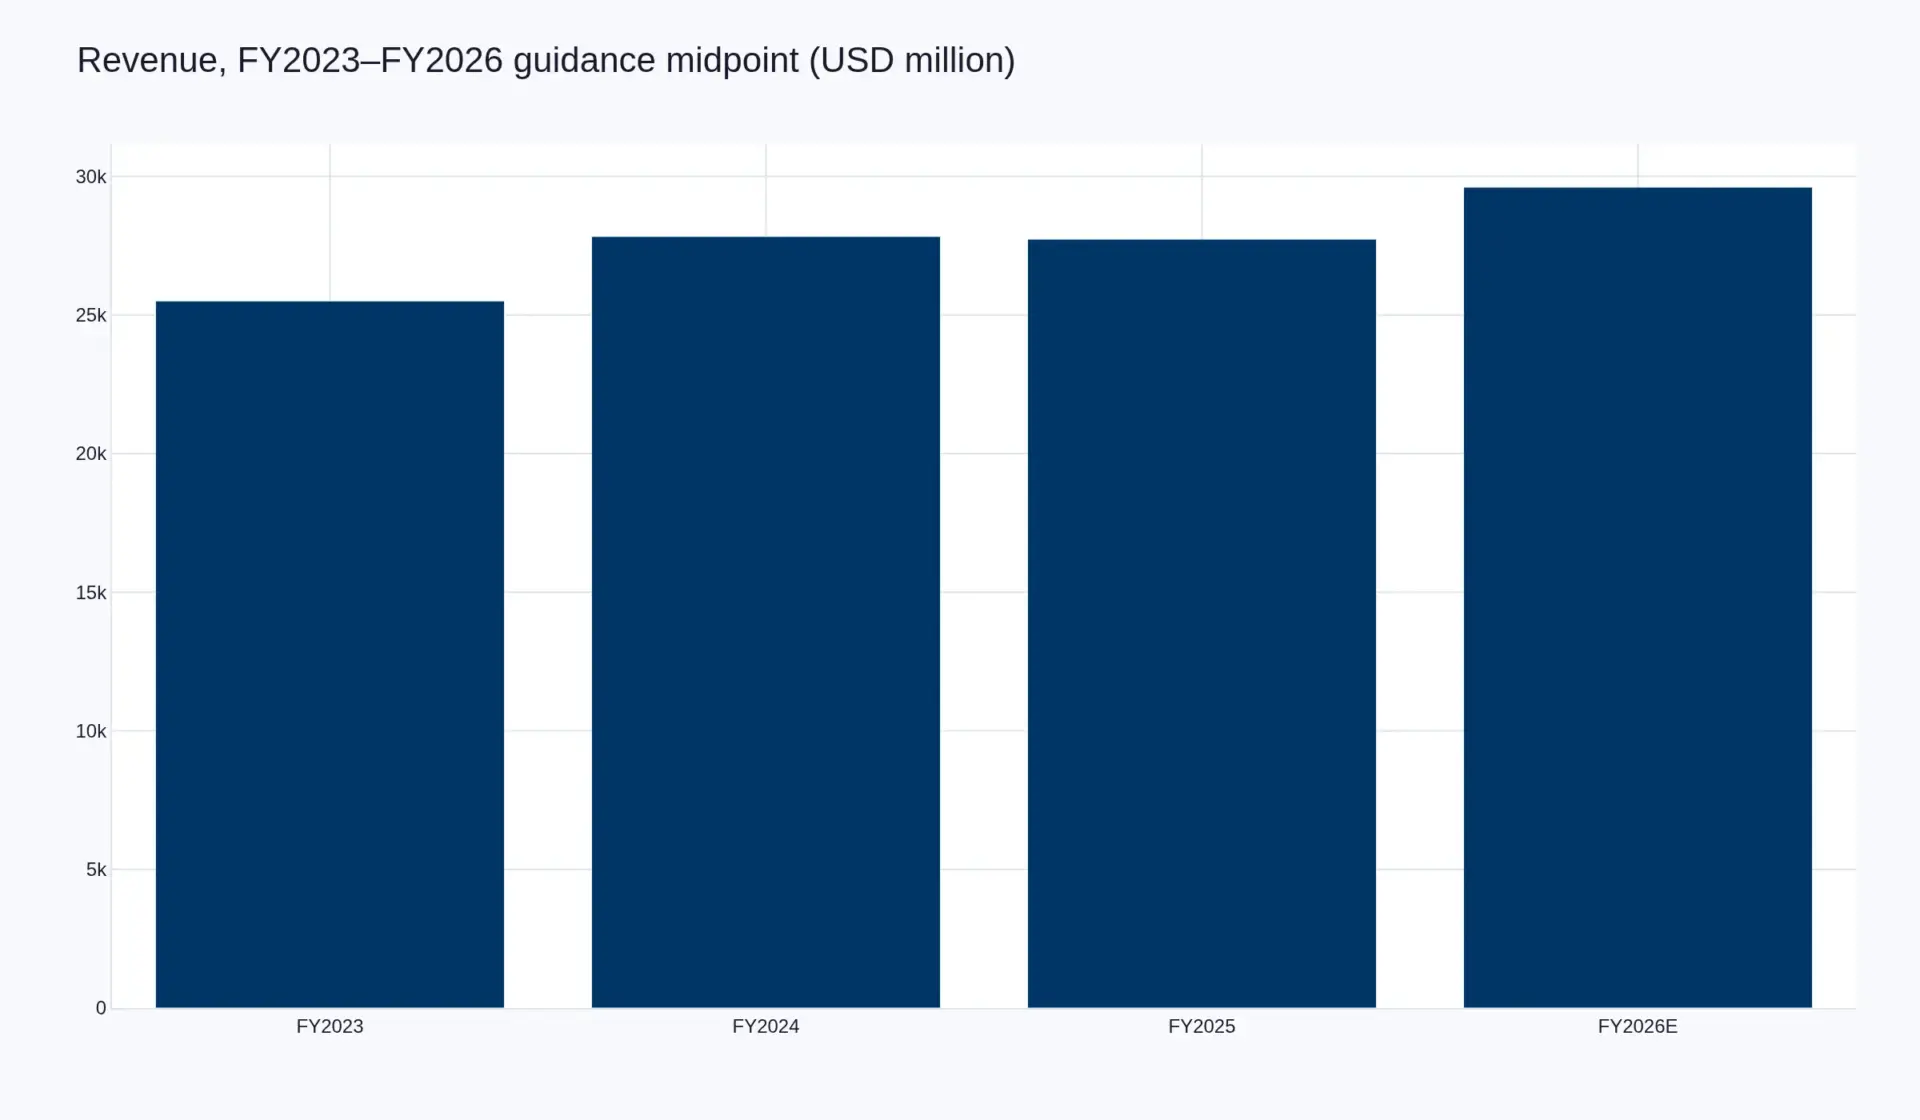
| Revenue | 25,506 | 27,829 | 27,733 |
| Cost of revenue | 19,604 | 21,346 | 21,189 |
| Research and development | 651 | 643 | 600 |
| Selling, general and administrative | 2,297 | 2,182 | 2,091 |
| OFSE segment EBITDA | 2,595 | 2,881 | 2,618 |
| IET segment EBITDA | 1,527 | 2,050 | 2,482 |
| Total segment EBITDA | 4,121 | 4,931 | 5,100 |
| Adjusted EBITDA (company definition) | — | 4,591 | 4,825 |
| Net income attributable to Baker Hughes | 1,943 | 2,979 | 2,588 |
| Diluted earnings per share (USD) | — | — | 2.60 |
| Cash from operating activities | — | — | 3,810 |
| Free cash flow | — | — | 2,732 |
The FY2025 result carries two opposing readings. Adjusted EBITDA rose 5 per cent and the margin reached a record 17.4 per cent, but net income attributable to the company fell to USD 2,588 million from USD 2,979 million, and FY2025 included USD 215 million of restructuring, a USD 22 million inventory impairment, USD 107 million of transaction costs and a USD 103 million adverse swing on the fair value of equity securities. Diluted earnings per share were USD 2.60 on both a GAAP and an adjusted basis.
2026 year to date
| USD million | Q1 2026 | Q2 2026 | Q3 2026 | Nine months 2026 |
|---|---|---|---|---|
| Orders | 8,159 | 10,501 | 10,764 | — |
| Revenue | 6,587 | 6,742 | 8,025 | 21,354 |
| Adjusted EBITDA | 1,158 | 1,231 | 1,415 | — |
| Net income attributable | 930 | 681 | 411 | 2,022 |
| Diluted earnings per share (USD) | 0.93 | 0.68 | 0.41 | 2.03 |
| Adjusted diluted earnings per share (USD) | 0.58 | 0.64 | 0.70 | — |
| Free cash flow | 210 | 1,109 | 769 | — |
Third quarter revenue of USD 8,025 million was up 14 per cent year on year and 19 per cent sequentially, with the company attributing the increase mainly to the Chart acquisition; excluding acquisitions and dispositions, revenue grew 5 per cent. The gap between GAAP and adjusted earnings per share in the quarter — USD 0.41 against USD 0.70 — reflects USD 284 million of adjusting items, including USD 158 million of transaction-related costs and a USD 25 million inventory step-up charge. Nine-month cash from operations was USD 2,850 million against capital expenditure of USD 907 million, and dividends paid were USD 684 million.
Balance sheet and leverage, 30 September 2026
| USD million | 30 September 2026 | 31 December 2025 |
|---|---|---|
| Cash and cash equivalents | 4,068 | 3,715 |
| Short-term debt | 788 | 689 |
| Long-term debt | 17,476 | 5,398 |
| Total debt | 18,264 | 6,087 |
| Net debt | 14,196 | 2,372 |
| Goodwill | 13,897 | 6,068 |
| Other intangible assets, net | 9,773 | 4,097 |
| Total assets | 59,063 | 40,881 |
| Total equity | 20,561 | 19,010 |
The balance sheet is the clearest record of what 2026 did to the company. Total debt rose from USD 6,087 million to USD 18,264 million, including USD 11,885 million of new long-term debt issued in the nine months, and goodwill plus intangibles rose from USD 10,165 million to USD 23,670 million — 40.1 per cent of total assets. Net debt of USD 14,196 million is 2.7 times the FY2026 adjusted EBITDA guidance midpoint of USD 5,265 million. The company retains a USD 3.0 billion committed revolving credit facility maturing November 2028, undrawn at 30 September 2026.
FY2026 guidance, as updated 27 October 2026
| USD million | Low | Midpoint | High |
|---|---|---|---|
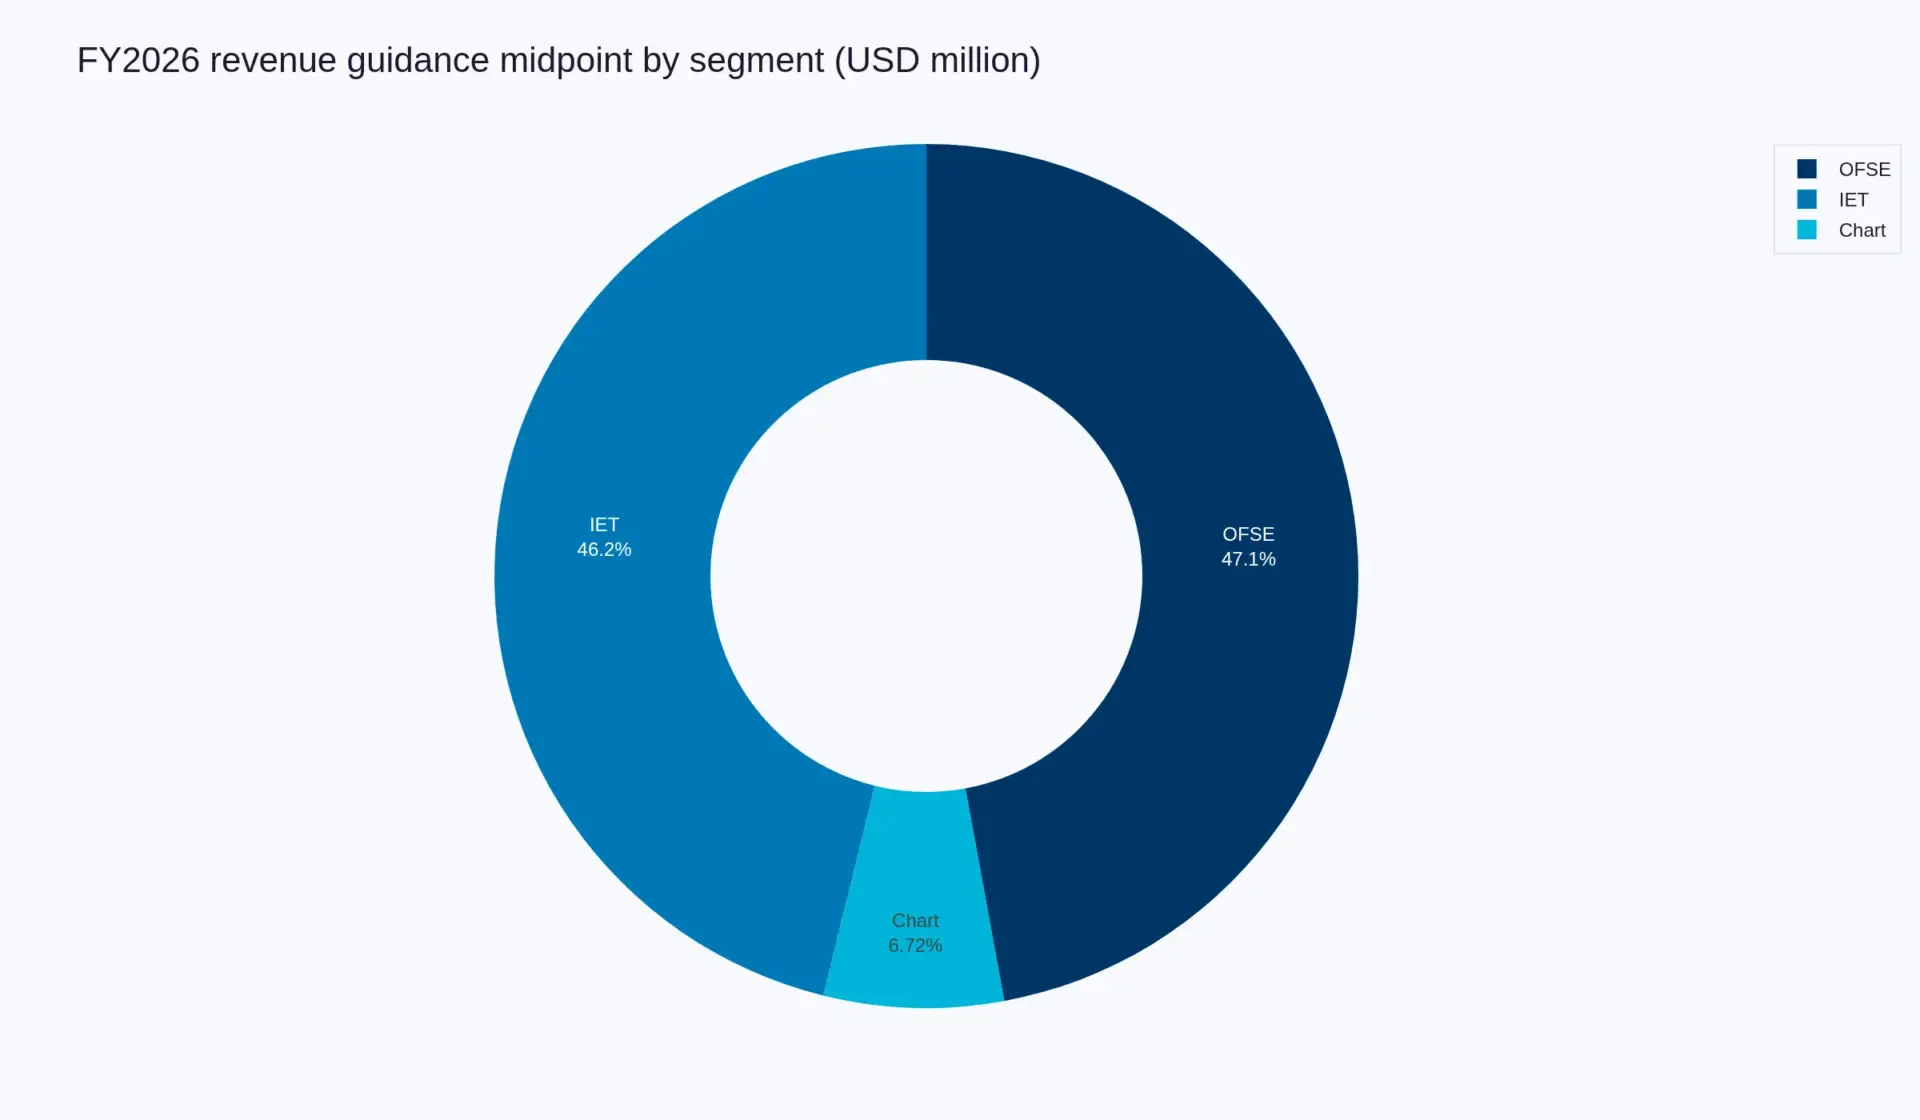
| Company revenue | 29,160 | 29,610 | 30,060 |
| Company adjusted EBITDA | 5,130 | 5,265 | 5,400 |
| OFSE revenue | 13,800 | 13,950 | 14,100 |
| OFSE EBITDA | 2,420 | 2,470 | 2,520 |
| IET revenue | 13,470 | 13,670 | 13,870 |
| IET EBITDA | 2,695 | 2,755 | 2,815 |
| Chart revenue | 1,890 | 1,990 | 2,090 |
| Chart EBITDA | 325 | 350 | 375 |
| IET orders | 21,500 | 22,500 | 23,500 |
Guidance also assumes free cash flow conversion of 45–50 per cent of adjusted EBITDA, depreciation and amortisation of approximately USD 1,415 million excluding Chart-related intangible amortisation, and an adjusted effective tax rate of 22–26 per cent. The midpoint revenue figure is 6.8 per cent above FY2025 revenue, and the midpoint adjusted EBITDA is a 7.1 per cent compound annual increase over the two years from the FY2024 figure of USD 4,591 million.
Where the figures are thin
Chart is consolidated only from 16 July 2026, so it appears in the FY2025 segment table nowhere and in the 2026 quarterly figures for a partial period only. An adjusted EBITDA figure on the company’s current definition is not presented here for FY2023 because the company formalised segment EBITDA as its segment profit measure in the first quarter of 2025; total segment EBITDA is shown for all three years instead. Revenue by product line and by geography is shown for the third quarter of 2026 only, not for the full year. The FY2026 figures above are company guidance, not reported results, and the fourth quarter of 2026 had not been reported at the date of this profile. No share price, market capitalisation or valuation multiple is presented.
SWOT Analysis
Strengths
|
Weaknesses
|
Opportunities
|
Threats
|
Recent Developments
These are discrete, dated events drawn from company releases and filings.
- 29 July 2025 — Agreement to acquire Chart Industries announced: USD 210 per share in cash, an enterprise value of USD 13.6 billion, or approximately 9x fully-synergised consensus 2025 EBITDA. Chart had reported USD 4.2 billion of revenue and USD 1.0 billion of adjusted EBITDA in 2024.
- July 2025 — Sale of the Precision Sensors & Instrumentation product line announced. The business comprised the Druck, Panametrics and Reuter-Stokes brands.
- 5 January 2026 — Sale of Precision Sensors & Instrumentation to Crane Company closed, with cash proceeds of USD 1,150 million before customary closing adjustments.
- 25 January 2026 — FY2025 results: record adjusted EBITDA of USD 4,825 million, orders of USD 29,585 million and remaining performance obligations of USD 35,900 million.
- First quarter 2026 — Joint venture with a Cactus, Inc. subsidiary closed, into which Baker Hughes contributed its surface pressure control product line, with USD 344.5 million of proceeds and a retained 35 per cent ownership stake.
- April 2026 — Sale of Waygate Technologies to Hexagon announced as an all-cash transaction of approximately USD 1.45 billion. In the same month, HMH, the minority-owned drilling equipment company, completed an initial public offering raising approximately USD 200 million.
- 16 July 2026 — Acquisition of Chart Industries completed. Chart became a third reporting segment, led by senior vice president Jim Apostolides, with an integration programme targeting USD 325 million of annualised cost synergies within three years.
- 27 October 2026 — Third quarter results: revenue of USD 8,025 million, adjusted EBITDA of USD 1,415 million, record remaining performance obligations of USD 46,416 million, IET orders of USD 5,886 million. The full-year adjusted EBITDA guidance midpoint was raised to USD 5,265 million and the IET order outlook to USD 21,500–23,500 million.
- 2 November 2026 — Sale of Waygate Technologies to Hexagon closed, with approximately USD 1.45 billion of pre-tax cash proceeds before customary closing adjustments. The business had approximately 1,500 employees across 25 locations and generated approximately USD 630 million of revenue in its fiscal 2025.
Taken together, the four portfolio actions — Precision Sensors & Instrumentation, the surface pressure control joint venture, the HMH listing and Waygate — were expected to generate approximately USD 3 billion of gross proceeds in 2026.
Business Strategy
Management frames the current period as the second horizon of a multi-year plan, with 2026 to 2028 designated Horizon 2. The stated objective is a higher-value, industrialised energy solutions company, with IET and Chart carrying growth and OFSE managed for margin and cash.
| Pillar | What it involves | The number behind it |
|---|---|---|
| IET as the growth engine | Concentrating capital and commercial effort on gas technology, power systems, climate technology and industrial solutions | 48.4 per cent of FY2025 revenue; USD 39.4 billion of IET backlog; FY2026 order outlook of USD 21,500–23,500 million |
| Active portfolio management | Exiting non-core lines and redeploying proceeds into higher-return industrial assets | Approximately USD 3 billion of gross proceeds expected in 2026 across four actions |
| Chart integration | Running Chart as a standalone third segment while harmonising platforms, engineering and lifecycle services | USD 13.6 billion enterprise value; USD 325 million of annualised cost synergies targeted within three years |
| Aftermarket and service mix | Growing recurring service and aftermarket revenue against original equipment | Gas Technology Services USD 897 million of IET’s USD 3,477 million in Q3 2026; Chart aftermarket 29.8 per cent of Chart revenue |
| Margin expansion through the Business System | Using the internal operating system to lift segment margins and convert backlog at higher profitability | Company adjusted EBITDA margin 17.4 per cent in FY2025, up 90 basis points; IET at 19.7 per cent in Q3 2026 |
| Capital returns and balance sheet | Paying a quarterly dividend and retaining buyback capacity while deleveraging after Chart | USD 0.23 per share quarterly; USD 684 million of dividends in nine months of 2026; USD 1.3 billion of repurchase authorisation remaining; net debt 2.7 times FY2026 guidance midpoint |
The single most important number in the strategy is the backlog conversion schedule. At the end of the third quarter of 2026, 33 per cent of the combined Gas Technology Equipment and Climate Technology Solutions backlog was scheduled to convert in 2027, against 46 per cent of the comparable backlog a year earlier for 2026. That is a consequence of a longer-lead-time order mix across power systems, LNG and offshore production. It improves visibility beyond 2027 and simultaneously means 2027 growth is likely to be more modest than 2026.
Coverage context: non-destructive testing
Baker Hughes appears in Pheonix Research’s non-destructive testing coverage through Waygate Technologies, whose inspection portfolio — industrial radiography, computed tomography, remote visual inspection and ultrasonic testing — sat inside the Industrial & Energy Technology segment. The sale of Waygate to Hexagon closed on 2 November 2026, so that participation now sits with Hexagon. This profile is retained as the record of the vendor group up to that date, and the Baker Hughes portfolio described above excludes Waygate from the point of close.
Sources
- Baker Hughes, Fourth-Quarter and Full-Year 2025 Results, 25 January 2026.
- Baker Hughes, Form 10-K for the year ended 31 December 2025, filed 5 February 2026.
- Baker Hughes, 2025 Annual Report.
- Baker Hughes, First-Quarter 2026 Results, 23 April 2026.
- Baker Hughes, Third-Quarter 2026 Results, 27 October 2026.
- Baker Hughes, Form 10-Q for the quarter ended 30 September 2026, filed 28 October 2026.
- Baker Hughes, Third Quarter 2026 earnings presentation and prepared remarks, 27–28 October 2026.
- Baker Hughes, agreement to acquire Chart Industries, 29 July 2025; and completion of the Chart acquisition, 16 July 2026.
- Baker Hughes, closing of the Precision Sensors & Instrumentation sale, 5 January 2026.
- Baker Hughes, closing of the Waygate Technologies sale, 2 November 2026; and Hexagon, completion of the Waygate acquisition, 2 November 2026.
- Wikidata, Q804353.
Provenance. This profile is bound to Wikidata Q804353 and to Pheonix entity MIEN-node_d804aab1. All financial and structural figures were verified against the primary filings and company releases listed above on 18 November 2026. The Wikidata item carries the BKR ticker statement at preferred rank, referencing the 2019 name change, and retains the earlier listing statements for BHI (to June 2017) and BHGE (2017–2019); it records the BKR line against the New York Stock Exchange, whereas Baker Hughes’ own filings and releases state Nasdaq: BKR, and this profile follows the company’s own disclosure.
Market Presence
Baker Hughes Company is mentioned across 1 market report.
