
Editorial Article
One Point Two Six Million Tonnes and a Price That Cannot Move
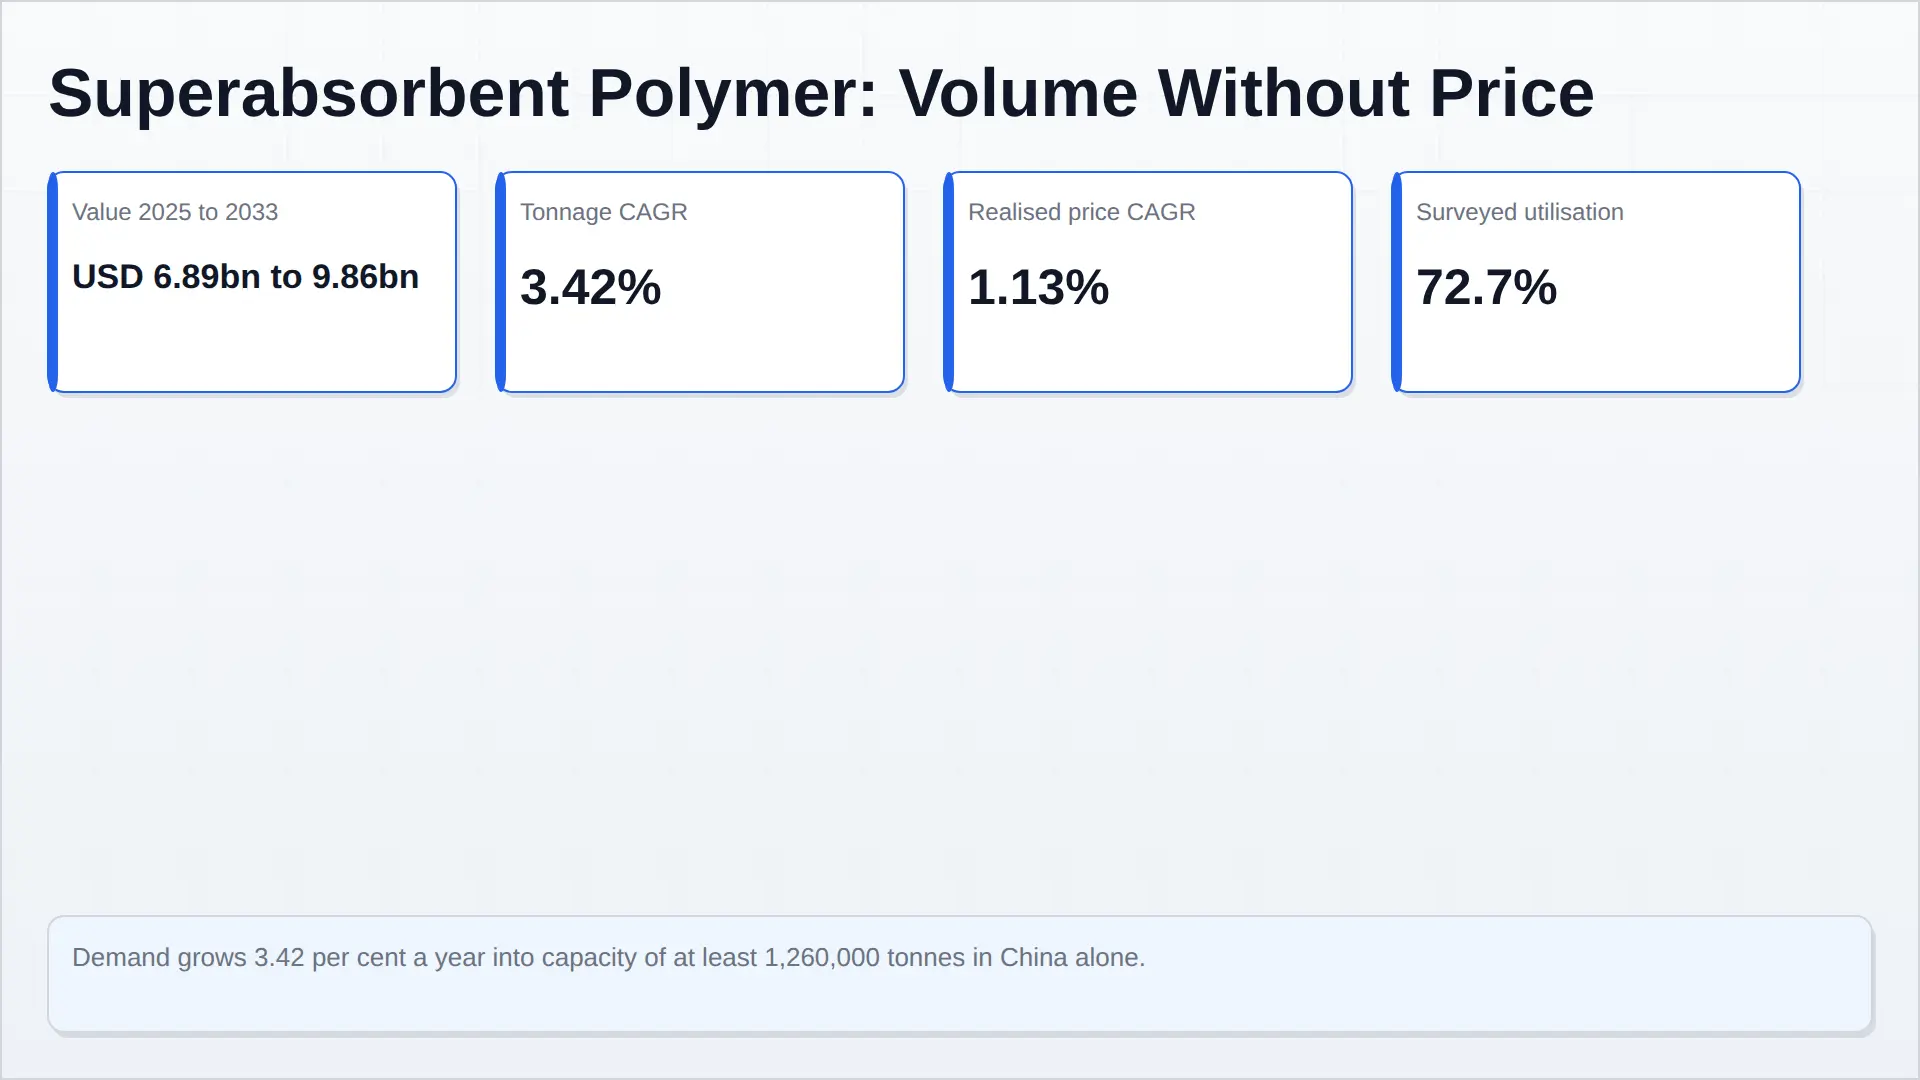
The global superabsorbent polymer market is modelled at USD 6.89 billion in 2025 rising to USD 9.86 billion in 2033, 4.59 per cent a year. Volume rises from 4,050 to 5,300 thousand tonnes — 3.42 per cent. Realised price rises from USD 1,700 to USD 1,860 a tonne: 1.13 per cent a year, the slowest price line of any node in the absorbent hygiene chain.
That gap is the whole story of this material. Tonnage grows at 2.59 times the rate of price, and price accounts for only 28.5 per cent of the USD 2.97 billion the market adds by 2033. This is the polymer that the absorbent core has been substituting towards for thirty years — the material that made the thinner diaper possible — and it is the one node in the chain that cannot charge for what it enables.
The marginal tonne is Chinese
Chinese capacity stands at a minimum of 1,260,000 tonnes a year, built for a domestic market that did not arrive at the rate it was built for. The industry’s response has been to export it. Dansonpack Industries has raised its export ratio to 70 per cent of output; Satellite Science & Technology to 40 per cent; the broader body of Chinese and Korean producers runs 15 to 30 per cent.
Once a marginal producer can export at seventy per cent of output, the question a buyer asks stops being who makes the best polymer and becomes who will quote the lowest price this quarter. That is not a market failure. It is a market working exactly as a surplus works, and it sets the terms for everyone else in it.
The top of the curve is concentrated and still cannot price
Nippon Shokubai is the largest producer: 710,000 tonnes a year of superabsorbent polymer capacity across Himeji, Antwerp, Zhangjiagang, Jurong Island, Cilegon and Houston — 17.2 per cent of surveyed global capacity — sitting on 980,000 tonnes a year of acrylic acid. A trade census of eleven producers put capacity at 4,126,000 tonnes a year against world demand of around three million tonnes, at 72.7 per cent utilisation.
A 17.2 per cent share would be decisive in most specialty chemicals. Here it means nothing on price, because a share measures the ability to supply and price is set by the ability not to supply. Capacity discipline at the top of the curve — the trade survey records the majors’ capacity as materially unchanged between 2019 and 2020 — does not offset a surplus at the bottom.
Integration is the only durable defence. Nippon Shokubai’s 980,000 tonnes of acrylic acid is more monomer than its 710,000 tonnes of polymer requires, which makes it a net seller of feedstock. A producer buying acrylic acid at a propylene-linked price and selling polymer into a surplus has that spread as its entire business, and every point the monomer rises without a matching polymer increase is taken straight out of its margin.
The consolidation that never closed
The trade record shows a planned combination of Nippon Shokubai’s and Sanyo Chemical’s superabsorbent businesses — Sanyo Chemical being the parent of SDP Global — intended to build scale against exactly this price competition. It had not been finalised at the time of the survey, with the stated reason being the economic environment.
Read that as a strategic statement rather than an administrative one. Two of the largest Japanese producers concluded they needed to merge in order to compete on price with capacity that was not going to close — and did not complete the merger.
Why nobody exits
A superabsorbent plant is a capital asset with a long life and low variable cost once built. In a surplus, the rational behaviour for each owner is to run and take share, because the alternative is to write the asset off. That mechanism holds utilisation at 72.7 per cent and price growth at 1.13 per cent, and it is self-reinforcing: the owner who exits gifts the remaining volume to competitors who did not.
It is also why the report does not forecast a price recovery. Recovery requires closures. Closures require someone to accept the write-off.
A contract market, not a traded one
Polymer is bought on quarterly or annual contracts against a volume forecast, and converters hold weeks of stock. Because price has been flat to gently rising for a decade, there is little incentive on either side to hedge, and the exposure sits as an unmatched quarterly negotiation rather than as a traded risk.
That is why the price line in the forecast is smooth. It is not a modelling convenience; it describes a contract market with structural surplus. A commodity with volatility gets a different curve, because volatility is what creates the incentive to trade it.
What would change the answer
Closures are the first. If Chinese capacity rationalises — through consolidation, environmental enforcement or simply exit at the margin — the spread between volume growth and price growth narrows fast, because it is a pure surplus phenomenon.
A bio-based premium is the second. Regulatory instruments aimed at bio-based feedstock create a genuinely differentiated grade, and differentiated grades price differently from commodity ones. The report covers the regulatory position; whether it creates a durable premium is a different question, and an open one.
Demand composition is the third. Polymer intensity per unit has been rising as fibre comes out of the core, and that is what drives the 3.42 per cent. If the fluff-reduction programmes reach their specification limits, the volume line slows and the price line has even less room.
How this was researched
Seventy per cent secondary, thirty per cent primary. Capacity and integration data come from producer disclosure — Nippon Shokubai’s integrated report, with 710,000 tonnes a year of superabsorbent polymer capacity, 980,000 tonnes of acrylic acid and site-level capacity across six countries — and from trade-press survey data covering eleven producers at 4,126,000 tonnes a year. The primary programme comprises structured interviews with absorbent-material suppliers and converter procurement teams, open-ended interviews with core-design engineers, technical and commercial conversations at the nonwovens trade shows, and a converter survey on specification authority and substitution decisions. Per-unit intensities are taken from the companion reports in this cluster. No market-research competitor data is used or cited.
Read next
- The substituting material reprices slower than the material it replaces — why the swap continues anyway.
- Global Fluff Pulp Market — the input on the other side of the substitution.
- Global Adult Incontinence Products Market — the end use with the highest polymer intensity.
Frequently Asked Questions
How big is the global superabsorbent polymer market?
USD 6.89 billion in 2025 rising to USD 9.86 billion in 2033, a 4.59 per cent CAGR, on volume rising from 4,050 to 5,300 thousand tonnes at 3.42 per cent a year.
Why can the largest producers not raise price?
Chinese capacity of at least 1,260,000 tonnes a year was built for a domestic market that did not arrive, and producers have raised export ratios as high as 70 per cent. The marginal tonne is therefore set by exported surplus, not by the cost of a European or Japanese plant.
What is capacity utilisation in superabsorbent polymer?
A trade census of eleven producers puts capacity at 4,126,000 tonnes a year against world demand of around three million tonnes, with utilisation at 72.7 per cent.
What would change the price outlook?
Closures first, because the volume-to-price gap is a pure surplus phenomenon. A bio-based premium is the second, if regulation creates a genuinely differentiated grade. Slowing polymer intensity would be the third, and it cuts the other way.