
India Programmatic Advertising Market Report, Size, Share and Forecast 2026–2033: A Billion Connected Indians, ₹292 Each — Growth Turns From Volume to Yield
India's programmatic advertising market was worth ₹30,081 crore in 2025, or USD 3,458 million at ₹87.0 to the dollar, and grew 19% that year. It reaches ₹81,441 crore by 2033 on the base case — a 13.26% CAGR in rupees and, under constant-rate conversion, the same in dollars. Conservative and optimistic paths bracket that at ₹73,056 crore (11.7%) and ₹90,612 crore (14.8%).
The headline rate is the least interesting thing about it. Three structural facts define this market, and each contradicts the way it is usually described.
Programmatic is not taking share inside Indian digital advertising. It was 42.0% of India's digital media spend in 2025 and is projected at 43.3% in 2027 — a 1.3-point move across two years in which digital advertising itself rises from 59% to 70% of the country's total ad market. Programmatic is growing at almost precisely the rate of the market that contains it. The fastest-growing slice of Indian digital, e-retail advertising, expanded 55.86% to ₹17,601 crore, and it is sold inside marketplace walled gardens rather than on an open exchange. That is the mechanism holding the share flat.
The revenue per connected Indian is derisory. Against TRAI's 1,028.61 million internet subscribers at December 2025, programmatic advertising generates ₹292.44 per subscriber per year — ₹24.37 a month, or 12.5% of the ₹194.57 monthly ARPU their telecom operator charges for the connection itself. Even at 2033's projected market value on today's subscriber base, advertising reaches only 33.9% of telecom ARPU. The domestic pool is too thin to fund the technology that serves it, which is why Indian adtech companies are structurally export businesses.
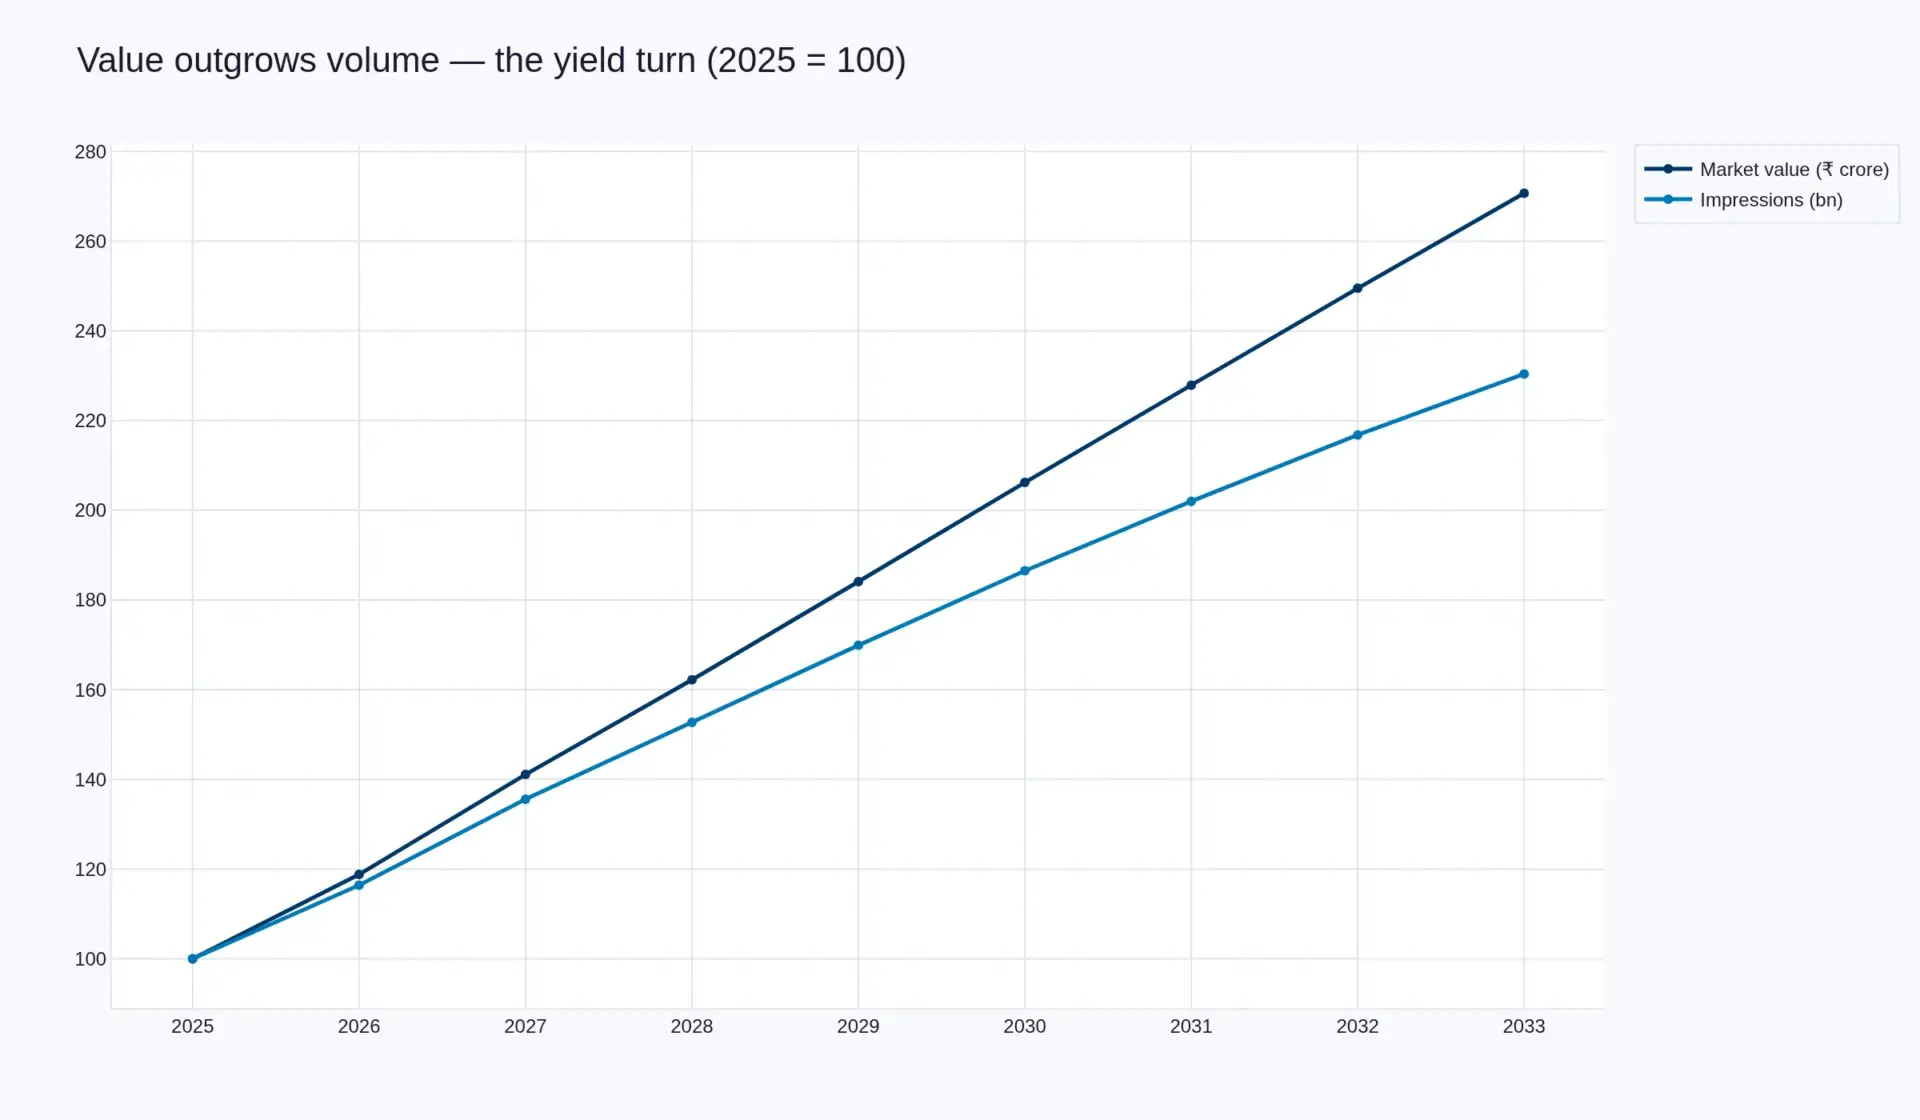
The next leg is yield, not volume. From 2025 to 2033 impressions grow 130% (5,469 billion to 12,603 billion) while value grows 171% (₹30,081 crore to ₹81,441 crore). Value outgrows volume and the difference is price: a blended eCPM of ₹55.00 rising to ₹64.62, a 2.03% annual gain driven by mix shifting toward connected TV (₹400–800 CPM) and premium video (₹180–450) and away from mobile display, where FMCG and mid-market retail rates fell 8–12% in 2025. Connected TV advertising grew 42% to ₹9,900 crore while linear TV advertising fell to ₹26,300 crore — a clean substitution from a cheap impression to an expensive one.
And there is a date. India's Digital Personal Data Protection Rules were notified on 13 November 2025 as G.S.R. 843(E). The operative obligations — notice, consent, purpose limitation, data-principal rights, the data fiduciary's duties — commence on 13 May 2027, eighteen months later, inside this forecast window. The consent-manager registration framework came live at twelve months, on 13 November 2026. Because India is a mobile-application market (983.29 million wireless against 45.32 million wired internet subscribers), third-party cookies were never the identifier that mattered here; the mobile advertising ID is, and the consent duty will land directly on it.
The market is oligopolistic at the top and crowded below it. Eight firms set terms — Google, Meta Platforms, Amazon, Flipkart, Jio Platforms, JioStar, InMobi and The Trade Desk — with Magnite and Vertoz representing the independent supply and demand layers beneath them. A Competition Commission of India investigation ordered on 8 January 2025 into Google's ad-tech intermediation (Case No. 34 of 2024) is pending and unadjudicated; it is an investigation order, not a finding.
The principal analytical caution: two credible Indian bodies measured the same 2025 market and disagreed by ₹21,535 crore on its size. Pitch Madison's expanded definition puts digital at ₹93,156 crore against dentsu-e4m's ₹71,621 crore. On the expanded base, the ₹30,081 crore programmatic figure would be a 32.3% share, not 42.0%. The growth argument survives either base; the absolute level does not. Both sources put digital at 59–60% of total advertising.
India Programmatic Advertising Market Overview
India's programmatic advertising market was worth ₹30,081 crore in 2025 — about USD 3.46 billion — and it grew 19% that year. On the headline alone it reads as a market in a hurry. It is not. It is a market that has spent a decade growing by serving more impressions, and is now entering the first phase of its life in which the growth has to come from somewhere else.
Three facts sit underneath that rate, and none of them is visible from it. The first is that programmatic's share of Indian digital advertising is stuck: 42.0% in 2025, 43.3% projected for 2027. It is not taking share from the rest of digital; it is riding digital's growth and no more. The second is that the billion-odd Indians now connected generate ₹292 of programmatic revenue each per year — about an eighth of what their telecom operator charges them for the connection. The third is a date: 13 May 2027, when the consent obligations at the centre of India's data protection framework commence, and with them the first statutory constraint on how Indian programmatic identifies and targets anybody.
The market, on the only published base that measures it
No Indian statistical agency produces a programmatic advertising number. The figure this report uses — ₹30,081 crore for 2025 — is the dentsu-e4m Digital Advertising Report 2026 estimate of programmatic's share of Indian digital media spend. It is the only published figure that states both a level and a definition, which is why it anchors the model here rather than a constructed bottom-up figure.
Read in its own context, it describes a market growing roughly in line with the digital advertising that contains it:
| ₹ crore | 2024 | 2025 | 2026F | 2027F |
|---|---|---|---|---|
| Total Indian advertising | — | 1,21,339 | 1,30,416 | 1,40,001 |
| Digital media | 60,186* | 71,621 | 84,977 | 98,034 |
| of which programmatic | 25,278* | 30,081 | 35,727* | 42,435 |
| of which e-retail advertising | 11,293* | 17,601 | — | — |
| Programmatic as % of digital | 42.0% | 42.0% | 42.0% | 43.3% |
| Digital as % of total advertising | — | 59.0% | 65.2% | 70.0% |
Source: dentsu-e4m Digital Advertising Report 2026, published February 2026. *Derived by Pheonix from the stated growth rates (digital +19% in 2025, programmatic +19% in 2025, programmatic 18.77% CAGR to 2027, e-retail +55.86% in 2025). Percentages derived from the stated levels.
The share that does not move
This is the single most important number in the report, and it is a number that does not change. Programmatic was 42.0% of Indian digital media spend in 2025. It is projected at 43.3% in 2027. Over the same two years, digital advertising rises from 59% of the country's total ad market to 70%.
So the engine of Indian advertising's shift to digital is not programmatic. Programmatic is growing at almost exactly the rate of the digital market that contains it. Everything else in digital — sponsored listings inside marketplaces, direct deals, influencer, branded content, search — is growing at least as fast. In a market where programmatic is 85–90% of digital display, a 42% share would be an anomaly. India's array of non-programmatic digital inventory is not a rounding error; it is the majority.
And the reason is visible in the one line that did move fastest. E-retail advertising grew 55.86% in 2025 to ₹17,601 crore — 24.6% of all Indian digital media spend, in a single sub-segment, at three times the growth rate of the market around it. That inventory is sold inside Flipkart, Amazon and the quick-commerce apps. It is auctioned, it is data-driven, and it is, in the loosest sense, programmatic. But it is not bought on an open exchange, and the platform that owns the shopper owns the auction, the identity and the price.
₹292 per connected Indian
India had 1,028.61 million internet subscribers at the end of December 2025, against 1,017.81 million three months earlier, according to TRAI's quarterly performance indicator report. Set the programmatic market against that base and the arithmetic is uncomfortable:
| Per internet subscriber | 2025 | 2033F |
|---|---|---|
| Programmatic advertising revenue, per year | ₹292.44 | ₹791.76 |
| Programmatic advertising revenue, per month | ₹24.37 | ₹65.98 |
| Telecom operator ARPU, per month | ₹194.57 | ₹194.57 |
| Advertising as % of telecom ARPU | 12.5% | 33.9% |
Subscriber base: TRAI Press Release No. 32/2026, quarter ended 31 December 2025. Wireless ARPU ₹194.57/month. The 2033 column holds the subscriber base and ARPU constant at December 2025 levels deliberately — it is a scale test, not a forecast of either.
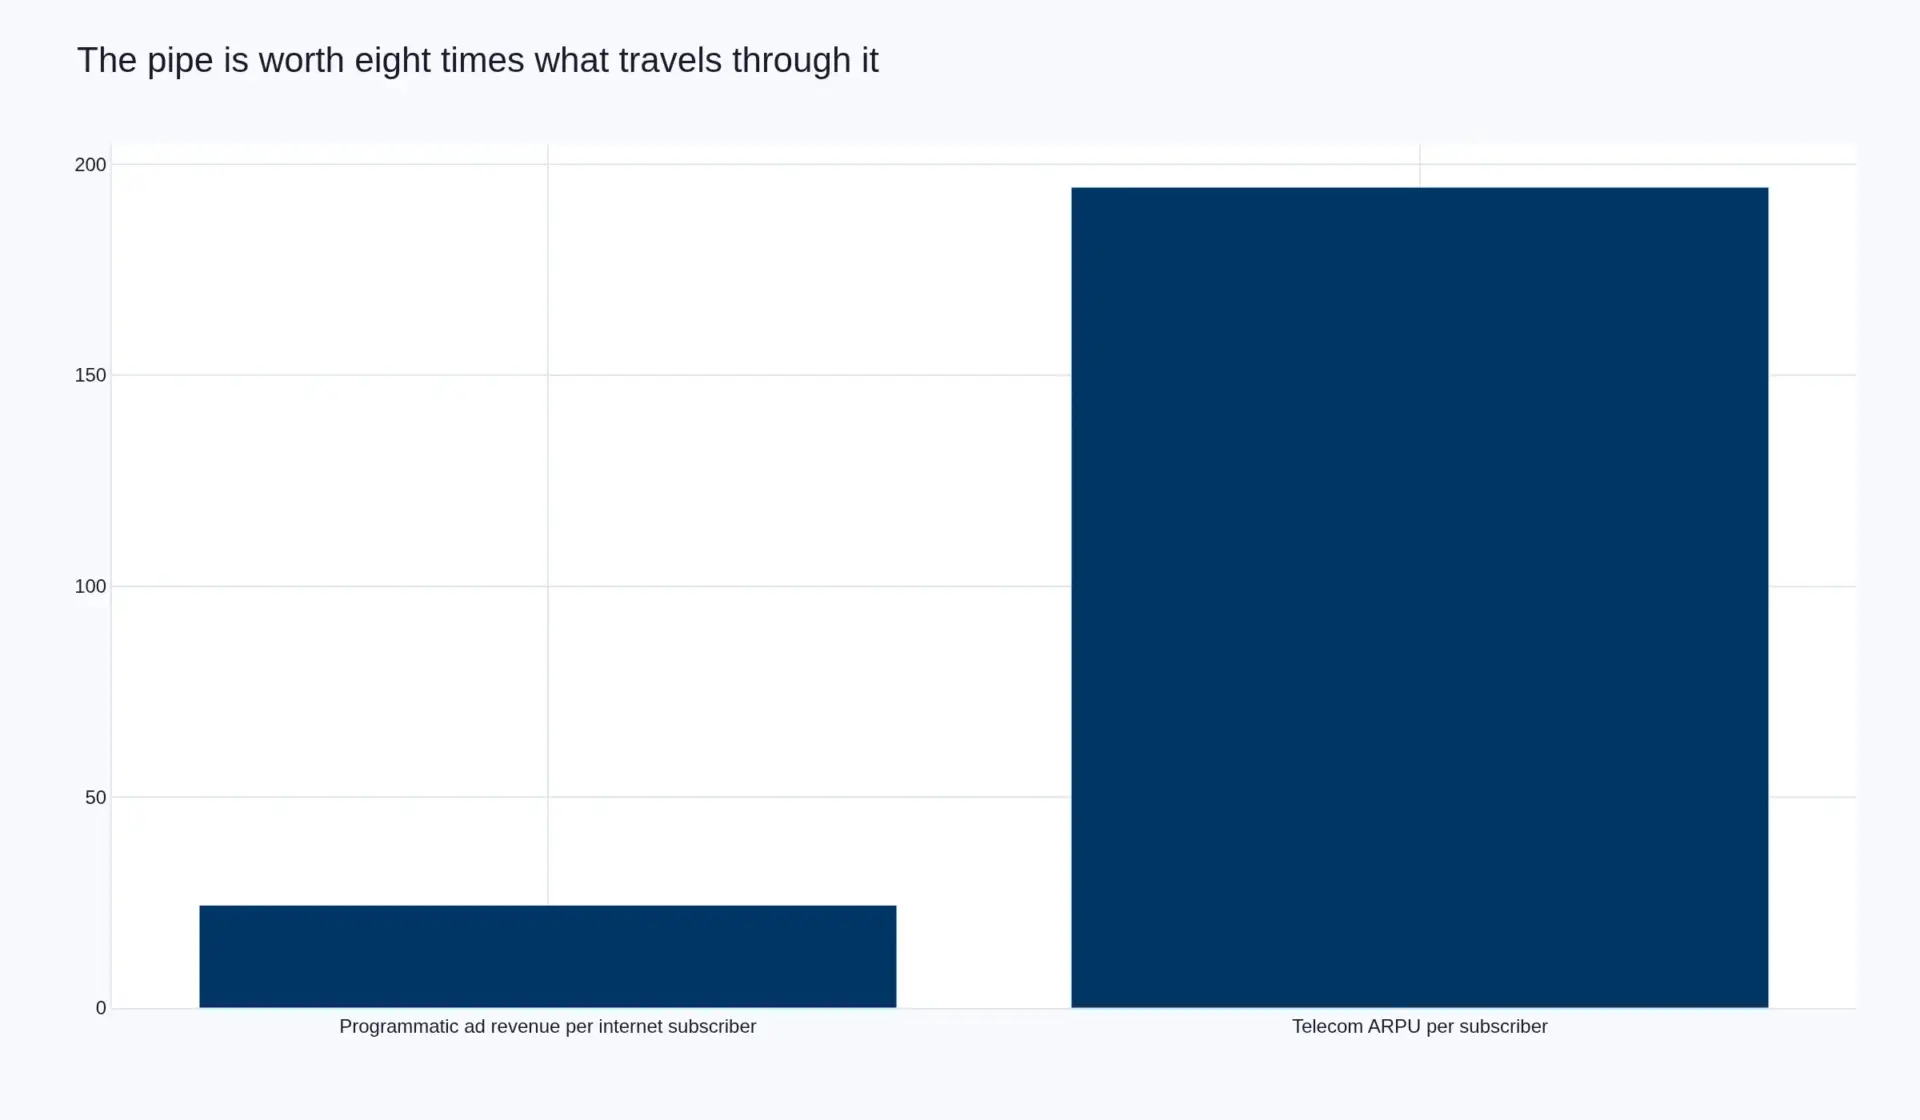
An Indian pays their telecom operator ₹194.57 a month for the connection through which every one of those impressions is served, and generates ₹24.37 a month of programmatic advertising revenue in the process. The pipe is worth eight times what travels through it. Even at 2033's projected market value, on today's subscriber base, advertising would reach only a third of what connectivity already extracts.
That gap is the reason Indian adtech companies are export businesses. The domestic pool is too thin to fund the technology that serves it, so the capital has to come from markets where an impression is worth more. It also explains the shape of the market's competitive structure: the firms that keep the most value are the ones that own the user relationship — the telco, the marketplace, the operating system — not the ones that own the auction.
From volume to yield
For most of the last decade Indian programmatic grew by serving more impressions to a rapidly expanding audience, at prices that were among the lowest in the world. That phase is ending, and the arithmetic of the next one inverts.
Between 2025 and 2033, impressions served grow 130%, from roughly 5,469 billion to 12,603 billion. Market value grows 171%, from ₹30,081 crore to ₹81,441 crore. Value therefore outgrows volume, and the difference is price. On the blended effective CPM assumed in this model — ₹55.00 per thousand impressions in 2025 — the mix shift to higher-yielding inventory carries the blended rate to ₹64.62 by 2033, a 2.0% annual increase.
| Year | Value ₹ crore | Value USD m | Impressions bn | Blended eCPM ₹ |
|---|---|---|---|---|
| 2025 | 30,081 | 3,458 | 5,469 | 55.00 |
| 2026 | 35,727 | 4,107 | 6,366 | 56.12 |
| 2027 | 42,435 | 4,878 | 7,413 | 57.26 |
| 2028 | 48,800 | 5,609 | 8,353 | 58.42 |
| 2029 | 55,388 | 6,366 | 9,292 | 59.61 |
| 2030 | 62,035 | 7,131 | 10,200 | 60.82 |
| 2031 | 68,549 | 7,879 | 11,047 | 62.05 |
| 2032 | 75,061 | 8,628 | 11,856 | 63.31 |
| 2033 | 81,441 | 9,361 | 12,603 | 64.62 |
| CAGR 2025–33 | 13.26% | 13.26% | 11.00% | 2.03% |
Pheonix model. 2025 and 2027 anchored to dentsu-e4m; 2026 interpolated at the stated 18.77% CAGR. 2028–2033 is a Pheonix projection: growth decelerates from 15.0% to 8.5% as the digital base approaches the 70%-of-advertising ceiling it reaches in 2027. USD at a constant ₹87.0. Impressions and eCPM are modelled, not reported — see methodology.
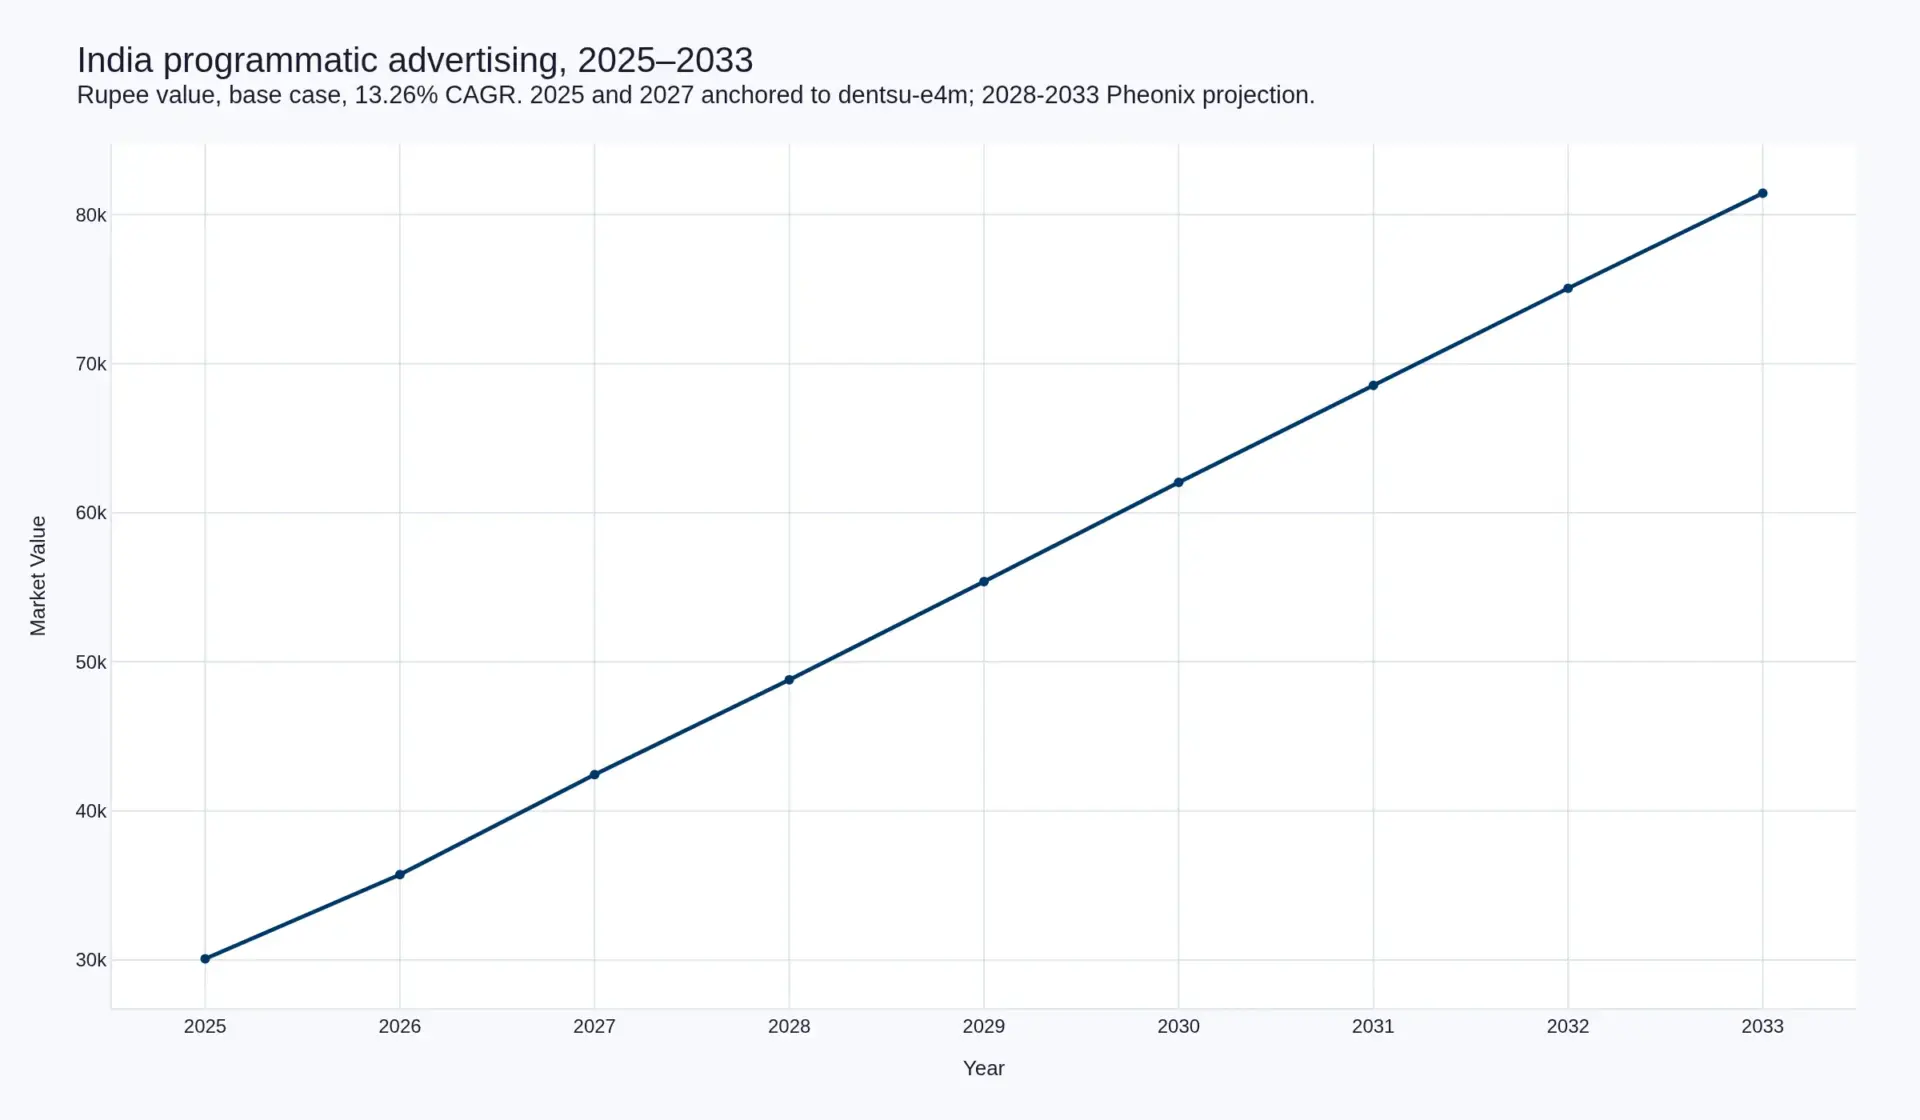
The three scenarios that bracket this path are worth stating plainly, because the terminal rate is the whole argument. On the base case the market reaches ₹81,441 crore in 2033 at a 13.3% CAGR. If yield does not materialise and programmatic simply tracks digital's own deceleration, growth runs two points lower each year and the market reaches ₹73,056 crore — an 11.7% CAGR. If retail media and CTV open up to third-party buying, it runs two points higher and reaches ₹90,612 crore — 14.8%.
Yield, not volume, because the price floor is real
India's impression prices are set by a structure that will not move quickly. Published benchmarks put mobile display at roughly ₹120–180 per thousand impressions and premium programmatic at ₹200–400 — but those are premium rates. The same trade reporting is explicit that remnant inventory "trades at significant discounts", and that the market has split in two: premium inventory in finance, luxury and technology rose 10–15% during 2025, while FMCG and mid-market retail CPMs fell 8–12%.
| Format | India CPM, ₹ | Direction in 2025 |
|---|---|---|
| Connected TV | 400–800 | Held; live sport commands a premium |
| Mobile video | 180–450 | Held |
| Premium programmatic | 200–400 | +10–15% in finance, luxury, tech |
| Social feed | 180–300 | Mixed |
| Mobile display | 120–180 | −8–12% in FMCG and mid-market retail |
| Desktop display | 80–140 | Soft |
| Remnant / open exchange | Not publicly benchmarked | Discount to all of the above |
Source: exchange4media, 6 May 2025, citing CPM benchmarks supplied by a senior marketer. Premium inventory in financial and sports content and in certain in-app environments commands 2–3× these averages.
This is why the blended eCPM in this model is ₹55 rather than the ₹120 floor of the table above. A blended figure has to absorb the open exchange, where most Indian impression volume actually clears, and that inventory is priced far below the premium benchmarks that get quoted. ₹55 sits at roughly a third of premium mobile display and several multiples above remnant. No published source measures a blended India programmatic eCPM; this one is an assumption, disclosed as such.
The mechanism that lifts it is mix, and the clearest evidence of the mix shift is in television. FICCI-EY's 2026 media and entertainment report records connected TV advertising revenue growing 42% to ₹9,900 crore in 2025, against linear TV advertising revenue falling to ₹26,300 crore. Combined linear and connected TV advertising held flat at ₹36,200 crore. Read that pair together and the substitution is exact: a rupee leaving a ₹100–200 linear impression and arriving at a ₹400–800 connected one raises the blended yield of the market it lands in without requiring any impression to be created at all. That is what "yield, not volume" means in practice, and it is why the forecast's 2.0% annual eCPM gain is a mix effect rather than a pricing-power claim.
13 May 2027
India's Digital Personal Data Protection Rules were notified in the Gazette on 13 November 2025 as G.S.R. 843(E). They do not commence all at once, and the staggered schedule is the most consequential thing in this report that is not a market number.
| Commencement | Provisions | What it means for programmatic |
|---|---|---|
| 13 Nov 2025 on notification | ss.1(2), 2, 18–26, 35, 38–43, s.44(1) and (3) | The Data Protection Board is constituted and empowered. Regulator exists before the rules that bind you do. |
| 13 Nov 2026 twelve months | s.6(9); s.27(1)(d) | The consent-manager registration framework. Registration is open; the consent duty itself is not yet live. |
| 13 May 2027 eighteen months | ss.3–5, s.6(1)–(8) and (10), ss.7–10, ss.11–17, s.27 except (1)(d), ss.28–34, 36, 37, s.44(2) | Notice, consent, purpose limitation, data-principal rights, and the data fiduciary's obligations all begin. This is the operative date. |
Source: Digital Personal Data Protection Rules, 2025, G.S.R. 843(E), Gazette of India, 13 November 2025, rule 1(2).
The date matters to this market more than to most, because of what Indian programmatic actually runs on. India is a mobile-application market: TRAI counted 983.29 million wireless internet subscribers against 45.32 million wired ones. Third-party cookies, the substrate of every Western privacy argument of the last five years, are close to irrelevant here because so little Indian inventory is served in a browser. What identifies a user is the mobile advertising identifier — the Google Advertising ID on Android, the IDFA on iOS — and both of those sit behind a device-level consent flow that the platform, not the advertiser, controls.
So the Indian consent shock does not arrive through a browser deprecation. It arrives through statute, on a fixed date, in eighteen months, and it lands on the one identifier the market actually uses. What changes is not whether you can target; it is whether the purpose for which you hold the identifier was ever validly consented to, and who bears the liability if it was not. That obligation sits with the data fiduciary, and in a chain that runs advertiser → agency → DSP → exchange → SSP → publisher, the fiduciary question is, in most Indian buys today, unanswered.
A separate competition proceeding runs alongside it. On 8 January 2025 the Competition Commission of India ordered a Director General investigation into Google's ad-tech intermediation services in Case No. 34 of 2024, on a prima facie view covering the tying of DoubleClick for Publishers with AdX inside Google Ad Manager, Google's dual role in Open Bidding as both auction host and bidder, and the Unified Pricing Rule operating as a de facto price-parity clause. This is an investigation order under Section 26(1), not a finding of abuse — the conduct has not been adjudicated. But it places the mechanics of Indian supply-path pricing on a formal record, and the outcome will determine whether the 42% in this report is a market outcome or an artefact of one firm's auction design.
The definitional trap you should know about
Two credible Indian industry bodies measured the 2025 advertising market this year and produced numbers that differ by a third. It is worth understanding why, because the choice of base changes the headline enormously.
| 2025, ₹ crore | dentsu-e4m | Pitch Madison PMAR 2026 |
|---|---|---|
| Total advertising (ADEX) | 1,21,339 | 1,55,105 |
| Digital advertising | 71,621 | 93,156 |
| Digital as % of ADEX | 59.0% | 60.0% |
| Programmatic, if 42% of digital | 30,081 | 39,125 |
| Programmatic share of that digital base | 42.0% | 32.3% |
Pitch Madison PMAR 2026 measures on an expanded definition that includes quick-commerce and MSME digital spend. dentsu-e4m does not. Both put digital at 59–60% of total advertising — the structural conclusion is identical; the absolute base is not.
The two sources agree completely on the shape of Indian advertising and disagree by ₹21,535 crore on its size. This report uses dentsu-e4m because it is the only one of the two that publishes a programmatic line with a stated method. But you should hold the ₹30,081 crore figure loosely in one specific sense: if the expanded base is correct, the true programmatic pool is nearer ₹39,000 crore, and the 42% share is really 32%. Nothing in this report's growth argument depends on which is right. The absolute level does.
What to watch
Four signals would move this market off the path above, and each is observable before the market reports it.
Retail media's gate. If Flipkart, Amazon or the quick-commerce platforms open their inventory to third-party demand-side platforms — rather than keeping it inside a closed auction — the programmatic share of digital breaks out of 42% quickly. If they keep it closed, the share stays flat and the growth in Indian digital advertising accrues to platforms that never appear in a DSP's bid stream at all.
Connected TV's measurement problem. India has no accepted currency for connected TV advertising. Linear TV has BARC; connected TV does not. At ₹400–800 CPMs the inventory is the most valuable in the market and the least verified, and programmatic buyers cannot scale what they cannot measure.
The consent-manager count. The registration framework has been live since 13 November 2026. The number of registered consent managers by the middle of 2027 will tell you whether India intends a functioning consent layer or a formal one.
The CCI outcome. A remedy touching Google Ad Manager's integration would change the supply path that most Indian open-web inventory travels on. An unappealable finding of no abuse would entrench it.
Methodology and the limits of these numbers
The market value is modelled, not surveyed. India has no statistical series for programmatic advertising, and the customs and services classifications that might approximate it are shared with adjacent activity. The model anchors 2025 and 2027 to the dentsu-e4m figures, interpolates 2026 at the stated 18.77% CAGR, and projects 2028–2033 on a decelerating path from 15.0% to 8.5% annual growth. The terminal rate reflects the ceiling the market reaches in 2027, when digital advertising is 70% of total Indian advertising and can no longer be the growth source it has been.
Values are converted at a constant ₹87.0 to the US dollar throughout. The Reserve Bank of India's published calendar-2024 annual average was ₹83.67, and the rupee traded in the high eighties through 2025. A different rate moves every dollar figure proportionally and moves the CAGR not at all — constant-rate conversion is a linear transformation. If the rupee depreciates at 3% a year instead, the 2033 dollar figure falls to roughly USD 7,300 million and the dollar CAGR to about 10.0%, while the rupee series is unchanged.
Impressions and blended eCPM are modelled from the value series and a disclosed assumption: a blended programmatic eCPM of ₹55.00 in 2025, growing 2.03% a year as mix shifts toward video, connected TV and retail media. No published source measures a blended India programmatic eCPM. The published benchmarks in this report are premium-format rates, and the open exchange clears well below them.
The research method is 70% secondary, 30% primary. The secondary base is dentsu-e4m, Pitch Madison, FICCI-EY, TRAI, the Gazette of India and the Competition Commission of India. The primary component is the derivation of every figure this report computes itself — per-subscriber revenue, programmatic share of an alternative base, the impression and eCPM series, and the scenario range — none of which appears in any published source.
Table of Contents
Competitive Landscape
Eight firms set terms in Indian programmatic advertising. Below them sits a crowded layer of exchanges, supply-side platforms and specialist vendors, most of which compete for a margin the top eight largely determine. The market is best described as oligopolistic at the top and fragmented beneath it, with high competitive intensity and an unusual feature: several of the largest participants are not primarily advertising businesses at all.
| Tier-1 participant | Position in the Indian chain | Source of advantage |
|---|---|---|
| Search, video, publisher ad server, exchange, DSP | Owns the identifier on an Android-dominant market and the supply path most open-web inventory travels | |
| Meta Platforms | Social feed and in-app demand and supply | First-party identity at national scale; closed auction |
| Amazon | Retail media network, DSP, marketplace inventory | Purchase intent data; the retail media pool growing fastest in the market |
| Flipkart | Retail media inside India’s largest domestic marketplace | Shopper data and closed inventory; the domestic counterweight to Amazon |
| Jio Platforms | Telco-scale reach, JioAds, connected devices | The subscriber relationship itself — the asset every other buyer of attention lacks |
| JioStar | Broadcast and streaming inventory, the largest connected-TV pool | Premium video and live sport; self-described as India’s largest media conglomerate |
| InMobi | Mobile in-app exchange and demand platform | The only Indian-origin platform with global exchange scale |
| The Trade Desk | Independent demand-side platform, connected TV weighted | The default alternative to a walled garden on premium video |
Beneath the eight, Magnite is the largest independent supply-side platform and the principal non-Google route to Indian publisher inventory, while Vertoz represents the listed Indian madtech layer — a domestic platform competing on cost and on programmatic access to inventory that the global exchanges do not index well. Both are exposed to the same pressure: as publishers pull premium inventory into private deals, the independent exchange layer is left with what the publisher could not sell better elsewhere.
The concentration that matters is not advertiser share — it is identifier control. India had 983.29 million wireless internet subscribers against 45.32 million wired at December 2025, according to TRAI. That ratio decides the whole competitive structure. A market that is 96% mobile is a market where the advertising identifier is issued by Google on Android or by Apple on iOS, and where the browser-cookie debate that reshaped Western adtech is largely beside the point. Google’s position in Indian programmatic therefore rests on something more durable than its exchange share: it issues the identifier, operates the dominant device platform, runs the publisher ad server, and owns the largest demand-side platform. The Competition Commission’s investigation order of 8 January 2025 is directed at exactly that stack.
The walled gardens are winning on growth, not on share of the open web. The most consequential competitive fact in this report is the one carried in the market overview: e-retail advertising grew 55.86% to ₹17,601 crore in 2025 while programmatic held at 42.0% of digital. The fastest-growing inventory in India is sold by platforms that own the shopper, and it is not flowing through the open exchange in proportion to its growth. Amazon and Flipkart are structurally advantaged in this because they can refuse: they do not need a third-party exchange to reach demand, and every rupee of intermediary fee they avoid is margin they keep.
Connected TV is the contested ground. FICCI-EY records connected TV advertising revenue growing 42% to ₹9,900 crore in 2025 while linear TV advertising revenue fell to ₹26,300 crore — combined, the two held flat at ₹36,200 crore. That is a substitution, not an expansion, and it is being fought over by the broadcasters who own premium video, the connected-TV platforms that intermediate it, and the independent demand-side platforms that want it sold on open terms. The global addressable TV market sets out the technology and economics of addressable linear and streaming inventory that this Indian segment is converging on.
The agency layer is where the buy actually happens. A handful of holding groups and large Indian independents control the majority of planning and buying. Because much of that buying is executed on principal terms, the competitive battle among DSPs and exchanges is frequently decided in agency trading-desk arrangements rather than in open competition for an advertiser’s business. This is the least visible and most consequential layer of Indian programmatic competition, and no independent Indian dataset measures it.
What to expect. Fee compression in the middle of the chain, consolidation among Indian independents, and a widening gap between the platforms that own identity and the vendors that rent it. The one development that would redistribute position is a remedy in the CCI matter that separates Google’s ad server from its exchange; the one that would redistribute volume is the marketplaces opening their inventory to third-party demand.
Value Chain
An Indian programmatic rupee passes through six hands, and the number of hands is not a detail — it is the commercial structure of the market. Each layer below takes a fee from the same rupee before it reaches the publisher whose inventory was sold, and in India several of those layers are owned by the same firm.
| Layer | Function | Who operates it in India | Structural note |
|---|---|---|---|
| Advertiser | Sets budget and outcome | FMCG, e-commerce, BFSI, telecom, auto dominate Indian ad spend | Concentrated in a handful of categories, so demand is cyclical |
| Agency / trading desk | Plans and executes the buy | The global holding groups plus large Indian independents | Often buys as principal, not agent — reselling inventory it has already bought |
| DSP | Bids for impressions against a target | Google’s DV360, Amazon DSP, The Trade Desk, InMobi, independent Indian desks | Access to premium Indian CTV is the differentiator, not bidding logic |
| Exchange / SSP | Runs the auction, connects supply to demand | Google AdX inside Ad Manager; Magnite; InMobi Exchange; JioAds; Vertoz | AdX sits inside the same product as the publisher’s own ad server — the subject of the CCI matter |
| Publisher | Owns the inventory and the audience | News sites, OTT and CTV platforms, music and audio, gaming and in-app | Increasingly prefers private deals over the open exchange |
| Verification & measurement | Confirms the impression happened and was seen | Global verification vendors; BARC for linear TV | No accepted currency for connected TV — the market’s largest measurement hole |
Where the value actually settles. No Indian source publishes a verified take-rate split across this chain, and that absence is itself the finding: in a market of this size, the division of a rupee between agency, DSP, exchange, SSP, verification and publisher cannot be independently checked. What can be said is directional. The layers that own a user relationship — the marketplace that knows what you bought, the telco that knows who you are, the operating system that issues your advertising identifier — retain value that the auction layers compete away. The layers in the middle, which is where most independent adtech sits, are the ones exposed to fee compression.
The principal problem. A material share of Indian programmatic is bought on principal terms, where the agency purchases inventory and resells it to its own client rather than acting as a disclosed agent. This is legal, common and disclosed in the contracts. It also means the advertiser frequently cannot observe the price the publisher received, which makes the take-rate question unanswerable from the buy side as well as the sell side. Any claim about Indian programmatic efficiency should be read against that opacity.
Supply-path concentration. The open web in India clears disproportionately through Google’s ad stack, where the publisher ad server (DoubleClick for Publishers) and the exchange (AdX) are components of a single product, Google Ad Manager. The Competition Commission of India’s investigation order of 8 January 2025 concerns precisely this arrangement — see the regulatory chapter. Two consequences follow for the value chain regardless of the outcome. First, the supply path is short and the same path is used by most sellers, which caps the fee the exchange layer can charge while entrenching the firm that charges it. Second, any remedy that separates the ad server from the exchange would re-open a layer of the chain that has been structurally closed for a decade.
Publishers moving up the chain. The most important shift in the Indian value chain is not technological. It is that publishers have begun to route around the open exchange deliberately. Premium inventory is held back for private marketplace deals, direct sales, or the publisher’s own demand platform. This raises the publisher’s realisation per impression and shrinks the biddable pool available to a third-party DSP — which is why an independent DSP’s addressable Indian market is considerably smaller than the ₹30,081 crore headline suggests. The same dynamic runs in reverse inside the marketplaces, where the platform is simultaneously the publisher, the exchange and, increasingly, the measurement layer.
Adjacent inventory worth watching in the chain. Two sources of Indian programmatic supply sit outside the conventional publisher list. Digital out-of-home and physical retail signage are moving onto programmatic rails, a shift that connects this market to the global professional AV and display infrastructure market, where the screens are installed before they are sold. And gaming and in-app inventory — a category India supplies in volume — is the most measurement-hostile and highest-fraud segment of the chain, covered in the global gaming and gambling market.
What would change the chain. Three things, in order of probability. Opening marketplace retail media inventory to third-party demand would add the fastest-growing inventory pool to the biddable chain. A functioning connected-TV measurement currency would make the highest-priced inventory verifiable and therefore scalable. And the consent regime commencing on 13 May 2027 would make the data-brokerage layer of the chain accountable for the first time — which may shrink it. All three are discussed in the chapters that follow.
Investment Activity
Capital in Indian programmatic advertising is moving, but almost none of it is disclosed in the form a market report would normally tabulate. There is no Indian equivalent of the deal-value transparency available in the United States or Europe for adtech transactions, because most participants here are divisions of conglomerates, private subsidiaries of foreign parents, or small listed companies whose acquisitions fall below disclosure thresholds. This chapter therefore separates what is documented from what is inferred, and it does so deliberately rather than filling the gap with estimates.
The one transaction that restructured the market
The formation of JioStar — the combination of Reliance’s Viacom18 with Disney’s Star India — is the most consequential media transaction in recent Indian history and it was completed in November 2024. JioStar describes itself as India’s largest media conglomerate, spanning entertainment, sports, and a streaming platform, with distribution and consumer products arms.
For programmatic advertising the significance is not the deal’s size but its shape. The transaction consolidated the country’s largest pool of premium video and live-sport inventory under one owner. Because live sport and premium video are the inventory that commands the highest CPMs and the strongest advertiser demand, that consolidation changed the negotiating position of every demand-side platform in the market at once. It also created the single most important counterparty for any connected-TV programmatic strategy: there is no way to build meaningful scale in Indian connected TV without trading with the consolidated entity.
The second-order effect is on the supply path. A publisher of that scale has less need of a third-party exchange than a fragmented one does, and is better placed to sell privately, directly, or through its own demand relationships. Consolidation of premium inventory therefore pushes the market away from open programmatic — which is one mechanism, alongside retail media, holding the 42.0% share flat.
Where capital is actually being deployed
Four categories absorb most of the identifiable investment:
| Category | What the money buys | Evidence position |
|---|---|---|
| Premium content and rights | Live sport, film libraries, original streaming — the inventory that carries the ₹400–800 CPMs | Consolidation into JioStar demonstrates the direction; individual rights values are contracted privately |
| Retail media infrastructure | Ad-serving, measurement and attribution inside marketplaces and quick-commerce apps | Visible in the 55.86% growth of e-retail advertising to ₹17,601 crore; not separately capitalised in any disclosure |
| Identity and clean rooms | Consent management, identity resolution, privacy-preserving matching ahead of May 2027 | Inferred from the regulatory timetable; no Indian dataset tracks this spend |
| Platform capability abroad | Acquisitions and product build in markets where an impression is worth more | Documented in the annual reports of the listed Indian participants |
The export imperative. The fourth row is the one that follows directly from this report’s central arithmetic. At ₹292 of programmatic revenue per connected Indian per year — a twelfth of monthly telecom ARPU — the domestic market cannot fund the product development that a globally competitive adtech platform requires. Indian adtech companies therefore grow by selling into markets where the same impression clears at several times the price. The listed Indian participants disclose this plainly in their annual reports: Affle’s FY2024-25 annual report and Vertoz’s FY2024-25 annual report both describe businesses whose revenue base is substantially international, and Vertoz positions itself explicitly as an AI-powered madtech and cloudtech platform rather than a domestic media business.
This is a structural feature of the Indian market, not a failure of ambition. A company that earns in dollars and spends in rupees can fund engineering that a purely domestic competitor cannot. It also means the Indian adtech sector’s health is only partly a function of Indian programmatic growth — a point frequently missed in commentary that treats domestic market size as the sector’s addressable opportunity.
What is not disclosed, and why it matters
Three specific gaps should be flagged rather than papered over.
No verified deal values for Indian adtech M&A. Acquisitions by the listed Indian platforms are typically small enough to fall below the threshold requiring disclosure of consideration, and the strategic rationale is disclosed without the price. Any table of Indian adtech deal values circulating in the market is, in the main, assembled from press reports rather than filings.
No domestic venture funding series. Indian adtech venture activity is not tracked by any published Indian dataset comparable to those covering financial services or consumer internet. Statements about the direction of early-stage capital in this sector are therefore inference.
No separation of advertising capex inside conglomerates. The largest participants — a telco, two marketplaces, a media conglomerate, and two global platforms — do not break out advertising infrastructure investment in their segment reporting. The investment is real and visible in product behaviour; it is not visible in a number.
Assessment. Investment trend direction is rising, recent M&A activity is present, and capital intensity in this market is medium: the software layer is asset-light, but the inventory it monetises is not, and the firms that control the inventory are the ones making the largest capital commitments. The strategic logic of the next five years is straightforward — own the content that carries the premium CPM, own the commerce data that makes it targetable, and own the identity that survives the consent deadline.
Technology & Innovation
India’s programmatic technology problem is not a bidding problem. Programmatic bidding has been solved, cheaply and globally, for a decade. India’s problem is identity, measurement and verification — three layers where the technology is either absent, imported, or controlled by a single firm, and where the market’s lowest-cost position in the world is directly connected to the weakness of all three.
Identity: the cookie argument never applied here
Every Western account of programmatic privacy in the last five years has been a story about third-party cookies. India never had that story, because India is not a browser market. TRAI’s December 2025 data puts wireless internet subscribers at 983.29 million against 45.32 million wired — so the overwhelming majority of Indian inventory is served inside an application, not a page. What identifies a user is the mobile advertising identifier: the Google Advertising ID on Android, the Identifier for Advertisers on iOS.
The consequence is structural. On a market that is predominantly Android, a single firm issues the identifier for most of the addressable population, and controls the consent surface through which that identifier can be reset or restricted. Apple’s App Tracking Transparency, which cut identifier availability on iOS, had a severe effect on iOS inventory and a comparatively limited one on the Indian market as a whole. When the Digital Personal Data Protection Rules commence on 13 May 2027, the statutory consent obligation will land on this identifier — the one the market actually uses — rather than on a cookie the market never relied on.
Auction mechanics and the supply path
Indian open-web supply clears through a small number of paths. The dominant one is Google Ad Manager, in which the publisher’s ad server and the AdX exchange are components of one product. Header bidding and Open Bidding were the market’s attempted answers to that integration; Open Bidding in particular put Google in the position of running the auction while also bidding into it. The CCI’s investigation order of 8 January 2025 records a prima facie view on this, and on the Unified Pricing Rule operating as a de facto price-parity clause. None of it has been adjudicated.
Supply-path optimisation — the practice of collapsing redundant reseller hops so demand reaches supply directly — is the main technical lever an Indian buyer has over cost today. It works, and it is why the number of intermediaries in a given Indian bid is falling. It does not address the underlying concentration, because collapsing hops inside a single stack leaves the stack intact.
Connected TV: the highest-value inventory with the weakest measurement
Connected TV is where Indian programmatic technology is most valuable and least resolved. At ₹400–800 per thousand impressions it is the most expensive inventory in the market, and it grew 42% to ₹9,900 crore in 2025 against linear TV advertising falling to ₹26,300 crore. FICCI-EY expects connected TV advertising to reach ₹16,400 crore by 2028.
The technical prerequisites largely exist: server-side ad insertion delivers addressable advertising into a stream, and the major Indian streaming platforms run it. What is missing is a currency. Linear television in India has BARC. Connected television has no accepted third-party measurement standard, which means a buyer is asked to pay a premium price for an impression whose delivery cannot be independently verified to the standard applied to the cheaper medium it replaced. That gap, not technology, is what caps programmatic connected-TV growth in India.
Retail media: the strongest technology stack in the market, in the least open place
The retail media networks operated by the large marketplaces hold the best first-party data in Indian advertising — what a person actually bought, at what price, in what basket — and they run it through closed auctions. Technically these are sophisticated systems: identity resolution against logged-in shoppers, deterministic attribution, on-site and off-site extension. Commercially they are the opposite of an open exchange.
This is the core tension in Indian programmatic technology. The best data is available only through the least biddable inventory, and the most biddable inventory runs on the weakest data. The market’s 42.0% programmatic share of digital is, in large part, the arithmetic of that split. The scale of the underlying commerce is set out in the global e-commerce market, and the platform economics that govern who gets to sell into it in the global e-commerce platform market.
Fraud, invalid traffic and the cost of being cheap
India’s low impression prices have a second-order effect that is rarely stated: at ₹55 per thousand blended, the economics of verifying an individual impression are unfavourable. Verification vendors price per impression, and a market where a thousand impressions are worth less than a dollar leaves little room for the verification that a market at ten times the price takes for granted. The result is that invalid traffic detection in India is thinner than in higher-priced markets, which in turn suppresses what sophisticated buyers are willing to pay — a self-reinforcing floor. Gaming and in-app inventory, where supply is abundant and attribution is hardest, sits at the worst end of this.
Where innovation is actually happening
Three areas, in order of commercial significance:
- Bid optimisation and creative generation. Machine-learning bidding is mature and commoditised; the live frontier is generative creative at scale and its interaction with brand safety. This is where most Indian adtech research and development spend is now directed.
- Data clean rooms. As consent obligations approach, the ability to match audiences across parties without exchanging raw identifiers becomes the mechanism by which any cross-publisher targeting survives 13 May 2027. Clean-room adoption in India is early and concentrated among the largest advertisers.
- Connected-TV identity. Resolving a household across a stream, a phone and a purchase is the technical problem that would unlock the premium inventory — and the one most likely to be solved inside a walled garden rather than outside one.
Assessment. Innovation intensity in Indian programmatic is high and technology maturity is at the growth stage rather than mature. But the direction of innovation is defensive: a substantial share of it is being built to preserve targeting capability under a consent regime that does not yet exist, and to verify inventory that is priced too low to verify properly. The market is not short of engineering. It is short of measurement it can trust and identity it is permitted to use.
Market Risk
The risks to this forecast are not evenly distributed, and two of them cut in opposite directions. The most likely outcome is not the base case in this report but a market that grows a little slower than modelled while consolidating faster than modelled. The risks below are ordered by their capacity to move the number, not by their likelihood of making headlines.
| Risk | Likelihood | Impact on forecast | Horizon |
|---|---|---|---|
| Programmatic share stays pinned near 42% — retail media and premium video remain closed | High | High — drives the ₹73,056 crore conservative case | 2026–2030 |
| Consent regime suppresses third-party data after 13 May 2027, shifting budget to first-party platforms | Medium | Medium to high — hits the open exchange hardest | 2027–2030 |
| Yield deflation in FMCG and mid-market retail continues at the 8–12% pace seen in 2025 | Medium | Medium — removes the 2.03% eCPM gain and with it roughly a third of value growth | Now |
| Connected-TV measurement never resolves, capping the highest-CPM inventory at private deals | Medium | Medium — the single largest upside foregone | 2026–2033 |
| CCI remedy restructures Google Ad Manager, separating ad server from exchange | Low to medium | High if it happens — could raise open-web programmatic share | 2027 onwards |
| Rupee depreciation converts rupee growth into materially lower dollar growth | High | Low for the rupee series, high for the dollar series | Continuous |
| Advertiser concentration in FMCG, e-commerce and BFSI makes the market cyclical | Medium | Low to medium — affects timing more than level | Any |
The structural risk: substitution, not competition
The most under-appreciated risk in this market is substitution risk, and it is rated high in this report for a specific reason. Programmatic advertising in India is not primarily threatened by a rival auction technology. It is threatened by the possibility that the money simply goes somewhere that is not an auction at all — into sponsored listings inside a marketplace, into a direct deal with a streaming platform, into an influencer, into branded content. Every one of those is growing at least as fast as programmatic, and the fastest of them, e-retail advertising, grew 55.86% in 2025.
This is visible in the market overview’s central number: programmatic held 42.0% of Indian digital media spend through a year in which digital advertising grew 19%. A technology that is not gaining share in a market growing that fast is not displacing anything. The substitution thesis is not speculative — it is what the 42% already shows.
The regulatory risk runs in an unexpected direction
Most market participants treat India’s data protection regime as a compliance cost. The larger commercial risk is different and is frequently missed. Consent obtained through a first-party relationship — the telco that bills you, the marketplace that delivered your order, the platform you log into — is legally cleaner and operationally simpler than consent assembled across a chain of third parties. A regime that raises the cost of third-party data therefore advantages exactly the walled gardens that are already taking the growth.
So the 13 May 2027 commencement could reduce programmatic share of digital rather than increase it, by making the open exchange’s inventory harder to target while leaving closed platforms unaffected. That is a genuine downside to the base case, and it is why the conservative scenario is not merely a symmetric deceleration.
Measurement risk and the fraud that follows from it
At a blended ₹55 per thousand impressions, verification is expensive relative to the value of what is being verified. Thin verification admits invalid traffic; invalid traffic suppresses what sophisticated buyers will pay; lower prices further discourage verification. India’s connected-TV inventory, at ₹400–800 CPMs and with no accepted measurement currency, is the segment where this matters most, because it is where the gap between price and verifiability is widest. A buyer paying a premium price for an unverifiable impression is the most likely source of a future correction in Indian programmatic pricing — in either direction.
Currency risk, stated plainly
Every dollar figure in this report is converted at a constant ₹87.0. That is a reporting convention, not a forecast. The rupee has depreciated against the dollar over every long horizon in the data. If it depreciates 3% a year, the 2033 dollar value falls from USD 9,361 million to roughly USD 7,300 million and the dollar CAGR from 13.26% to about 10.0%, while the rupee series — which is what an Indian advertiser actually spends — is unchanged. Readers comparing this report to others should check the conversion basis before concluding that two forecasts disagree.
What would falsify this report
Three observable outcomes would show the analysis to be wrong. If programmatic’s share of Indian digital media spend rises above 48% before 2029, the substitution thesis is wrong and the market is genuinely opening. If blended Indian CPMs fall in nominal rupees for two consecutive years, the yield thesis is wrong and the market is in a volume trap rather than a yield transition. And if the e-retail advertising growth rate falls below digital’s own growth rate, retail media is not the mechanism holding the share flat and the central structural claim needs rebuilding. None of these is currently indicated. All three are measurable from published sources within the forecast window.
Regulatory Landscape
Indian programmatic advertising is regulated by four instruments that were designed for other things, plus one that was designed for it and has not yet commenced. There is no ePrivacy equivalent, no dedicated adtech statute, and no regulator with advertising technology as its remit. That is the first thing to understand about the compliance position: the constraint arrives sideways, principally through data protection and competition law.
1. The Digital Personal Data Protection Rules, 2025
The Digital Personal Data Protection Act 2023 was brought into operation by the Rules notified in the Gazette of India on 13 November 2025 as G.S.R. 843(E). Rule 1(2) commences the Act in three tranches, and the schedule is the operative fact for anyone buying media in India.
| Tranche | Provisions commenced | Subject matter |
|---|---|---|
| 13 November 2025 on notification |
ss.1(2), 2, 18–26, 35, 38–43, s.44(1) and (3) | Definitions, and the constitution and powers of the Data Protection Board of India |
| 13 November 2026 twelve months |
s.6(9); s.27(1)(d) | A single sub-clause of the consent provision, and part of the consent manager provision |
| 13 May 2027 eighteen months |
ss.3–5, s.6(1)–(8) and (10), ss.7–10, ss.11–17, s.27 except (1)(d), ss.28–34, 36, 37, s.44(2) | Application and grounds; notice; consent in full; legitimate uses; the data fiduciary’s general obligations; data principal rights and duties; consent managers in full; the Board’s adjudication and appeal machinery |
Source: Digital Personal Data Protection Rules, 2025, G.S.R. 843(E), Gazette of India, 13 November 2025, rule 1(2).
The practical reading is that the regulator has existed since November 2025, while the obligations it will enforce do not begin until 13 May 2027. Section 27 — consent managers — is split, with one sub-clause live at twelve months and the remainder at eighteen. An organisation therefore has eighteen months from gazette notification, not from today, to establish lawful basis, rewrite notice and consent flows, map data-fiduciary relationships across its vendor chain, and implement the data-principal rights the Act creates.
Why this bites harder in India than the equivalent did elsewhere. The obligation attaches to the data fiduciary, and Indian programmatic runs through long chains — advertiser, agency, trading desk, DSP, exchange, SSP, publisher, verification vendor. In a principal-model buy, several of those entities hold personal data on terms the advertiser never sees. Establishing who is the fiduciary for a given identifier, and on what consented purpose it is held, is the single hardest operational problem the new regime creates for this market. It is also the one that cannot be solved by configuration: it requires contract changes across the chain.
A secondary effect is likely to be structural rather than merely administrative. Consent obtained directly by a platform with a first-party relationship is cleaner than consent assembled from a third-party data market. A regime that raises the cost of third-party data raises the relative value of walled-garden inventory — which would push programmatic share of digital down, not up, after 2027. That is a genuine downside risk to the forecast in this report and is treated as such in the market risk chapter.
2. Competition law: the CCI’s adtech investigation
On 8 January 2025 the Competition Commission of India passed an order under Section 26(1) of the Competition Act in Case No. 34 of 2024, directing the Director General to investigate Google’s conduct in adtech intermediation. The order was passed on a prima facie view, and the Record of Proceedings names Alphabet Inc., Google LLC, Google International LLC and Google India Private Limited.
It is an investigation order. It is not a finding of abuse, and no conduct has been adjudicated. That distinction matters to anyone relying on it. The prima facie view concerns three practices: the tying of DoubleClick for Publishers with AdX within Google Ad Manager; Google’s dual role in Open Bidding, where it operates the auction while also bidding into it; and the Unified Pricing Rule operating as a de facto price-parity clause. The proceeding builds on an earlier prima facie order in a related matter.
The outcome is the single largest regulatory variable in Indian programmatic. A remedy that separates the publisher ad server from the exchange would restructure the supply path on which most Indian open-web inventory is sold. A finding of no abuse would entrench it. Either way the order puts on the formal record a set of allegations about auction design that the market has discussed informally for a decade.
3. Advertising standards and content rules
The Advertising Standards Council of India operates a self-regulatory code that binds most major Indian advertisers and is enforced through the media owners rather than by statute. Its influence on programmatic is indirect but real: compliant creative is a precondition for premium inventory, and platform-level brand-safety controls are frequently calibrated to ASCI rather than to any statutory standard.
Alongside it sit the general content and platform rules applicable to intermediaries and publishers, which govern what may be advertised and how disclosures must appear. For programmatic specifically, the practical constraint is that in a real-time auction the creative is served before any human reviews it, so compliance depends entirely on pre-clearing creative at the point of upload. That is a control most Indian advertisers operate at the agency level and few operate at the DSP level.
4. What is not regulated
Three gaps are worth naming because they shape commercial behaviour. There is no statutory measurement standard for digital or connected-TV advertising — BARC covers linear television, and nothing equivalent covers the ₹9,900 crore connected-TV advertising market. There is no transparency requirement obliging an intermediary to disclose the price the publisher received, which is what makes the principal-model question unresolvable from outside. And there is no dedicated adtech licensing or registration regime, so market participation requires no permission at all.
Net assessment: high regulatory complexity, compliance-driven entry, and a single date on which the operating environment changes. Companies that treat 13 May 2027 as an IT project will be late. The work is contractual and relational — who holds what data, on whose consent, for which purpose — and it runs the length of the value chain described earlier in this report.